Thursday, June 12, 2014

What is Carl Icahn Thinking in Taking an Interest in Family Dollar?

Last week, the financial world learned that Carl Icahn had taken a 9.4% interest in Family Dollar.  The question for this move is, why?  Let's start by looking at the industrial sector, which the FINVIZ website classifies as "discount variety stores."  The top three players here are Wal-Mart, Target and Costco, which no one is going to target for a hostile takeover, simply based on the sheer size of the companies. 

However, the next group of companies -- Dollar Tree, Dollar General and Family Dollar -- are smaller and therefore far more attractive.  From a purely tactical perspective, Family Dollar has the smallest market cap at 7.56 billion, meaning this company is simply easier to attack.  And, to make this possibility more attractive, family dollar stock has under-performed competitors over the last three years by a wide margin:


When a stock underperforms at this level its for one (or a combination of) of three reasons: the sector is in a downturn, management is not performing well or the market is simply over-looking a bargain.  Icahn clearly believes the latter is the case.  And, I agree with him.

FDO is clearly the "red-headed stepchild" of the group.  And, it's not for lack of revenue performance:


As the chart shows, the year over year revenue growth of FDO, DLTR and DG are all solid (FDO is in orange and has not reported its final 2014 numbers yet).

What Icahn is thinking is this company can be merged with one of its competitors to achieve better financial efficiencies.  Consider a comparison of the three companies' net margins:


Dollar tree is clearly the winner of the three in financial efficiency, with a net margin between 2%-4% higher than FDOs.   

And it's not just in the net margins.  The company's cash/investment ratio has been positive for the last three years, indicating they can self-finance expansion through existing sales.  An expand they have, increasing their store count from 6655 in 2009 to 7916 in 2013.   They have also moved to better manage their own internal infrastructure:

At the end of fiscal 2013, each distribution center served an average of 720 stores, compared to 744 stores in fiscal 2012. Our tenth distribution center in Ashley, Indiana, began operations in June 2012, and our eleventh distribution center in St. George, Utah, began operations in July 2013. The opening of the eleventh distribution center reduced the average stem miles between our distribution centers and our stores by approximately 7% at the end fiscal 2013, as compared to the end of fiscal 2012.
 
The bottom line is pretty clear: this is a good company that could easily be merged into one of its larger rivals, thereby achieving better efficiencies.  What Icahn has done is to purchase a solid percentage of shares in a small (as expressed in market cap) company that will make a good partner for one of its two larger rivals.
 

Wednesday, June 11, 2014

The REAL "real unemployment rate" for May 2014


 - by New Deal democrat

This month the usual suspects did not run any "real unemployment rate" articles, which assume there is no such thing as Boomers retiring in droves. Only t
he EPI updated its "missing workers" number based on estimates from a research paper published 7 years ago.

In fact, let me make a general announcement that will save you a lot of time reading useless or misleading analysis:  any time you see an article citing the employment to population ratio, or the civilian labor force participation rate, for the entire population, ignore it.  It's useless BS garbage. Retired Boomers are skewing both numbers drastically,  Both numbers are going to trend down for years, as Boomers move out of the labor force and into senior citizenship.

With that caution, let me update the "REAL real unemployment rate."

In order to be counted among the unemployed for purposes of the monthly jobs survey, a person must have actively looked for a job during the reference period.  But what about people who are so discouraged that they have completely stopped looking for work and have simply dropped out of the labor force?

The monthly household jobs survey measures exactly this in a statistic called "not in labor force, want a job now."  Here's what that metric shows for the last 10 years:


The number of discouraged workers rose by nearly 2,000,000 in the wake of the Great Recession. In 2012 and 2013, it declined by about 1/3 of that number.  Disturbingly, it has risen since the beginning of this year by over half a million.  This looks like a real trend.  I suspect it is fallout from the termination of long term unemployment benefits.  Supposedly this was going to spur those lazy moochers < /snark > to finally go out and find employment.  Instead, it looks like it has caused a fair number of  the long-term unemployed to simply give up hope.


In order to find out what the "real" unemployment rate is, including such discouraged workers, we simply add the number of people shown above to both the numerator (unemployed) and denominator (civilian labor force, which excludes those adults not interested in jobs, like retirees) of the statistics used for the unemployment rate.  Here's what that shows for the last 10 years:


The usually reported unemployment rate (U3, in red) is currently 6.3%.  The "real" unemployment rate including those who want a job but haven't looked (blue) is back up to 10.0%.


While this is by no means good, it is important to compare apples to apples.  Note that the current rate is equivalent to that of late 1994, and even at the height of the late 1990's tech boom, the best economy the US has seen since the 1960's, this rate was 6.7%.


We can perform a similar calculation to get the "real underemployment rate," i.e., which adds those who are working part time for economic reasons or are otherwise marginally attached to the workforce:


The "real" underemployment rate is 16.1% (red) vs. 12.2% (blue).  Again, note that even in the 1990's tech boom, this rate never got below 9.9%.


Back in March I wrote that The cutoff in unemployment wasn't just vile, it explained a lot of Q1 economic weakness.  Almost 1/3 of all of the people who affected in all of 2014 were cut off in January, and more have been cut off each month since.  It appears this is showing up in the "REAL real unemployment rate," even if not the official one.


Recent UK News Points to Stronger UK Economy and Pound Sterling

This is up at XE.com

http://community.xe.com/forum/xe-market-analysis/recent-uk-numbers-point-stronger-uk-economy-and-pound

Tuesday, June 10, 2014

Ranking The Major Central Banks From the Most Likely To Least Likely to Raise Rates

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/ranking-major-central-banks-order-most-likely-least-likely-raise-rates

My Questions About Apple

When my wife and I were house hunting, I was obsessed with getting an I-Phone.  I remember telling her as we were out driving, "If I had an I-phone, I could look at a map and find near-by restaurants."  I eventually purchased one and was very pleased.  I later upgraded to the then newer model and was still happy. 

However, over the last year or so I became less than happy.  Service was slower than anticipated.  And, finally, the new operating system that was launched about 6-8 months ago was very unsatisfactory as it literally ate battery life.  The last straw was my inadvertently dropping the phone shattering the glass.  Now I have a Galaxy 5 which I'm very pleased with along with a new data provider.

All that being said, there are two points on Apple's financials that really leave me wondering about the company.

First of all is the lack of R&D.  Here's a chart of R&D expense as a percentage of revenue:


The response to this is these percentages actually represent billions of dollars of expense -- and they do.  The latest figure represents over $4 billion in expenses.  But, in response, consider this: what was the last really big Apple product?  It was the I-Pad and that was a long time ago in technology years.  That, combined with the death of their primary creative mind in Steve Jobs indicates they should be spending a lot more to come up with the next big thing.

Here is their statement from the latest 10-K regarding R&D:

Because the industries in which the Company competes are characterized by rapid technological advances, the Company’s ability to compete successfully depends heavily upon its ability to ensure a continual and timely flow of competitive products, services and technologies to the marketplace. The Company continues to develop new technologies to enhance existing products and to expand the range of its product offerings through research and development, licensing of intellectual property and acquisition of third-party businesses and technology. Total research and development expense was $4.5 billion, $3.4 billion and $2.4 billion in 2013, 2012 and 2011, respectively.

10-K's are notoriously bland documents, so we're not going to see a statement like, "Shit.  Steve Jobs, the man who revolutionized multiple businesses is dead and we're now up a creek without a paddle."  At the same time, there doesn't seem to be any acknowledgement that their business is changing.   

Second, according to the company's latest 10-K, they have $92 billion in marketable securities on their balance sheet.  Now, short-term investments are part and parcel of treasury management nowadays, so the act of doing this shouldn't be an issue.  But, here's the key question for me: with this amount of securities, isn't Apple now as much a mutual fund as a technology company?  Consider this page from their latest 10-K which discloses their investment philosophy etc....  It looks a great deal like a mutual fund disclosure. 

These questions are actually periphery to the company's basic business.  They own some of the strongest tech products ever and command a very loyal following.  But, I also think it's important to remember that the times are changing for Apple and we need to change the way we look at the company in order to tailor our expectations accordingly.


Saturday, June 7, 2014

Weekly Indicators for June 2 - 6 at XE.com


 - by New Deal democrat

My Weekly Indicators piece is Up at XE.com.

The high frequency data is booming.

Friday, June 6, 2014

Live-blogging D Day hour by hour, as it happened


 - by New Deal democrat

For those of you who are interested, the blog World War 2 today, which normally posts one item per day, "live-blogging" what happened in the war exactly 70 years earlier, has been running numerous posts since late on June 4, on almost an hourly basis by now, as to the immediate prelude to and operation of the D Day landings in Normandy.

This is absolutely top-notch blogging, giving you a real sense of "you are there" as each facet of the landings begins to unfold.  By all means check it out.

May jobs report: same old, same old


- by New Deal democrat

HEADLINES:
  • Not in Labor Force, but Want a Job Now: up +292,000 to 6.438 million
  • Employment/population ratio ages 25-54: 76.4% down -0.1%
  • Average Weekly Earnings for Production and Nonsupervisory Personnel: $20.54 up $.03
In May 217,000 jobs were added to the US economy.  The unemployment rate was unchanged at 6.3%.  April was revised downward by -6,000. There was no revision to the March number.  

Since we knew the general range of job growth and unemployment, as I indicated last Sunday I would focus on the 3 above headline numbers as to "real" unemployment and wages.  These numbers for May tell us that we made no headway - in fact we went backward -  in bringing back discouraged workers into the workforce and into jobs.  

Those who want a job now, but weren't even counted in the workforce were 4.3 million at the height of the tech boom, and were at 7.0 million a couple of years ago.  The big increase this month was not welcome.

After inflation, real hourly wages probably declined slightly from April to May, but April was revised higher.  The YoY change in average hourly earnings is +2.4%.

The more leading numbers in the report tell us about where the economy is likely to be a few months from now. These were generally positive.
  • the average manufacturing workweek rose from an upwardly revised 40.9 hours to 41.1.This is one of the 10 components of the LEI, and will contribute significantly towards a positive number.

  • construction jobs increased by 6.000. YoY 188,000 construction jobs have been added.

  • manufacturing jobs  also increased by 10,000, and are up 105,000 YoY.

  • temporary jobs - a leading indicator for jobs overall - increased by 14,300.

  • the number of people unemployed for 5 weeks or less - a better leading indicator than initial jobless claims - rose by 15,000 from 2,447,000 to 2,461,000 compared with December's 2,255,000 low.

Other important coincident indicators help us paint a more complete picture of the present:

  • The average workweek for all nonsupervisory workers remained unchanged at 33.7 hours.

  • Overtime hours were unchanged at 3.5 hours.

  • the index of aggregate hours worked in the economy rose by 0.2 from 108.1 to 108.3.  This is a new record.

  • The broad U-6 unemployment rate, that includes discouraged workers decreased from 12.3% to 12.2%.

  • The workforce rose by 192,000. (partially offestting last month's number, which was the big Harbinger of DOOOOM at -806,000) Part time jobs for economic reasons decreased by 196,000.
Other news included:
  • the alternate jobs number contained in the more volatile household survey increased by 145,000 jobs.  The household survey jobs numbers had been lagging the establishment survey numbers, but as expected this difference has now been entirely made up, with the household survey showing a 1,895,,000 increase in jobs YoY.

  • Government jobs increased by 1,000.
  • the overall employment to population ratio for all ages 16 and above was unchanged at 58.9%, and has risen +0.2% YoY. The labor force participation rate was also unchanged at 62.8% , and has fallen by -0.6% YoY (but remember, this includes droves of retiring Boomers).
In summary, this report was another good report, with good internals, based on the standard of the last decade.  It is a mediocre report when measured against a longer timeframe.

Where the report is disappointing is in making headway against the real slack in the labor force, including discouraged workers, and in wages, which are still stagnant.

Same old, same old.


Thursday, June 5, 2014

Of corporate profits, progressives, and the business cycle


 - by New Deal democrat


Yves Smith has a piece up at Naked Capitalism this morning on "why economists don't recommend real remedies" in which she says:
I hate criticizing writers whose work I generally like, but as a contrast to this talk, I suggest you look at a new post by Ed Lambert at Angry Bear. In it, a left-leaning blog (and remember, Angry Bear has been vigorous in its defense of Social Security), we see an strong argument against having workers get a better deal. Why? It will lower corporate profits, which will lower asset prices and give the confidence fairy a sad. I am not making that up. This shows the degree to which liberal economists have been intellectually captured by the orthodoxy and/or have been inculcated to live in fear of the Market Gods. If you can’t get parties who are ideologically sympathetic to argue for real remedies rather than a “recovery” only for the top tier, how can you possibly exert any pressure on the minions of the 1%?
 (my emphasis)

Except Lambert isn't saying that labor's share of productivity should stay low.  To the contrary, Here's his concluding paragraph:
Profit rates just simply went too high and labor share went too low. Bringing these back into a sustainable balance will trigger an unstable financial situation, which would likely produce a recession.
(my emphasis)

In what sense is stating that labor share is too low arguing that it shouldn't be increased?  Lambert is simply stating a fact from business cycle analysis:  recessions don't happen when corporate profits are increasing, they happen when corporate profits are decreasing.  Here's his explanation:
Firms do not want to see their profit rates fall… even though their aggregate profit rates are very high already. If profit rates start to fall, asset prices will fall. This will have a cascading effect to investment and consumption. The problem is that asset prices are dependent upon very high profit rates which are based on a historically very low labor share. This situation is unsustainable. People are demanding higher wages because they are struggling terribly. Moreover, government assistance increases to make up for low wages. There are calls for higher taxes on capital.
Even if labor share rose and profit rates were to back down from 9% to a more sustainable 8% (which is still high historically), asset prices would fall and there would be a negative cascading effect upon the economy.
The simple fact is, as I pointed out last week in a post at XE.com
Corporate profits, particularly as adjusted by unit labor costs, are a long leading indicator for the economy,  They typically decline by at least one year before the overall economy does, and sometimes make their high near mid-cycle.
Unsurprisingly, given the rest of the GDP report, Q1 corporate profits, both unadjusted and as adjusted by unit labor costs, declined....
Corporate profits are a long leading indicator, typically turning down over a year before the next recession.  That is simply a fact, as originally shown in detail (pdf) by Prof. Geoffrey Moore, who was instrumental in establishing the index of Leading Economic Indicators and went on to co-found ECRI.

If you don't believe me, here is  Cris Sheridan at Financial Sense discussing the downturn in corporate profits in the first quarter:
If you do this for the 60 years of data and 8 complete business cycles shown in the chart [below], you’ll find that BEA’s measure of corporate profits peak on average over a year before the stock market peaks and over two years before the onset of an economic recession.


Recessions typically mean that millions of workers get laid off.  Does Yves Smith want that?

The question is, if there were a uniform increase in corporate taxes, would that operate the same as when forces naturally generated by the economy lead to a decrease in profits?  Typically, when faced with a sustained downturn in profits, companies start looking for ways to economize. This can include hiring freezes, and if the squeeze continues, layoffs. But what if every company, across the board, faced a uniform increase in taxation?  Would they react the same to that as to a decline in profits endogenous to the economy (since their relative share of profits compared with other companies would be the same)?  

Like both Edward Lambert and Yves Smith, I believe that the Labor share of productivity is too low and must be raised.  So long as both profits and wages rise in tandem, we should get broad-scale growth.  At the same time, I know that a decrease in corporate profits typically has preceded a recession. 

While I think Lambert is correct that stock prices would decline, as the "p" part of the P/E ratio would have declined, it is well to remember that the stock market has famously "predicted 9 of the last 4 recessions." In other words, an externally imposed, uniform decrease in profits, as opposed to an endogenous decline, might not create the "cascade effect on the economy" from asset price declines that Lambert fears. While a decrease in stock prices would create a negative wealth effect, the increase in consumer spending by Labor would likely more than make up for that (since Labor spends more of its income than the wealthy).  And another paradoxical result of the business cycle is that employment doesn't lead spending, it is consumer spending that leads jobs.

 To test this, we need to examine past examples of the sequelae to increases in corporate profits.  Needless to say, those would be nearly non-existent after 1980. I'll poke around and if I find something worth following up on here, I'll post it.

Wednesday, June 4, 2014

Joe Weisenthal needs to start reading my Weekly Indicators column again


 - by New Deal democrat

I guess Joe Weisenthal of Business Insider must have stopped reading my Weekly Indicators columns, because otherwise he would have known two weekends ago that Gallup personal spending is at its highest since 2008, instead of posting it on Monday, and he would have known about the Spring spring two months ago instead of yesterday.

By the way, Joe, our new agreement with XE.com allows Business Insider to pick up the items we publish there, so long as credit for the original publication goes to XE along with a link.

So BI readers could have found out about the downturn in corporate profits, and why it isn't a big deal yet,  last week instead of waiting to Hussman and Shedlock yesterday to claim it as a harbinger of DOOOOOM!

Just sayin'.

P.S.:  On another matter, the new post-recession high in vehicle sales in May is about the 101st confirmation that there isn't going to be any economic downturn this year.  According to Prof. Edward Leamer's research, car sales are typically the second domino to fall, before the onset of a recession, after housing.  Typically vehicle sales have turned down over half a year before the onset of any recession.

Tuesday, June 3, 2014

Sunday, June 1, 2014

Euro and Pound Break Uptrend

This is up over at XE.com

http://community.xe.com/forum/xe-market-analysis/euro-and-pound-break-uptrends

The three data points I'll be watching for in this week's employment report


 - by New Deal democrat

This Friday we'll get the employment report for May.  Since it's going to be a busy news week, I thought I'd put right out front what I'll be paying particular attention to in that report, and it boils down to three specific data points.

Unless there is a huge surprise, we know that the economy will have added jobs, and the unemployment rate will be somewhere over 6%, and probably won't move much.  In other words, there's no reason to obsess over the headline numbers at this point.

Meanwhile, the economy as a whole has moved beyond the "recovery" stage into the "expansion" stage.  Production, sales, income, and almost certainly as of this Friday employment will all have exceeded their pre-recession levels.  But while the economy as a whole is continuing to expand, and there's no reason to think it won't continue to expand at least through the end of this year, on a per capita basis American households are still languishing.  Wages have employment have lagged.

So it is three measures of wages and employment that I will be particularly observant of this Friday:

1.  Not in Labor Force, Want a Job Now

This is a self-explanatory data series.  As I've pointed out repeatedly in the last few months, this is the only number you need to know to determine the "real" unemployment rate.  Even at the height of the tech boom, there were about 4.3 million people who fit this decription.  That number rose to 7 million in the wake of the recession, but has declined significantly in the last 18 months:


As of last month, there were 6.146 million people in this category. A decrease would be positive, and a decline to under 6 million would be a good number.  I'd like to see this number decline to about 5.5 million by the end of this year.

2.  The Employment - Population ratio for ages 25-54

This is of a piece with the first number.  I am selecting this age group because it excludes retiring Boomers and college students.  This ratio was as high as 80.3% in 2007 and as low as 74.8% in 2009 and 2010.  It has risen from 76.0% to 76.5% in the last 6 months:


A continuing increase would be welcome.  I would like to see this number at 77% or higher by the end of this year.  That wouldn't be great, but it would be nearly half the way back.

3.  Average hourly earnings of production and nonsupervisory employees

While a median measure would be nicer, those aren't reported on a monthly basis.  This average measure does not include managerial personnel, so is a good monthly measure of how the average American wage or salary worker is doing.  To get to the "real" average wage, in the below long term graph I have normed by the CPI:


You can see that real wages peaked in the 1970s, and made a partial comeback in the 1990s tech boom.  The big increase in the last recession is when gas prices declined to $1.50 a gallon, and we actually had significant YoY deflation.

This second graph of the same data zooms in on the last 5 years, and indexes to the recent "real" peak in October 2010:


We're still about 1% below that peak.  Since inflation has been running in the 1.5% to 2% range recently, I want to see at least a $.04 per hour increase from last month's reading of $20.50.  That should be enough to overcome any inflation in the last month.  The trend in the last 18 months has been for a "real" increase of about .1% a month.  I would like to see that at least maintained, on track for a new high by midyear next year.

I will spotlight these three points, which will tell us if average Americans are making any progress in employment and wages, when Friday's report comes out.


Saturday, May 31, 2014

Weekly Indicators for May 26 - 30 at XE.com


 - by New Deal democrat

My Weekly Indicators post is up at XE.com.

This was a week that shows why watching the high frequency data is so valuable.  We got the revised Q1 GDP report on Thursday, and since then the Doomers have been pouring out the woodwork with stories of their discoveries that it is supposedly a really big deal.

Naked Capitalism has been especially noteworthy (and not in a good way) for showcasing these Doomer-discoveries-come-latelies.  The Telegraph's Ambrose Evans-Pritchard came out with the news that a heretofore unknown money supply measure  called "Divisia M4" showed that the US economy was DOOOOOOMED.  A particularly incoherent rant showed up at The Automatic Earth, where it was argued (although that word conveys a basic rationality not present in the article) that the second quarter wasn't showing a rebound because -- just look at that bad January and February data!!!!  Ummm, okay. (Hint: when even the Pied Piper of Doom doesn't cite a blog anymore, that's a pretty good sign that showcasing it is conceding the argument in advance).

To the contrary, if you were reading my Weekly Indicator columns, you saw the parade of poor data in real time in  January and February, and have been watching its strong rebound since mid-March. Don't bother looking for the Doomer concessions when revised Q2 GDP data is released in three months. It won't be there.

Friday, May 30, 2014

John Hinderaker: Once Again Proving His Economic Stupidity

I've gotta hand it to John Hinderaker; never has someone with such a horrible record of economic analysis consistently proven his incompetence.  It's almost as though he has a pathological need to publicly demonstrate on a regular basis that he has no clue how to perform economic analysis. 

Now he's talking about the labor force participation rate, claiming,

Apologists for the Obama administration sometimes argue that the nation’s declining rate of labor force participation is largely a function of baby boomers retiring from the labor force. Unfortunately, this is not the case

Unfortunately, John, there has been a ton of research on this.  Several Federal Reserve branches have looked at along with a lot of economists. 

Invictus, over that the Big Picture blog, has a really good summary at this link.  That link as a series of links at the bottom that show a lot of the research on the topic.  You'd think Hinderaker would have looked at some of these before he put his foot in this mouth ... again.


First Quarter GDP Contraction A Statistical Blip

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/data-indicates-1q-usd-gdp-contraction-statistical-blip

The state of the housing market, April 2014


 - by New Deal democrat

As most readers know Bill McBride a/k/a Calculated Risk and I made a charitable bet about the direction of housing in 2014.

In his forecast for 2014 residential investment, CR said, "I expect growth for new home sales and housing starts in the 20% range in 2014 compared to 2013."  By contrast, half a year ago, in a post at XE.com, I said that "If the typical past pattern is followed, we will shortly see permits running 100,000 less than one year previously."

Courtesy of a horrible comparison number with April 2013, YoY housing starts were up over 20% in April 2014, and so I have made a charitable contribution to the scholarship established in the name of CR's late co-blogger, Tanta.

This morning the final monthly report on housing for April, pending home sales, was reported by the NAR.  The index was +0.4% m/m and remains down -9.2% YoY:


(h/t RTT News)

So, with the first four months of 2014 in the books, here is what the housing market looks like.

First, here is a graph of the change, in thousands, YoY of starts (blue), permits (red), new home sales (green), and existing home sales (orange) (note that the St. Louis FRED does not track pending home sales):


Next, here is the YoY% change in the same four statistics:


Both of these graphs show the clear deceleration in the housing market through 2013 and into 2014, with a definite surge in starts (making up for their poor showing vis-a-vis permits in the first few months of 2014).  Whether that was a one-month phenomenon or the beginning of a positive reversal is very much open to question.

More specifically, through April 2014:
  • Permits are down -0.8% from their October 2013 high
  • Starts are down -3% from their December 2013 high
  • New home sales are down -6% from their June 2013 high
  • Existing home sales are down -14% from their July 2013 high
  • Pending home sales are down  -13% from their June 2013 high
Note that there have been extensive revisions to the 2013 data this month, resulting in several altered comparison high months.

But as I have written in the last several weeks, it is only multi-unit (apartment) construction that is carrying the recovery in housing this year. Single family home starts and sales have completely stalled.  Here is a graph of single family permits (blue) and starts (green) compared with 5 unit or higher permits (red) and starts (orange), all normed to 100 as of September 2012:


It is easy to see that it is multiunit construction, especially beginning in the second half of 2013, that is entirely responsible for any continuing increase in residential construction. Single family home construction and sales have gone nowhere since the beginning of 2013.

With mortgage rates at 7 month lows, and with interest rates likely to be lower YoY in several months, there will probably be renewed vigor in the market by the end of this year.  Still, with one-third of 2014 in the books, the odds that the housing market as a whole will be up as much as 20% for the year look like slim and none.  Due to the demographic tailwind of the Millennial (a/k/a "echo boom") generation, and the boom in apartment construction, it also looks unlikely that permits will fall -100,000 as I originally forecast.

Thursday, May 29, 2014

Sometimes it's just too easy . . .


 - by New Deal democrat

I'd say that catching out the Pied Piper of Doom in inconsistency and hypocrisy is like shooting fish in a barrel.  But at least sometimes, that would be unfair to the fish.

The Pied Piper of Doom, March 10, 2014, reacting to the first revised GDP estimate for the 4th quarter of 2013, at +2.4%:
touting Gross Domestic Product numbers are meaningless, and little more than a talking point for the one percent (it is a Wall Street meme, given greater truths) to obfuscate what's really happening in our economy.
The Pied Piper of Doom, May 28, 2014, reacting to the first revised GDP estimate for the 1st quarter of 2014, at -1.0%:
The fact that the economy shrunk 1% in Q1 is a rather MAJOR piece of economic data.
Yeah, I know, we've all read the weeping and gnashing of teeth and rending of garments today about the GDP report. ... Oh, wait, no we haven't.

First quarter corporate profits post small decline


 - by New Deal democrat

This post is up over at XE.com.

Corporate profits, adjusted for unit labor costs, are significant as a long leading indicator for the economy as a whole.

Wednesday, May 28, 2014

Why Real Median Housiehold Income is the most misused statistic in the econoblogosphere

- by New Deal democrat

In virtually any discussion in the econoblogophere about the well-being of the middle and working class, you are bound to see reference to "real median household income" as proof that the average family is much worse off now than they were at the outset of the Millennium.  Everyone seems to know that real median household income peaked in 1999, never surpassed that figure during the Bush years, took it on the chin during the Great Recession, and has barely budged since. So wages have plummeted.

The problem is, what everyone seems to know is wrong.

Real median household income is compiled by the Census Bureau for all households headed by a person age 16 or older. NOT just wage/salary earners.  Households consisting of two retirees are included.  Households headed by somebody in college are included.  Households headed by one or two unemployed person are included.

So, real median household income does not tell you what is happening with salaries and wages.  It is in no way "proof" that real wages and salaries have been declining.  In fact, real wages and salaries have been essentially stagnant since the turn of the Millenium.  We know that because that's what the BLS quarterly report on median weekly earnings shows.

While the Census Bureau reports median household income only once a year, the data is collected each month by the Census Bureau as part of its Household Survey (one of two surveys included in the monthly jobs report). Sentier Reseach uses this to create a monthly update on median household income, which blogger Doug Short uses to update graphically.  At my request, Doug  (who creates some of the best economic graphs on the internet, and if you aren't  already, you should start reading him) put together two graphs comparing real usual weekly earnings with real median household income, and also to the employment to population ratio.

Here is the resulting graph, dating from the onset of the Great Recession at the end of 2007:


You can see the stark divergence between wages and household income at the end of 2008.  The huge increase in unemployment depressed median household income (and the E/P ratio), while those who kept their jobs actually saw their real wages increase, as gas prices declined from a high of $4.25 to $1.50 a gallon.  As a small bout of inflation rippled through the economy in 2010-12, due to gas prices returning to near $4/gallon, real median wages declined somewhat.  As the YoY comparisons of gas prices have since largely turned negative, real median wages have shown a slight improvement.

Now here is the same comparison, taken back to 2000:


This graph confirms that real median wages have largely been stagnant since 2000.  Further, note that the two time periods of the most divergence between real median household income and the E/P ratio, 2002-05 and 2009, the the two times when there were upward spikes in real median weekly earnings.

In summary, real median household income has been declining because of increased unemployment, and because of Boomers retiring in droves. (The first Boomers hit age 62 in 2012.  They have already caused an increase of 4.4 million in the total population age 65 and above to 43.9 million, and an increase as a percentage of the population over 16 over over 1% to 17.9%.  Retirement typically causes a decline of about 50% in the total income of households.)  Because of that, real median household income largely mirrors the employment to population ratio.

To reiterate, real median household income is the most misused statistic in the econoblogosphere.  Whenever you see a citation to it, you should examine the post carefully to see if the piece is using it appropriately to discuss income broadly including non-wage earning households, or is mis-citing it as evidence of a big decline in wages.


Oil At Top of Triangle Consolidation Pattern


Tuesday, May 27, 2014

This does not look like a market on the edge of a Crash

by New Deal democrat
Barron's ratio of insider to selling last 52 weeks:

S&P 500 last 52 weeks:

Hmmmm, insiders vs. Zero Hedge. I wonder which have the better record?

Since the Beginning of the Year, Bonds Have Outperformed


Above is a chart that compares the SPYs, UUP, IEF and DBC.  Since the beginning of the year, the IEF (7-10 year treasury) has clearly outperformed.

Monday, May 26, 2014

The world will little note, nor long remember what we say here, but it can never forget what they did here.


  - by New Deal democrat


Gettysburg National Cemetery


Antietam National Cemetery


Arlington National Cemetery

"We cannot dedicate - we cannot consecrate - we cannot hallow - this ground.  The brave men, living and dead, who struggled here, have consecrated it, far above our poor power to add or detract."  - Abraham Lincoln

Sunday, May 25, 2014

International Week In Review: Slow But Steady Growth Continues Edition

This is up over at XE.com

http://community.xe.com/forum/xe-market-analysis/international-week-review-slow-steady-growth-continues-edition

Saturday, May 24, 2014

Weekly Indicators for May 19 - 23 at XE.com


 - by New Deal democrat

My Weekly Indicator column is up at XE.com.  We know enough now to conclude that the economy will continue to expand at least through the end of this year.

Friday, May 23, 2014

The Failure of Austerity: the UK

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/failure-austerity-uk

Thursday, May 22, 2014

Housing: so what does it all mean?


 - by New Deal democrat

I have some concluding comments up at XE.com about the direction and the importance of the housing market.

What happens to single family home construction and ownership will be largely determined by interest rates.  What happens to apartment construction, in particular, is much more dependent on demographics.  If the Millennials follow the pattern of the Boomers nearly 50 years ago, apartment construction could nearly triple even from its current level over the next 5-8 years.

Wednesday, May 21, 2014

The demographic tailwind of the Millenial generation


 - by New Deal democrat

In the final installment of my more detailed look at the housing market at XE.com,  I discuss how the entry of the Echo Boom generation, a/k/a the Millenials, is  creating a demographic tailwind that is likely to continue for a long time.

Tuesday, May 20, 2014

The apartment boom


 - by New Deal democrat

Yesterday I wrote that the recovery in building of single family homes has been completely halted by higher interest rates and higher prices.

In contrast, in today's second installment, up at XE.com, I show how multi-unit dwelling construction has completely recovered and last month was close to its highest levels in 25 years.

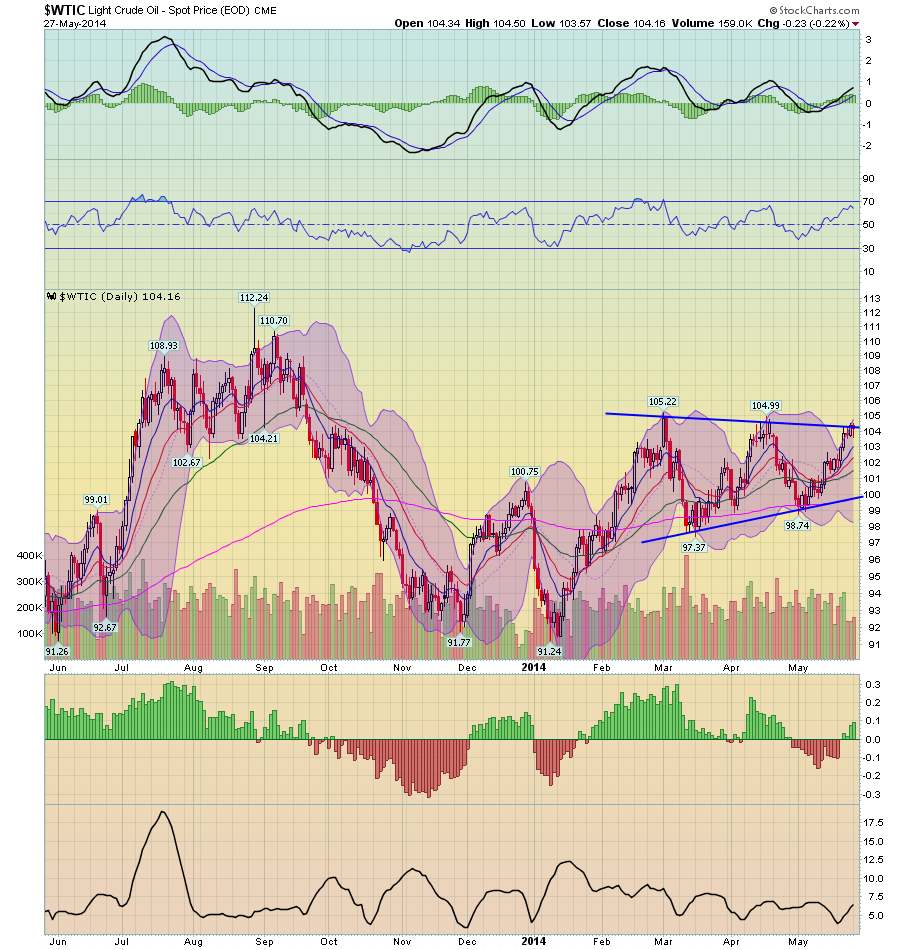
Oil Prices Are Consolidating


One of the things that has been interesting about this expansion is the lack of impact we've seen from oil prices.  As professor Jim Hamilton has pointed out, oil price shocks have been a primary cause of most post WWII recessions, so, on the whole this is good news.

Above is a chart of oil prices.  Currently they're consolidating in a triangle pattern between the upper 90's and ~105, using the 200 day EMA as technical support

Monday, May 19, 2014

Increasing interest rates and prices have brought the recovery in single family homes to a complete halt


 - by New Deal democrat

I'm taking a deeper, segmented, look at housing. The first installment, dealing with single family houses, is up at XE.com.

Chinese Weekly Chart Is Not Encouraging


Since the beginning of 2013, the Chinese stock market has been consolidating in a triangle formation.  Just as importantly, the 200 week EMA has been consistently moving lower and momentum is weak and negative.  This is not a chart that has any potential bullish implications.

Saturday, May 17, 2014

International Week in Review: Japanese and EU Slowdown in the Works Edition

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/international-week-review-japanese-and-eu-slowdown-works-edition

Are skyrocketing rents and increased food prices behind the decrease in tax withholding?


  - by New Deal democrat

Earlier today in my Weekly Indicator column I highlighted the anomaly of an outright YoY decline in tax withholding.

The Treasury Department's daily tax withholding report  isn't an estimate like nonfarm payrolls or GDP that is subject to substantial revision. It is bedrock hard data.  And just by virtue of nominal average wage increases YoY, it should be up about 2%.  Instead, since April 1, the daily reports have been consistently negative, and now the 20 day average has turned negative as well.

Almost all of the other incoming weekly and monthly economic reports have been quite positive. For example, consumer spending has really picked up this spring.  More particularly, April nonfarm payroll growth was nearly +300,000.  So what's going on?

It could be that the jobs numbers for the last couple of months are going to be revised downward. Big time.  But we've also just hit a post-recession low in layoffs, via initial jobless claims.  Has hiring really screeched to a stop?

Here is my preliminary guess, and it is only a guess, but this story fits the data.

One way to get a decrease in withholding taxes in the face of increasing jobs, is if workers decide to take more deductions.   In essence workers would be trading less of a refund next year for more cash in the pocket now.

And there are several excellent reasons why they might have done so in the last few months.

First of all, due to the government shutdown last October, the IRS had to delay processing of tax refunds.  It started 10 days later than planned, on January 31.  I suspect the delays continued.  Most significantly,  Walmart reported its 1st quarter profits were lower than expected:
The big discount retailer said its results were hurt by bad weather and a delay in tax refunds caused by last fall's government shutdown.
Not only were tax refunds delayed, but the prices for two basic need - food and shelter - increased significantly in the first quarter, especially for renters.  Food prices are up 2.7% so far this year.

More importantly than that, with apartment vacancy rates just above 12 year lows in the first quarter, rents have skyrocketed.  The first quarter's median asking rent nationwide is $766, up 2.7% in that quarter alone, and up 6.7% YoY.  (I wrote a few weeks ago that rent wasn't in a bubble, based on statistics through the end of 2013, and while I still wouldn't call it a bubble, this first quarter jump has got to be putting a real squeeze on working class renters).

Faced with a big increase in rent, and significant increases in food prices, together with a delay in receiving tax refunds, have a significant number of working class families decided to trade next year's tax refund for the ability to pay for food and rent now, but decreasing the amount of money withheld in their paychecks?

It's only a guess, but it fits the data.

Weekly Indicators for May 12 - 16 at XE.com


 - by New Deal democrat

WTF is going on with tax withholding?!?

Friday, May 16, 2014

Single family vs. multi unit housing permits and starts: it's still not different this time


 - by New Deal democrat

As I pointed out in my earlier post today, housing starts are considerably more volatile than permits.  In fact, they're about twice a volatile:  a 200,000 change in starts is just as likely as a 100,000 change in permits.  This morning, reported housing starts were up +224,000 YoY.  But the biggest change in permits in the last 6 months has been +107,000 YoY in November.

As I wrote last year, 16 of 21 times since the end of World War 2, an increase in interest rates of 1% or more has led to a decrease of -100,000 in housing permits (a 17th time, in 2001, the change was -62,000).  In January, I examined the exceptions to the rule, finding that they typically involved scenarios where the saying, "Buy now or be forever priced out" was a powerful scenario.

A lot of the commentary today has focused on how much of the increase in housing starts in April was multifamily (5+ units) vs. single family homes.  In view of that, I thought I'd go back and examine how single family vs. multifamily permits and starts played out both in general and during those 4 "exceptions to the rule" periods over the last 50+ rules.

And it turns out this time really isn't different.   On all 4 occasions where an increase in interest rates did not lead to a significant decrease in overall housing starts, the effect on single family vs. multifamily units was - unlike most periods - profoundly different.

Below are 4 graphs, showing housing permits for single family homes (blue), multifamily units (green) vs. interest rates measured by 10 year treasuries (inverted so that an increase shows as a negative, red).  The first three are measured as YoY% changes in 20 year or so increments.  The 4th is  measured in changes of 100,000 units, focused on the last 10 years:


If you click on the first three graphs and examine them, you'll find out that typically single and multifamily permits move in unison.  With the exception of 1994, all of the other exceptions -- 1962, 1967-78, 1978, and 2004-05 -- coincided with significant increases in interest rates.

In other words, the first sign of stress in the housing market due to rising interest rates has generally been a shift from single family to multifamily building.  And that is what has happened in the last year as well, as single family permits have actually turned negative YoY in the last few months.  It is the multifamily segment (as you recall, rental vacancies are at all time lows on the order of 3%, and rents have outpacing inflation since the beginning of 2013), which is holding up the market.

In the prior "exceptions to the rule," eventually housing permits and starts followed interest rates. I still think the best rule of thumb is that "it's not different this time."

Congratulations to Bill McBride


 - by New Deal democrat

As I suspected, housing starts rebounded strongly from their last two months and blew past the 1,023,000 number that would give Bill McBride the win on our friendly bet.  Starts are the more volatile of the two series, and tend to follow permits by a month or two.

This is also more evidence that this past winter was a real factor in holding down the economy, and there has been a "Spring spring" in almost all of the data.

So, Congratulations to Bill McBride, and it will be a pleasure to make a contribution to the late Tanta's memorial fund.

The interesting thing is, the trend on the most leading indicator of the two - housing permits - continues its deceleration, even if it has not turned negative.  I'll post the graph showing this below as soon as the St. Louis FRED updates their data.

UPDATE:  The regional breakdowns make it clear that the huge increase in starts was due mainly to the severe winter in the Northeast and Midwest holding back demand until April.

Here's the m/m and YoY breakdown in starts by region:

Northeast: 139 vs. 108 m/m (+28.7%);  vs. 78 YoY (+78.2%)
Midwest: 216 vs. 152 m/m (+42.1%);  vs. 154 YoY (+40.3%)
South: 486 vs. 479 m/m (+1.5%); vs. 411 YoY (+18.2%)
West: 231 vs. 208 m/m (+11.1%); vs. 205 YoY (+12.7%)

If, as I did yesterday with real retail sales, we average January through April and compare the total YoY, we get an average of 922,000 starts in 2013 vs. 961,000 starts in 2014, for a gain of +4.2%.

UPDATE #2:  As promised, here is a graph of the YoY% change in permits and starts since 2011:


Notice that the decelerating trend in permits is still very much intact.  Note also this month included revisions to the 2013 numbers, indicating that permits were actually negative YoY two months ago.

Next, here is a graph of the percentage change m/m between permits (blue) and starts (red) (squared so that the sign in each is positive.  It does not affect their relative volatility at all):


Note that starts are much more volatile than permits.

So, there is still the issue of whether this is a one-off due to the spring rebound from the unusually severe winter, or whether the decelerating trend (as evidenced YoY in permits) will continue.

Thursday, May 15, 2014

A true mixed reading on another long leading indicator


 - by New Deal democrat

I have a new post up at XE.com discussing real retail sales per capita, which typically peak about one year or more before the economic cycle rolls over.

The spring spring may have given us a new peak, but the longer term decelerating trend is intact.

Will Bill McBride win our housing bet tomorrow?


 - by New Deal democrat

Tomorrow April's housing permits and starts will be reported, and there's a decent chance that Bill McBride will win our bet on housing.

Not because housing is suddenly on a roll, but because April 2013 was one of the two worst housing starts numbers of last year, at 852,000 (only June was worse at 835,000).  Housing starts are also more volatile than permits, and tend to follow permits by a month or two.

Since permits have had two decent months in February and March, starts are likely to follow, aided by the spring springback from winter's poor data.  Anyway, the high for starts since the  housing bust was 1,024,000 back in December.  There's a decent chance starts equal or beat that in April, and if so Bill will win our bet (a 20% YoY increase would be 1,023,000).

As to permits, April 2013 saw 1,005,000 issued.  The estimates suggest that tomorrow we will see the first YoY decline in permits in 3 years.

We'll see then.

Wednesday, May 14, 2014

Japanese ETF Breaks Through Resistance


Since the beginning of February, the Japanese ETF has been trading in a downward sloping triangle pattern as traders have begun to slightly discount the long term effects of "Abenomics."  However, yesterday prices broke through upside resistance, indicating there may be a change in trader's perceptions of the Japanese economic situation.  Also note the increased CMF and rising MACD accompanying the move. 

On the downside, prices are still below the 200 day EMA as are the shorter EMAs. 

Tuesday, May 13, 2014

Why Austerity Doesn't Work

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/why-austerity-does-not-work

Indian Market Hits Yearly High on Election News


News that Modi will win the Indian election has rallied Indian shares to yearly highs.  However, there are questions as to whether the voters' expectations for his term are too high.