Thursday, May 8, 2014

In which I am a semi-wet blanket about that 401(k) story


 - by New Deal democrat

By now you've probably all read at a bunch of blogs about how IRS data shows that Americans increased their borrowing from or cashed out their 401(k)'s in recent years, all of which feature these graphs:


A truthful headline for these graphs would be "During and right after the Great Recession, Americans increasingly tapped their 401(k)'s."  While the original Bloomberg piece was fairly careful, some of the later iterations have sloppily or ambiguously used the present tense (see, e.g., 
Barry Ritholtz, “Tapping your 401(k)?”).

Which is simply not correct.  This data is in no way contemporaneous data. The most recent reading is THREE YEARS OLD. And the most recent, three-year-old, data, shows a significant improvement from the four-year- old data.

It’s also worth pointing out that the series isn’t population adjusted, which is a non-trvial difference, and the 38% increase in the number of IRS returns incurring the penatly is faiirly consistent to the ~60% increase in the unemployment rate from 6% to 10%.

What the graphs show is that those borrowing from or cashing out their 401(k)'s went up as unemployment went up, peaked about when unemployment peaked, and came down in 2011 as unemployment started to recede. We have absolutely no idea what has happened in the last 3 years, and furthermore it is a reasonable bet that 401(k)’s were raided less and less as the unemployment rate continued to go down. 

All of this seems non-contoversial to me.    Which leads me to my next question:  would the alarm be the same if we still had a well functioning pension system for most people? 401(k)’s are basically “rainy day” funds where the target rainy day is retirement. Obviously we should expect that people who have emergencies are going to tap their rainy day funds. Is that by itself really a problem? – Or only because 401(k)’s have largely replaced rather than supplemented traditional pensions?

In my opinion the alarm shouldn’t be that people tapped into their 401(k)’s as the unemployment situation worsened. The alarm should be that 401(k)’s are a dismal (and to some extent intentional) failure as a replacement for the traditional pension. No company should be allowed to offer a 401(k) that does not include a substantial company match, or is in lieu of or bigger than its traditional or defined contribution pension, or is not as generous percentage-wise as its stock option or other incentive program for senior executives.

That, it seems to me, is the disgrace. Not that people cashed out or borrowed from 401(k)’s more in 2008-11 than they did in 2002-06.


The Failure of Austerity: Spain

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/failure-austerity-spain

Wednesday, May 7, 2014

Real median wages for occupational employment decline -0.6% in 2013*


 - by New Deal democrat

Most of the measures of real wages that I have tracked bottomed either in the beginning of 2013 or in late 2012, so this one comes as a bit of nasty surprise.  With an asterisk.

Every year in May, the BLS, in cooperation with state workforce bureaus, compiles a list of median wages for hundreds of occupations.  In the last few years, these have shown that jobs in the 4th quintile, i.e., the lower middle class or working poor, have taken the biggest hit.

Like other measures of real wages, they reached a peak at the end of the last recession when gas prices were under $1.50 a gallon and thus mild nominal increase in wages were paired with about a -1% deflation in overall prices.

With gas prices stabilizing in the last 3 years, I certainly expected even small nominal wage increases to lead to an increase in this measure of wages as well.

Not so.  As of May 2013, the median wage in the US was $16.87.  In 2012 it had been $16.71, but adjusting for inflation, that becomes $16.98, which means that real wages were down -0.6%.

Now here is why there is an asterisk.  The result is likely due to the way the BLS conducts the survey, as explained in this technical note:  the 2013 results are due to results obtained over 6 surveys from November 2010 through May 2013. That means the survey period coincided almost perfectly with the trough in other wage measures.

If we treat the survey as an average of wages from late 2010 through early 2013, then the continued decline makes sense.  Unfortunately we won't have a comparison until one year from now.


Unit labor costs up YoY, gain in first quarter


 - by New Deal democrat

I have a new post up at XE.com reporting on unit labor costs, which were just reported for the first quarter.

Last year, you may remember, I teed off on reporter David Cay Johnston, who did some sloppy Doomish reporting on 1Q 2013's number.

Most measures of real median wages increased in the first quarter of this year.  I'll put up a comprehensive post updating all of the data series at some point in the next week.

Tuesday, May 6, 2014

A note for Tuesday: 3 reasons I will vote democrat in 2016


 - by New Deal democrat

(Slow day, have items in draft but not completed, so ...)

  1. Antonin Scalia (78 years old)
  2. Anthony Kennedy (77 years old)
  3. Ruth Bader Ginsburg (81 years old)
None of the above three are likely to alive or healthy enough to serve on the Supreme Court by 2020.  I have previously pointed out that it typically takes 3 consecutive Presidential terms of same party control to reshape the Court.

Who do you want to name their replacements?

There is no single item, no matter how important, on any economic or social agenda, that will have nearly the impact as the answer to that one question.

The Failure of Austerity: Portugal

This is up over at XE.com


Monday, May 5, 2014

Historical recoveries in manufacturing vs. retail jobs


- by New Deal democrat

This is the second installment in my look at how low vs. high paying jobs have recovered in past recessions. My hypothesis is that the typical pattern in recoveries is that low wage jobs recover faster than high wage jobs.  Thus, earlier in a recovery it will be the case that the economy seems to be producing only low wage jobs.  Since most post-World War 2 recoveries restored all jobs relatively quickly, the pattern was not long-lasting.  This recovery, however, is from a much deeper hole and is taking much longer, so the period in which it is producing mainly low wage jobs is taking longer and has been profoundly noticed.   In this installment I am comparing high-paying manufacturing jobs with low paying retail jobs.

This comparison is a special challenge, since manufacturing employment reached its peak in 1979,  and has trended downward ever since.  So, while I can look at recessions through 1974 as I did with construction jobs, measuring the month at which the respective category of jobs exceeded its prior peak of employment, it is impossible to do so for recessions beginning in 1979.

Since there has been an overall declining trend in manufacturing jobs since, what I can do is compare the first derivative of manufacturing job growth/decline against the first derivative of retail job growth/decline.  In other words, at what point after the recession did each category have its highest rate of growth. The first derivative information is represented in italics in the chart below:

Recession
year
manufacturingretaillag in
months
19488/19506/19502
1953 3/19652/1955121
1957 9/19641/195968
196010/196311/196123
1970 11/1973 9/197038
1974 5/19788/197533
19797/19817/19810
1981 4/198411/1984-7
1990 4/19941/1995-9
200110/20048/2005-10
2008 3/201112/2013-33

What we find is that, for every single job recovery since World War 2, up until 1980, retail jobs regained their prior peak before manufacturing jobs, in one case by over a decade! All but one such lag were at least by almost 2 years.

In the later recessions as to which we must measure by the first derivative of YoY growth, in all cases but one, including the current expansion, the rate of manufacturing job growth peaked in advance of that of the rate of retail job growth.  As the below graph shows, in 5 of the 7 pre-1980 recessions, the YoY increase in manufacturing jobs also peaked first:


In summary, in manufacturing as with construction, this economic expansion is no different from most other post- World War 2 expansions. And in all cases where we can make a direct absolute measure, low paying retail jobs fully recovered before manufacturing jobs did so.

The REAL "real unemployment rate" for April 2014


 - by New Deal democrat

This morning the New York Times ran an article describing how poor wage growth is the best measure of how fragile this economic expansion has been for average Americans.  I agree.  Unfortunately in that article, unsourced, they reported that
... [I]n Friday’s jobs report..., the unemployment rate fell entirely because people stopped looking for work, not because they found jobs.
What a load of crap. The BLS itself said that the decline in labor force participation in April was mainly because fewer than normal people entered it, rather than people dropping out.  But this poor reporting is typical. The EPI wrote that its "missing workers" number (based on estimates from a research paper published 7 years ago) reached a new high in April, despite the fact that the economy has added over 225,000 jobs per month for the last three months -- well above any estimate of what is needed to absorb population growth.  Meanwhile the popular blog Naked Capitalism calculates a rate of 12%+ for unemployment with an analysis that begins with an unspoken "assume there was no Baby Boom" and completely ignores the inevitable downward pressure Boomer retirements must place on the labor force participation rate.

So herewith, let me update the "real real unemployment rate.

In order to be counted among the unemployed for purposes of the monthly jobs survey, a person must have actively looked for a job during the reference period.  But what about people who are so discouraged that they have completely stopped looking for work and have simply dropped out of the labor force?

The monthly household jobs survey measures exactly this in a statistic called "not in labor force, want a job now."  Here's what that metric shows for the last 20 years:

The number of discouraged workers rose by nearly 2,000,000 in the wake of the great recession, but has declined by about 1/3 of that number in the last two years.

In order to find out what the "real" unemployment rate is, including such discouraged workers, we simply add the number of people shown above to both the numerator (unemployed) and denominator (civilian labor force, which excludes those adults not interested in jobs, like retirees) of the statistics used for the unemployment rate.  Here's what that shows:


The usually reported unemployment rate (U3, in red) is currently 6.3%.  The "real" unemployment rate including those who want a job but haven't looked (blue) is 9.8%.

While this is by no means good, it is important to compare apples to apples.  Note that the current rate is equivalent to that of late 1994, and even at the height of the late 1990's tech boom, the best economy the US has seen since the 1960's, this rate was 6.7%.

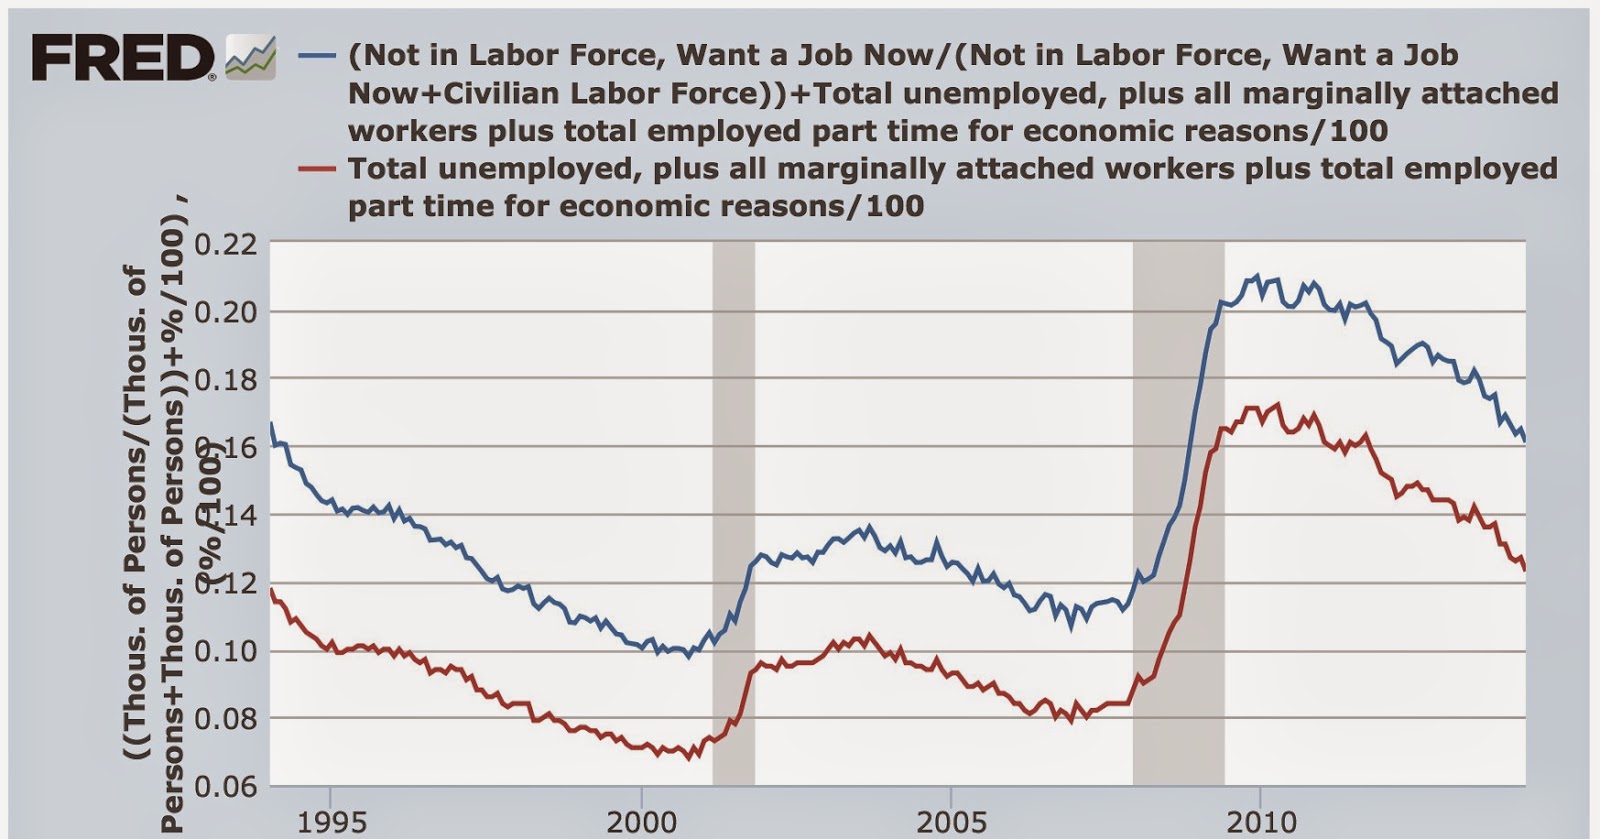
We can perform a similar calculation to get the "real underemployment rate," i.e., which adds those who are working part time for economic reasons or are otherwise marginally attached to the workforce:

The "real" underemployment rate is 16.1% (blue) vs. 12.3% (red).  Again, note that even in the 1990's tech boom, this rate never got below 9.9%.

The calculation above is in accord with recent papers by the Atlanta Fed , researchers at the IMF, and Shigeru Fujita of the Philadelphia Fed that, while most of the increase in the "missing workers" initially was due to discouragement, in the several years there has been a relative increase in the number of retiring Boomers, thus reducing the number of those who are "not in the labor force, [but] want a job now."


Sunday, May 4, 2014

John Hinderaker: Still Economically Clueless

To quote Hawkeye Pierce from MASH, "there's so little that Hinderaker knows about economics, it's difficult to keep up with what he doesn't know."  Really, it's amazing to me that a person who supposedly has an impressive resume can be so wrong on economics on such a regular basis. 

In his latest attempt to prove economic relevance, Hinderaker compares the current expansion to the Reagan's expansion.  As usual, he fails.  Completely.

As people who regularly read this blog know, there is a big fundamental difference that makes this comparison moot.  Reagan's recession was caused by the Federal Reserve increasing interest rates to slow inflation.  As a result, we see the following chart of the effective federal funds rate:


And, we have the following chart of the discount rate:


Because the Fed was the primary cause of the slowdown (fulfilling its job of "taking away the punch bowl") the recovery that started afterward could gain traction quickly.

In contrast, the latest expansion is a "credit default recovery," a vastly different economic event.  Here, the economy experiences a massive asset bubble caused by the expansion of credit.  But as the asset bubble bursts, those who are in debt begin selling assets to cover their loans.  Eventually, the pace of selling leads to two things: a collapsing bubble and a large number of people who owe more than they own.  This means thy greatly slowdown the pace of their purchases, slowing overall economic activity.  We know this to be the current case from looking at monetary velocity numbers:


You can read about this concept in Irving Fisher's essay, The Debt Deflation Theory of Great Depressions.

At this point, I don't expect Hinderaker to actually say anything insightful about economics; he's been consistently wrong on the topic for the better part of 10 years.  But, people actually read his work and (terrifyingly enough) take him seriously.  And that is dangerous, especially when his analysis is so fundamentally flawed. 


Saturday, May 3, 2014

Weekly Indicators for April 28 - May 2 at XE.com


 - by New Deal democrat

There was a real schizophrenic read on Gallup consumer spending vs. the ICSC and Johnson Redbook this past week.

International Week in Review: The US' Weak Growth Head Fake Edition

This is over at XE.com

http://community.xe.com/forum/xe-market-analysis/international-week-review-us-weak-growth-head-fake-edition

Friday, May 2, 2014

Is it really different this time? historical recoveries for low vs. high paid jobs


 - by New Deal democrat

In the last week there has been another spate of articles on the order of The low wage job explosion from CNN Money.  On Monday Prof. Mark Thoma picked up the issue.

There is no doubt that what the articles are saying about the post-recession jobs situation is correct.  Unfortunately, none of these articles compare this recovery with prior recoveries.  The question is, is this jobs recovery producing a different mix of jobs from earlier recoveries, or is it producing a similar mix, but taking a longer time to fully recover?  Put another way, is this jobs recovery different in kind, or just different in intensity compared with prior recoveries?

This is an issue I spent some time researching a while ago, but never wrote about.  Since I left a comment at Thoma's site earlier this week and got a plaudit from the well-known Anne in response, I thought I would repost the research I've done so far here.

Here's the hypothesis I am testing:  the typical pattern in recoveries is that low wage jobs recover faster than high wage jobs.  Thus, earlier in a recovery it will be the case that the economy seems to be producing only low wage jobs.  Since most post-World War 2 recoveries restored all jobs relatively quickly, the pattern was not long-lasting.  This recovery, however, is from a much deeper hole and is taking much longer, so the period in which it is producing mainly low wage jobs is taking longer and has been profoundly noticed.

If my hypothesis is correct, then as the unemployment rate drops, a bigger proportion of higher wage jobs ought to be created.  Dean Baker produced a graph earlier this week comparing the state by state unemployment rate with low wage food service jobs, that lends support to this proposition:


Notice that, the lower the unemployment rate, the lower the relative rate of low wage food service jobs.

So I examined two types of jobs: I compared recoveries in construction jobs (relatively high paying) with retail jobs (low paying), measuring how long it took for each to recover fully from their pre-recession highs for each recession since World War 2. Here's a chart of what I found:

recession
Year
constructionretaillag in
months
19485/19506/1950-1
1953 11/19542/1955-3
1957 11/19641/19592
19606/196311/196119
1970 4/1971 9/19707
1974 4/19788/197544
197912/19842/198162
1981 12/19841/198323
1990 3/19962/199425
20013/200411/2006-7
2008 n/an/an/a

With the exception of the recovery from the 2001 recession, in every recovery beginning with 1957, retail jobs fully recovered before construction jobs.  This supports my hypothesis.

In essence, I am going to extend the research by the National Employment Law Project, shown in the below graph, which compared only job recoveries from 2001 and 2008, to prior job recoveries.


In addition to retail, note that the two biggest categories of low paying jobs are food service and drinking places, and administrative and waste services.  Data for these two categories of jobs only goes back to the 1990's, so they are of very limited value for the comparisons I need to make. For the record, food service and drinking place jobs returned to their 1990's peak in December 2003 (3 months before construction jobs); waste services returned to their 1990's peak in September 2005 (18 months after construction). Food service has not regained its pre-Great Recession peak. Waste services exceeded its pre-Great Recession peak in November 2013.

In addition to government, I need to test the hypothesis against some of the other high paying private sector job categories besides construction. I imagine this will take a few weeks.  I'll post results as I get them, and we'll see if the hypothesis pans out.

Prime working age employment population ratio improves in 2014


 - by New Deal democrat

As I pointed out below, that the employment population ratio has increased while the percentage of the population in the labor force has decreased seems like a good thing, suggesting that the reason for the decrease is moving more and more towards Boomer retirements.  Part of that may be that Boomers who want to retire can now enroll under the ACA, and don't have to wait for their Medicare eligibility.

I thought I'd look at a metric Paul Krugman has examined from time to time, in order to avoid the confoundment of the data by Boomer retirements; namely, the employment to population ratio of 25 to 54 year olds.  And I got a surprise:


Since last October, the employment to population ratio in this age group has increased from 75.5% to 76.5% (in March, it was actually higher at 76.7%).

It is now higher than it was at the beginning of 1985.  It has made up about 1/3 of its Great Recession decline.

This is good news.

April jobs report: a blowout (almost)


- by New Deal democrat

In April 288,000 jobs were added to the US economy.  The unemployment rate fell from 6.7% to 6.3%, a new post-recession low.  January and February were revised upward by 36,000, with both now over the 200,000 threshhold as well.


As usual, first, let's look at the more leading numbers in the report which tell us about where the economy is likely to be a few months from now. These were mixed but with a tilt towards positive.

  • the average manufacturing workweek fell from 41.1 hours to 40.8 .This is one of the 10 components of the LEI, and will contribute significantly towards a negattive number.

  • construction jobs increased by 32.000. YoY 189,000 construction jobs have been added.

  • manufacturing jobs  rose by 12,000.

  • temporary jobs - a leading indicator for jobs overall - increased by 24,000.

  • the number of people unemployed for 5 weeks or less - a better leading indicator than initial jobless claims - declined by 14,000 to 2,447,000, compared with December's 2,255,000 low.

Now here are some of the other important coincident indicators filling out our view of where we are now:

  • The average workweek for all nonsupervisory workers was unchanged at 33.7 hours.

  • Overtime hours were also unchanged at 3.5 hours.

  • the index of aggregate hours worked in the economy rose by 0.3 from 108.1.  This is a new record.

  • The broad U-6 unemployment rate, that includes discouraged workers decreased from 12.7% to 12.3%, also a post-recession low.

  • The workforce declined by 806,000. Part time jobs decreased by 276,000.
Other news included:
  • the alternate jobs number contained in the more volatile household survey decreased by 73,000 jobs.  The household survey jobs numbers had been lagging the establishment survey numbers, but as expected this difference has now been entirely made up, with the household survey showing a 1,993,000 increase in jobs YoY.

  • Government jobs increased by -15,000.

  • February was revised upward from 197,000 to 222,000.  March was also revised upward by 11,000 to 203,000  Upward revisions happen in expansions, and after a weak spot in late 2013, these revisions in the last several months have all been positive.

  • average hourly earnings were unchanged at $24.31. The YoY change is +1.9%.  As a result, YoY average real wages probably fell slightly in April, given the expected slight rise in consumer prices due to the weakening of the Oil choke collar.

  • the employment to population ratio was unchanged at 58.9%, and has risen +0.3% YoY. The labor force participation rate declined from 63.2% to 62.8%, and has fallen by 0.6% YoY.  The usual  caveats about discouraged workers and Boomer retirements apply, but the comparison of the two measures, i.e., a greater percentage of the population is employed, but a smaller percentage of the population is in the labor force, looks very much like Boomer retirements are moving to the fore.
  • the number of people who are not in the labor force but want a job now (the best measure of long time discouragement) declined 245,000 and now totals 3,125,000.
This was a blowout report by the standards of the last 7 years.  This would not be seen as a blowout by any standards prior to 2000, however.  With one exception, all of the metrics moved substantially and positively.  We may have sub-6% unemployment, finally, by the end of this year.  The Doomer memes of part-time employment and discouraged workers both took a hit, as it appears that, excepting Boomer retirements, participation is increasing and discouragement is decreasing.

The big decrease in the civilian labor force will probably get lots of attention this month, but no obvious reason for the decline besides monthly noise appears on the surface.

The one big caveat to this report is wages. They are stalling and in real terms are declining again slightly. The YoY comparison, which had been as high as 2.5%, has faded back under 2%.  This is not good, especially over 4 years into a jobs recovery.  What happens to wages the next time there is an economic downturn.  That is the problem that worries me the most.

From Bonddad:

These are my thoughts, in no order of importance:

Let me begin with this curmudgeonly caveat: I really don't like the monthly employment number report.  The US labor market is wide and deep, and has many nooks and crannies.  And those various nuances are still pretty negative: under-utilization is high, confidence is low and utilization is weak.  However, the market loves this number and report, so let's dive into the details.

Wow.  288,000.  That's a great headline number.  Overall growth was far more tilted to the service sector as 220/288 (or about 76%) of the jobs were added in that sector.  Considering the harsh winter weather, that's to be expected.  Manufacturing only added 12,000 jobs, but considering the high degree of automation involved with US manufacturing now, that's really not a bad number.  And construction only added 32,000.  My guess is contractors are still trying to regroup after the winter.  Hopefully we'll see a stronger increase in this number as the weather warms up and housing starts, well, start.

There were some interesting developments in the household survey.  The civilian non-institutional population increased 181,000 but the labor force dropped by 806,000.  That's a really big drop.  On the good side, the number of unemployed decreased by 733,000 but the total number of employed dropped by 73,000.  These rather interesting internals explain the sharp drop in the unemployment rate and participation rate.  These internal numbers are a bit odd; I'd like to see a hard-core statistician explain them. 

Total hours worked and total wages paid were stagnant.  While this is usually a bad thing, I would offer the following explanation: rather than increase hours and pay, maybe employers started to add to payrolls instead?  That's just a thought.

February and March were revised a higher by a combined amount of 36,000.  This tells us the initial weakness from those readings is still intact; but we weren't as weak as we thought initially. 

I agree with NDD that, when judged from the perspective of this expansion, this is a good report.  However, when we broaden that base of comparison, it's not that great. 


Thursday, May 1, 2014

More shallow DOOM about jobs at Daily Kos


 - by New Deal democrat

I haven't had enough time to clean up some draft posts this week, one of which is about the relative strength in this recovery in terms of low wage jobs vs. high wage jobs. Is this recovery unique in that regard, or is it similar to past recoveries?

I figured there would be a Doomer post or two at the usual suspects,and I had hoped to already have the main research done before they weighed in, but I haven't had the time.  So, earlier this week Mark Thoma had a brief piece up, and I had an exchange with commenter Anne on the topic.  I'm just going to repost the comments here for now:
-----------
NDD: Is this recovery actually any different than other post World War 2 recoveries in terms of creating low wage jobs before high wage jobs? I looked at a few post-war recoveries and it looked like the same pattern was followed, but full employment returned quickly so the initial shortfall in higher paying jobs wasn't noticed. Dean Baker seems to be making a similar point in response to the NYT article; namely, it's the shortfall from fulll employment that is responsible for the prevalance of lower paying jobs.
I'm asking the above as a real question, rather than making a statement. If somebody can compare this recovery vs. other post WW2 recoveries in terms of the order of the return of low vs. high paying jobs, I'd be very interested in what they find.

NDD: OK, I've compared construction vs. retail employment as proxies for high and low wage jobs. I used construction since, unlike manufacturing, it can't all be offshored.
Here's what I found. Beginning with the 1957 recession, in every recession except the 2001 recession, retail employment returned to its previous high sooner than construction employment, by as little as 2 months and as much as 62 months! The exception was that after 2001, construction returned to its previous high 7 months ahead of retail.
Needless to say, neither has returned to its pre-Great Recession high, although retail is closer. If these are fair proxies, this supports the idea that the current lag in high paying jobs is a question of intensiy, and is not different in kind from most post WW2 recessions.
Anne:  Having now looked carefully at the data from this perspective, I agree. Again, well done. The problem is evidently general demand, not the structure of demand, which makes sense. 
-------------
I'll have a lot more to say on this issue in the next few weeks or so, because I have a lot of number crunching to do.
For now, the question to Meteor Blades and all of the Doomers at Daily Kos is,
How does the structure of demand (low wage vs. high wage jobs) stack up since 2009 ...
  • vs. 1948?
  • vs. 1954?
  • vs. 1957?
  • vs. 1960?
  • vs. 1970?
  • vs. 1974?
  • vs. 1980?
  • vs. 1982?
  • vs. 1990?
  • vs. 2001?
Has this recovery uniquely produced more low paying jobs? Or, like prior recoveries (as to construction vs. retail jobs at least), is the recovery in low paying jobs simply taking place more quickly than the recovery in high paying jobs?   Put another way, is this recovery different in kind or just different in intensity? Until you can answer that question, you really don't have a clue about whether this recovery is different from any other recovery in terms of how quickly it has produced low paying jobs vs. high paying jobs.

But don't disturb the echo chamber by forcing them to do some actual comparisons.  Spoils all the fun in DOOOOMMM.


March personal spending rebounds from winter doldrums as reflected in yesterday's GDP report


 - by New Deal democrat

I have a new post up at XE.com.

The very positive March personal spending report is consistent with the idea that we are rebounding from the near-recessionary consumer spending of January and February that were reflected in yesterday's flatlining Q1 GDP report.

Wednesday, April 30, 2014

The decline in real private residential spending raises a yellow flag for US economic growth in 2015


 - by New Deal democrat

I discuss this aspect of today's first quarter GDP report in a post over at XE.com.

1Q GDP: Blame the Weather

This is up over at XE.com

1Q GDP: Blame the Weather:

Don't freak out about the poor 1st quarter GDP report (except for one thing)


 - by New Deal democrat

So GDP grew by the smallest amount possible, +0.1% annualized, in the first quarter of 2014.

If you've been reading my "Weekly Indicator" series religiously, you know that all through January and February I was reporting that the economy, as measured by the high frequency weekly data, had hit an air pocket.  It recovered in the latter part of March.

This was one of those rare cases where the weather really was a valid excuse, and that's what the late March and April data have been confirming.

So, yes, this was a bad positive number.  But a bad positive number with a perfectly reasonable explanation, that need not carry forward at all.

With one exception.  And that is the line that reads, "Real residential fixed investment decreased 5.7 percent, compared with a decrease of 7.9 percent" in the fourth quarter of 2013.

According to UCLA Prof. Edward Leamer, a decline in real residential fixed investment as a share of GDP is the first warning sign of a recession about 5 quarters out.  With a decline of two quarters in a row, the outlook for 2015 has become more problematic.

I'll have more up at XE.com later, and I'll update with a link here.

Monday, April 28, 2014

My housing bet with Calculated Risk: March results


 - by New Deal democrat

As most readers know Bill McBride a/k/a Calculated Risk and I have a charitable bet about the direction of housing in 2014.

In his forecast for 2014 residential investment, CR said, "I expect growth for new home sales and housing starts in the 20% range in 2014 compared to 2013."

By contrast, several months ago, in a post at XE.com, I said that "If the typical past pattern is followed, we will shortly see permits running 100,000 less than one year previously."

Here are the terms of our bet:  If starts or sales are up at least 20% YoY in any month in 2014, I will make a $100 donation to the charity of Bill's choice, which he has designated as the Memorial Fund in honor of his late co-blogger, Tanta.    If housing permits or starts are down 100,000 YoY at least once in 2014, he make a $100 donation to the charity of my choice, which is the Alzheimer's Association. 

This morning the final monthly report on housing for March, pending home sales, was reported by the NAR.  The index was up 3.4% m/m (its best showing in 4 months) but remains down 9.7% YoY:


(h/t Mortgage News Daily)

So, with the first three months of 2014 in the books, how do we stand?  Below are two graphs.

First, here is a graph of the change, in thousands, YoY of starts (blue), permits (red), new home sales (green), and existing home sales (orange) (note that the St. Louis FRED does not track pending home sales):


Next, here is the YoY% change in the same four statistics:


Both of these graphs show the clear deceleration in the housing market through 2013 and further into March 2014, to the point where 4 of the 5 monthly reports have turned negative YoY.  The strongest metric is housing permits, which has rebounded over the last two months from a +3.3% YoY reading in January to a +12% YoY reading in March.  Nevertheless, the graphs make clear that except for permits, deceleration has turned into outright YoY decline.

More specifically, through March 2014:

  • Permits are down -4% from their October 2013 high
  • Starts are down -9% from their December 2013 high
  • New home sales are down -16% from their January 2013 high
  • Existing home sales are down -15% from their July 2013 high
  • Pending home sales are down  -12% from their June 2013 high
Bill's forecast of 20% annual growth will take a real reversal of momentum of most of the metrics (housing starts and sales will have to be up about 25% on average YoY for the next 9 months), although there are some individual months where there are some easy YoY comparisons.  Obviously I am expecting some further deterioration, concentrated between now and mid-year.

Initially after I made this forecast, most people seem to be either surprised by or ignoring the housing slowdown.  While the horrible March new homes number in part reflects the volatility of that series, it seems to have served to concentrate economic minds on the sector now.


Sunday, April 27, 2014

International Week in Review: US Housing Market Starting to Cause Concern Edition

This is up over at XE.com

http://community.xe.com/forum/xe-market-analysis/international-week-review-us-housing-market-starting-cause-concern-edition

Saturday, April 26, 2014

Weekly Indicators for April 21 - 25 at XE.com


 - by New Deal democrat

After two very positive weeks, this week the high frequency data was much more mixed.

I tell ya, I don't get no respect


 - by New Deal democrat

Joe Weisenthal at Business Insider writes that:
[T]here are lots of different ways to measure housing (price, inventory, new home sales, existing home sales, etc.) ....
As Bill McBride at Calculated Risk pointed out in a must-read post this week, the biggest part of the existing home sales decline is due to a drop in distressed housing sales (fewer and fewer firesales as a result of stretched homeowners) while the percentage of sales that are conventional is on the rise. So this is a good sign.
And even new home sales/housing starts (which are off to a sluggish start this year) should be up nicely for the year as a whole.
And he concludes:
 Numbers remain generally up (the numbers that really matter, anyway)....
 Seriously, Joe? Housing starts don't matter?  New home sales don't matter? While starts typically follow the pattern for permits by a month or two (so I am expecting a big YoY gain in starts next month, given their horrible April 2013 number, and as they catch up with permits),  new home sales are just as leading as housing permits.

And the piece Joe cites from Bill McBride was written the day before the awful March new home sales came out.

Here we are, 1/4 of the way through 2014, literally every metric is down YoY except permits, the concerns are sufficient enough that the title of Joe's piece is Is it Time to Freak Out about Housing? and his only cite is to the forecast of an average monthly gain of 20% YoY.  How's that working out so far?

Gee, on the other hand, did anybody say the housing market was going to run into these problems?  Anyone at all?

Now I know how Rodney Dangerfield felt.  I tell ya, I don't get no respect.

Thursday, April 24, 2014

The "rental affordability crisis" is real, but it's about declining real wages, not a bubble in rents


 - by New Deal democrat


Earlier this week there was a post at another site about the "rental affordability crisis."  Claiming there was a bubble in rents as well as housing, the writer called me out by link for my ridicule of Doomers who see a bubble every time a metric goes up.

HIs analysis of the issue was wrong.  The shame is, he highlighted a real, serious problem.  But in his zeal to find yet another bubble, he overlooked the real story, of how declining real wages in the two lowest quintiles have created real hardship for renters in that group.

Let's start with the fundamental mistake that the writer made. He wrote:
"Things are expected to continue getting worse, as rents will outpace the rate of inflation (not to mention incomes) for years to come."
In support of that assertion, he provided the following graph of median asking rents:


You can probably immediately see the problem, just by looking.  The huge increase in rents took place from 2000 through 2008. Rents have varied by only +/-5% since then.  And that's exactly what the data, compiled by the Census Bureau, shows.  The data series goes back to 1988, and below is a chart of nominal asking rents vs. median weekly wages, compiled by the BLS, showing that real rents declined in the 1990s as wages increased, then soared in the 2000 - 2008 period, and have been below that peak ever since:

Year Median
Asking Rent
Usual weekly
earnings
Rent as %
of earnings
Real median
asking rent
198833038286649
1992 40143792 677
1993 422450 88 690
200047856884658
2002 545 60790 717
2004 620629 99 777
200972373299797
2012 72176594 740
2013   Q1 718770 93 722
2013  Q273577695741
2013  Q3 73677895 738
2013  Q4 746782 95 746

Note that from 2000 to 2009, real median rents rose 17.8%, from .84 to .99 of wages.  By January 2013 that was back down to .93, but by the end of 2013 had risen to .95.  

The final column above shows "real" asking rents (rents deflated by the CPI), and indicates that rents haven't even kept up with inflation for the last 5 years (although they increased more than inflation in 2013).  There simply is no bubble in rents.

So what's the big deal?  The problem is that, while median wage earners aren't having a problem, the decrease in real wages in the bottom two quintiles is putting them in a real bind.

The Wharton School of the University of Pennsylvania's public policy brief that is the source of the "rental affordability crisis" information says:
According to data from the U.S. Census, half of all renters, and 83 percent of renters with incomes under $20,000, paid more than 30 percent of their incomes in rent in 2011.
 ....
[D]emand for rental apartments has grown and apartment construction has not kept pace. Between 2010 and 2013, the national apartment vacancy rate fell by half, from 8.0 percent to 4.3 percent,.....
....
...  [But i]ncome growth has failed to keep pace with rental growth over the last decade. At the national level, between 2000 and 2011, growth in REIS rent exceeded the growth in median renter income by the affordability rate to fall further.
Instead, the greatest decline in affordability has occurred amongst low-to-middle income households. [For example, i]n Atlanta, the share of households with incomes between $20,000 and $35,000 in year 2010 dollars who paid at least 30 percent of their incomes in rent rose from about 20 percent in 1980 to more than 80 percent in 2012....Even households in the $35,000 to $50,000 real income tier have experienced declining affordability rates, albeit not to the same degree....However, the highest income groups in the data – households making $50,000 or more in real terms—have experienced little decrease in affordability.

[my emphasis]

In other words, the problem isn't a bubble in rents. The problem is that even when rents have not kept pace with inflation, the income of the typical household that rents has experience a real decline.  The Harvard Joint Housing Center points out [pdf] that in 2010, 70% of all rental households had below the median of household income, and 40% of renters were in the in 25% of household income.

And what has happened to the bottom two quintiles of income earners?  They have fallen further behind the median and the upper 2 quintiles, as shown in this well-known graph of income by quintiles last updated by the Census Bureau in 2011:


And as the Employment Law Project pointed out last June, since 2009 real incomes of the bottom two quintiles - and particularly the fourth quintile -- fell the most in real terms through 2012:


A recently released study by the Harvard Joint Center for Housing Studies noted that "Between 2000 and 2012, real median rents rose nationwide by 6%.  However, over the same time period, the real median income of renters fell by 13%."

In other words, even though rents have failed to keep up with inflation since 2008, and even if they have declined as to real median weekly wages since then, they have continued to increase in real terms compared with the falling real incomes of the bottom two quintiles who make up the typical renter household.  Rental prices have failed to go up more in the last several years not because of a lack of demand, but because higher rents are simply out of the reach of the typical renter.

It's a shame that the writer of that piece was so focused on the idea that there must be a bubble in rentals and housing that he completely overlooked this very real problem. It demonstrates in yet another way that falling real incomes among the lower middle class and working class are destroying the American dream. 

US' Slow Recovery Is Still Intact

All of the coincident indicators are still increasing.

http://community.xe.com/forum/xe-market-analysis/us-slow-recovery-still-intact

Wednesday, April 23, 2014

Increased interest rates, asking prices taking a serious bite out of home sales


 - by New Deal democrat

I have a new post up at XE.com on new and existing home sales.  Total home sales are off -13.5% from their peak 9 months ago, as higher interest rates and an overshoot on increasing home prices is taking a serious bite out of the market

Yield Curve Is Flattening


Above is a chart of the difference between the 30 and 5 year CMTs -- constantly maturing treasuries.  Since the beginning of December, this spread has been declining. 


The reason for the decrease is a rally in the long-end of the curve as the 30 year CMT has decreased from ~ 3.9 to ~3.5, or a decrease of about 40 basis points.  That tells us that traders don't see inflationary pressures.

Tuesday, April 22, 2014

Treasuries Are the Surprise Year to Date Winner

When the Fed announced an end to the quantitative easing program, the treasury market sold off.  The reason is simple: the largest buyer of treasuries had announced they were leaving the market.  However, since January 1, treasuries have outperformed the market as a whole.


When we compare long treasuries, SPYs, commodities (DBC) and the dollar (UUP) since January 1, treasuries again outperform.

Monday, April 21, 2014

The state of housing: an update on permits and starts, and a look ahead


 - by New Deal democrat

One of my key mantras is that I don't fight with the data.  Sometimes there is an obvious asterisk (e.g., the government shutdown, or particularly severe weather, e.g., Sandy), but as a general rule trying to make the data fit your worldview will lead you astray.

With that in mind, much as it pains me to say it, while housing starts and sales have been trending down as I thought they would:


the best and most forward looking indicator, housing permits, has reversed course and trended upward in the last two months:


Last year I pointed out that on 15 of 19 occasions in the last 60 years, when there had been a 1% increase in interest rates, housing permits had decreased YoY by at least -100,000.  One time, in 2000, permits decreased only -62,000.  The three remaining times appear to be cases of "buy now or be forever priced out," in which the housing market levitated for awhile, and then crashed all the harder.

So here is what YoY interest rates (inverted) and housing permits YoY look like updated through March:


While permits have certainly decelerated, they have resolutely not turned negative, something that I absolutely thought would have happened by now.

(By the way, it's not like any of these have approached Bill McBride's forecast of a 20% average gain for 2014 over 2013 either.  He may win his bet with me due to an isolated month of YoY comparisons, in particular June or July, where starts and sales in 2013 posted horrible numbers.  But from here on in permits would have to exceed 1.1 million in a month for Bill to win the bet on that basis, and that seems very unlikely.  And for the record, Bill is the nicest blogger there is and we are on good terms.  This is a friendly bet for charity.)

So why have permits held up?  A lot of the data is exactly what I'd expect to see as permits roll over.  And there are reasons to think that the tow month YoY increase in permits might be an artifact of the unusually severe winter.

To begin with, builders appear to be seeing an actual slowdown.  Here's homebuilder sentiment compared with housing starts (h/t Scott Grannis):


Note that the two generally move in the same direction, and homebuilder sentiment has decreased in the last few months.

More significantly, here is a graph of buyer traffic (via Paper Economy):


Buyer traffic appears to have decreased in the last few months, and is now basically flat YoY.  This certainly does not look like what I would expect to see if there were to be an increase in housing starts or sales.

As to the unusual winter shifting permits in some regions from January and February to March, here are permits in the Northeast:


It looks pretty clear that there were several months of depressed winter data, followed by a huge rebound as the weather broke in March.  Although I won't post it, a similar but smaller rebound occurred in the Midwest, while  the South was negative YoY in March.

So there is reason to believe that the increasing trend in permits YoY since January might be an artifact of the unusually severe winter.

But on the other hand, in support of the reslience of housing permits, the below quote from this article in Redfin points out that several markets are experiencing outright booms:
While the housing market has cooled in many major cities since last year, other cities have only gotten hotter. In certain areas of Texas, North Carolina, Colorado and the Pacific Northwest, homes are selling like hotcakes thanks to strong job and population growth, worsening inventory shortages and ... relative affordability.
And here is the accompanying chart showing the stats:


If there is a migration from high-priced to low-priced housing markets, this could be ameliorating the increase in mortgage rates.

Yet another factor may be the changing rent-vs.-own ratio.  According to the US Census Bureau (pdf), while housing prices declined by about 1/3 from top to bottom, and have made up less than half of that decline since, median rents have remained within 5% of $700 per month since 2008.  In the last few quarters of 2013, they rose to the top end of that range.  In metro areas with relatively expensive rentals, buying a house may be more attractive.

Still, as noted by Realty Trac, the increase in mortgage rates has raised the minimum down payment to buy a house by about 20%:
The income needed to qualify for a median-priced home in the fourth quarter of 2013 was $41,500, up from an average minimum income of $34,250 a year earlier. (That minimum assumes you'll spend no more than 25 percent of your household income on your mortgage.)
 Not coincidentally, the number of months' supply of houses has been slowly rising.  In this week's reports of new and existing home sales, I will be particularly looking to see if this increase continues.  There does not appear to be any magic number, as the below graph indicates, which compares the median house price change YoY (left scale) with the monthly supply of houses (inverted, right scale):


In the 1960s, 5 months supply was enough to bring prices increases to a halt.  In the 1970s and 1980s, it was more like 7 months.  In 2006, it was between 5 and 6 months' supply.

April and May of last year were particularly strong months for housing permits.  If they are going to turn negative, those are the months where they should do so. If double-digit price increases continue, and affordability rapidly declines, then as with the prior 3 occasions, delaying the day of reckoning will only make it a harder fall.

So tomorrow and Wednesday, I will be paying particular attention to the median price months' supply of both new and existing homes.  Is there evidence that the market has not withstood the most recent price increases?  In the case of new homes, there is already evidence that there has been a peak, and YoY price increases may have ended.  Is the months' supply steady, or is it increasing further?   An increase in the months' supply is evidence supporting that there is or shortly will be a pullback in building.


Latin American Markets Rebound


Latin American markets sold off in tandem when the Fed announced the end of QE, which basically reversed the flow of "hot money" funds leaving the US into development markets.  Also hurting these economies is the Chinese slowdown, as many of these countries supply raw materials to the Chinese economy. 

But LA has made some impressive strides in its own right, which were heavily discounted in the sell-off.  Traders have obviously reassessed these markets and are again committing funds.

Chile and Colombia are understandable bets; both countries are on fairly decent economic footing.  Brazil is a bit more of a puzzle, as there hasn't been much good news from that country since the first of the year.  And Argentina has some issues, especially with its publicly released economic numbers that make me question its market strength.


Here's a chart of the regions performance over the last year.

Sunday, April 20, 2014

A thought for Sunday: the legacy of a fateful choice


 - by New Deal democrat

Bonddad's  weekly international summary, below, is well worth a read at XE.com.  In it he describes the deflationary danger of the pro-creditor/pivot to austerity choices that were made in the developed world.

The below quote, from Larry Summers describing his "secular stagnation" theme,  in particular leapt out at me:
 in such a situation falling wages and prices or inflation at slower-than-expected rates is likely to worsen economic performance by encouraging consumers and investors to delay spending, and to redistribute income and wealth from higher spending debtors to lower spending creditors.
 In 2008-09, we could have bailed out debtors, or we could have bailed out creditors.  Had we bailed out debtors, the debtors could have used that bailout money to renegotiate, pay down, or pay off their debts to the creditors, and then both would be made reasonably whole.  Bailing out creditors rescued them, but didn't cancel the debt, and so debtors still had to deleverage and pay off the debts, a painful and slow process.

At that critical juncture, none other than Larry Summers had the most powerful position possible to argue in favor of bailing out debtors, but did not do so.  We chose creditors, and we've been paying the price since.

Friday, April 18, 2014

No, the ratio of "employer-to-employer flows" does *NOT* prove the job market isn't improving


 - by New Deal democrat

Mike Konczal of the Next New Deal has a post up claiming to show that even the currently employed are struggling to find jobs, and therefore there has been no jobs recovery.  Like many Doomish arguments, it suffers from "proving too much."  The author finds some metric either flatlining or going down since 2009, therefore conditions are not improving.  The author never thinks through the implications of the same data showing the exact same thing for previous economic expansions.  That's Konscal's problem here.

Konczal says:
Even those who have been unemployed zero weeks are having trouble finding jobs in this economy. And this is important evidence against the idea that the labor market is doing better than people realize if you just ignore the long-term unemployed.
....  If the economy is heating up significantly and the long-term unemployed aren’t capable of taking jobs, then the EE transition rate should be increasing. So how is it doing?
.... If the economy was heating up and the unemployed or those out of the labor force couldn't take jobs, we would expect this to increase
Here's the graph Konczal uses to support his conclusion:


Except here's the problem:  the graph just isn't flatlining since 2009 to the present.  It also flatlines from 2003 to 2008, and even more tellingly, from 1994 to 1999 - during the biggest economic boom since the 1960s (highlighted below):


 Is Konczal seriously contending that "the labor market wasn't improving" during the biggest boom in the last half century?

The "stair-step down" trend in Konczal's graph reminded me of another, namely, the employment to population ratio.  Here is that graph for the same period of time:


As it turns out, that isn't a coincidence.  The Census Bureau also took a detailed look at this data in 2006 (pdf).  Here's their graph showing the data up until that point:


Notice how closely the data tracks the employment to population ratio.  Unlike Konczal's graph, the Census Bureau's graph does slightly increase during the mid-1990s.  This is likely due to the fact that the two graphs are measuring slightly different things: Konczal's graph measures the "percentage of employed moving straight to a new job" on a 6 month basis, while the Census Bureau's graph measures "number of flows as a fraction of employment" on a quarterly basis.

Konczal's problem is that he entirely fails to take into account the effect of demographics.  Here's the Census Bureau's graph showing how employer to employer flows skew by age:


A huge percentage of employer to employer flows comes from people in their 20's.  The percentage declines sharply as we move into the 30's and continues to gradually decline thereafter until about age 60.

So what Konczal has failed to account for is the huge distortion in the demographics of the work force caused by young people staying in college longer, and by the Boomer generation skewing the median employment age much higher into the age group that wants nothing more than to hang on to their current job until retirement age.

In other words, Konczal's graph appears to be another manifestation of the employment to population ratio, and not say anything about the relative strength of this job recovery.  (My position remains, there has been a jobs recovery, it just hasn't been strong enough.)  His data is sound, but his conclusion is faulty because it proves too much.

Thursday, April 17, 2014

A note about the strong rebound in March economic data


 - by New Deal democrat

I have a post up at XE.com about the recent run of excellent March economic data.

Thoughts On Inflation In Light of Yellen's Comments Yesterday

This is up over at XE.com

http://community.xe.com/forum/xe-market-analysis/thoughts-us-inflation-light-yellens-comments

Coke and Pepsi Now Tied Over the Last 10 Years


When I was a kid, I assumed that coke was the stronger brand.  In retrospect, that impression was probably created by the "Pepsi challenge" marketing plan when I was kid (this was the 1970s).

But flash forward to the last 10 years and you wind up with a tie game between the performance of both stocks.  Pepsi was the winner during the previous expansion.  The two had similar performance in '08, Coke eventually outperformed Pepsi from 11-13, but now the two are more or less tied.