Tuesday, April 26, 2011

A Closer Look at M2

Investopedia defines M2 as:
A category within the money supply that includes M1 in addition to all time-related deposits, savings deposits, and non-institutional money-market funds.

M2 is a broader classification of money than M1. Economists use M2 when looking to quantify the amount of money in circulation and trying to explain different economic monetary conditions.
In other words, M2 is liquid money (M1) plus assets consumers can readily access, but usually use as "back-up" funds like savings accounts and money market accounts. This is money that people keep in reserve.


Let's begin our look at M2 with a simple logarithmic chart of M2. Notice that -- unlike M1 -- M2's rise is far more consistent over the last 25 years. While its rise was somewhat slower during the first part of the 1990s expansion, its rise continued in the mid-1990s and has moved higher at near the same pace for the last 15 years.


Above is a chart that shows M2 and GDP on a scale of 100 to better compare their relative performance. Note that unlike the M1 chart from yesterday, this chart shows a closely correlated performance of both numbers, indicating a strong relationship.


The M2/GDP YOY percentage change comparison for the 1980-1994 periods reveals little correlation. At times they move in tandem, but at over times they move in completely opposite directions. There is a general relationship for the 1980s expansion as both lines have a general downward shift, but the relationship is at best casual; no firm conclusions can be drawn from this chart.


Link
The lack of correlation between the YOY percentage change between M2 and GDP continues in this chart that shows the relationship for 1993-2010. In fact during both recessions there is an inverse relationship between the two -- a very counter-factual development indeed.

Like M1, the the YOY charts show nothing meaningful, although the scale 100 charts show a strong overall correlation.

Treasury Tuesdays

Last week, I wrote the following about the Treasury market:

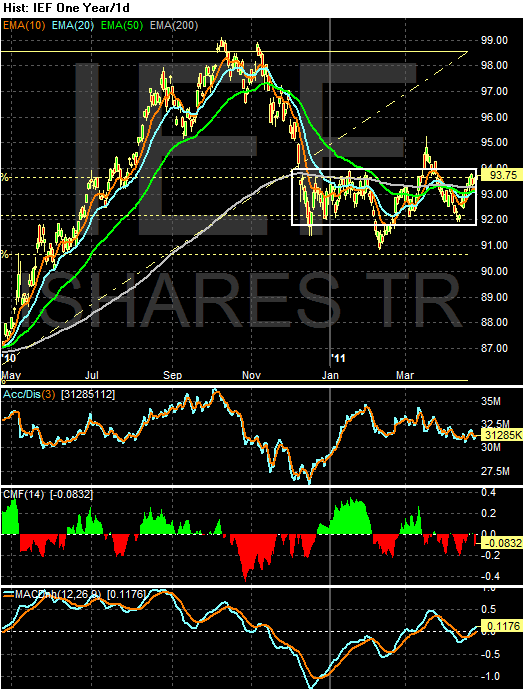
I'm treating the current action as a consolidation range and would wait to make a trading move until after prices convincingly choose a direction. For the IEFs, that would be a move above 94-94.5 or a move below 92. For the TLTs, it would be a move above 93.5 or a move below 90.

Very little has changed to alter that opinion about the market. Let's start by looking at the IEFs:


Last week, prices clustered right about the 200 day EMA. The 10, 20 and 50 day EMAs are all moving higher, but are in a very tight range and are right below the 200 day EMA.


Looking at the underlying technicals, we see the A/D and CMF showing a slightly negative bias, but nothing to show a massive exodus from the market. The MACD has given a buy signal, but the lines are right around 0, indicating the EMAs are just crossing into a positive correlation.


At the long end of the curve, notice prices are finding strong resistance at the 200 day EMA -- they have hugged the line for the entire week.

The long end of the curve is still contained by the 200 day EMA -- a technically important development. In addition, the Treasury market is still in a trading range. Until we see a convincing move in either direction, I would not be trading this market.

Monday, April 25, 2011

Actually, Mr. President, it's Called Supply and Demand

While the president is convening a counsel to look into price manipulation in the oil markets, consider these data points:

From Bloomberg:

Crude oil gained for a fourth day in New York, the longest rising streak since December, as escalating violence in the Middle East and Africa threatens to prolong supply disruptions.

Futures advanced as much as 0.7 percent after Syrian security forces detained at least 200 protesters while unrest showed no sign of ending in Yemen. U.S. Senator John McCain said rebels in Libya need more assistance in the fight against Muammar Qaddafi’s forces. Saudi Arabia, holder of the world’s largest crude reserves, has no plans to raise production capacity, an oil official said.

Political developments in the Middle East and North Africa are providing the main support for prices, according to a report from JBC Energy received by e-mail today.

“The oil market remains fraught with uncertainty,” the Vienna-based analysts said. “Most of it is related to possibilities in the future, including the developments in all the geopolitical hotspots, the inflation threat and its impact on the economy,” as well as a possible decrease in demand due to high prices.

Political unrest leads to decreased supply -- at a time of rising demand. You do the math.

And read this update from Prof. James Hamilton.

While it's nice to have someone to blame (this evil people on Wall Street and traders in general) the reality is the commodities markets are being driven by pure supply and demand right now. I realize that's a far less exciting story, but that's what the data says.


A Closer Look At M1

Last week, I wrote a post on monetary velocity which got me thinking about monetary policy in general. So this week I'm going to look at the macro money statistics and how they relate to GDP.

Let's start with M1

A category of the money supply that includes all physical money such as coins and currency; it also includes demand deposits, which are checking accounts, and Negotiable Order of Withdrawal (NOW) Accounts.

This is used as a measurement for economists trying to quantify the amount of money in circulation. The M1 is a very liquid measure of the money supply, as it contains cash and assets that can quickly be converted to currency.


M1 is basically spending money -- money we are most likely to use in daily transactions. Also note this definition includes demand deposits, which we access with debit cards -- a far more common transaction these days.


Above is a chart of M1 in logarithmic scale. Notice that it rose consistently from 1975 to the mid-1990s, then moved sideways until just after the recession of the early 2000s. It moved slightly higher again before moving sideways for the second half of the last expansion. During the recession, the Fed pumped a lot of money into the economy which explains the big move higher starting in the middle of the last recession.


The above chart fleshes out the relationship between M1 and GDP by using the scale 100. Notice their is a strong correlation between the two, but the correlation is not exact. In the mid 1990s when the economy continued to grow, M1 was near stagnant. The exact same situation played out in the expansion of the 2000s. The reason the economy continued to expand during both of these sideways moves in M1 was monetary velocity continued to increase:


In the above chart of M1 velocity, notice that velocity continued to increase in the second half of the 1990s and 2000s expansion. As the pace of money moving through the economy increases, lesser amounts of currency is needed.


Above is a comparison of the year over year percentage change in M1 and GDP. Notice there is a general relationship from 1975 - 1985. However, as the year over year rate of change in M1 becomes more extreme in the late 1980s, its relationship to GDP is oddly reversed for the years 1985-1987, although you could also argue there is a delayed effect of the monetary spike.


M1's YOY percent change was also fairly extreme in the 1990s. It bears some relationship to GDP performance, but not enough to warrant any firm conclusions. The same is true for the relationship between M1's YOY and GDP's YOY percentage change during the 2000s

What I find interesting is the one to one correlation exists, but it is not as strong as I would have expected (although the lack of strong correlation for part of the time is explained by higher monetary velocity). I'm also very interested in the YOY charts. It could be argued that flooding the economy with money during and right after a recession has an effect, but the effect is much weaker when the economy is already expanding.

Crossing the Rubicon: Obama vs. Reagan

- by New Deal democrat

At the end of 2007, I had an argument with democratic activist Dana Houle (a/k/a DHinMI), who argued that 2008 would likely be a fundamental turning point, a realignment of the economy and the electorate, just as the 1932 election had been.

To the contrary, I argued that 2008 would be like 1968, in which the new electoral majority began to emerge, but fundamentally reversed none of the prior paradigm. In fact President Nixon established the EPA and said "We are all Keynesians now." Barring an economic calamity that would force people to jettison long-held precious ideological beliefs, I did not see how 2008 could produce anything other than a transitional presidency.

One year later and it seemed like we were in the process of undergoing that calamity. But whereas the Great Depression saw increasing Democratic Congressional majorities in each election from 1930 through 1936, instead in 2010 the Democrats gave back most of their 2008 gains in the Senate, and all of their gains from 2006 in the House. If there was no 1932 style realignment, what about Reagan's signature 1980 victory, which produced a Republican Senate for 6 years, even though there were losses in 1982? Or was 2008 indeed more like 1968, where established party dominance of the political narrative was largely unbroken, or even extended?

In 1932 and 1980, the country "crossed the Rubicon" in its political and economic thinking. Fundamental ideological paradigms were changed. Has Obama "crossed the Rubicon" as well, for good or ill? I envision this being a periodic series, for I as a voter am also strongly considering "crossing the Rubicon" as it pertains to Barack Obama and the institutional Democratic party.

So let's begin by stacking up how Obama's economic performance compares with that of Reagan. [Note: keep in mind that in the graphs below, a 24 or 27 month period of Obama's presidency is being compared with the entire first 4 yeas of Reagan's presidency.]

GDP:

In Obama's first two years, real GDP has gone up 3%:


During Reagan's first two years of office, GDP had barely budged, up 1%. But it gained 12% in the next two years. Thus, for Obama to equal Reagan's record, GDP must go up 5% a year in real terms this year and next:


Industrial Production

Two years and three months into Obama's term, Industrial production is already up 7%:


Industrial production only reached 7% growth at the end of Reagan's first term of office. At this point in Reagan's first term, Industrial production was still off about 4%:


Employment

Employment has shrunk about 2% in the first 27 months of Obama's term:


Reagan posted a similar 2% loss after 27 months, but over the next 21 months, employment grew another 8%:


Unemployment

At 8.8% unemployment is about 1% higher than when Obama took office:


Twenty-seven months into Reagan's first term, unemployment was still over 10%, but it would shrink all the way down to under 7.5% in the next 1 3/4 years:


Real Income

Real income is barely higher than what it was when Obama took office:


By this point in Reagan's first term, real income was up about 2%. It would go up another 12% before his first term ended:


Inflation

When Obama took office, the country was on the verge of a deflationary spiral. It was reversed, with inflation now running at close to 3%:


The economic Rubicon that Reagan had to cross when he entered office was that of high inflation and the wage-price spiral that had accelerated in the 1970's. Two and one quarter years into his first term, it had been conquered, going down from 12% to 3%:


Mortgage Rates

During Obama's term, conventional mortgage rates have meandered between 4.2% and 5.4%:


With the slaying of high inflation, mortage rates during the first 2 1/4 years of Reagan's first term declined all the way from over 18% to under 13%, a huge difference in terms of a family's income that was required to pay this most important monthly bill:


Housing starts

Housing starts have meandered in the 500,000-650,000 range during Obama's term:


Because of the large decline in mortgage rates, 27 months into Reagan's first term, housting starts had increased nearly 900,000 from their bottom, although they were only about 100,000 annualized than when Reagan took office:


Oil prices

Twenty seven months into Obama's presidency, Oil prices have more than doubled:


At the same point in Reagan's presidency, Oil prices had declined by about 30%. They would fall nearly by half, by the end of his first term:


In summary, while Reagan's progress lagged Obama's in a few metrics like Industrial Production, by this point during his first term Reagan had crossed his economic Rubicon. With the assistance of a Fed-induced brutal recession, inflation had been broken. The last two years of his first term saw strong growth not just in the broad economy, but in such measures as real income, employment and unemployment, and housing starts. The Oil shocks of the 1970's receded. He was re-elected in 1984 by a landslide, and the GOP kept control of the Senate.

By contrast, while Obama has made progress against the economic declines of the great recession, unless the housing market shows real signs of a strong rebound in the next year, (contra Calculated Risk who is predicting at least 3 more years until it does so), and unless Oil miraculously goes into a long lasting decline without harming economic demand in the process, he will have failed to resolve the secular economic problems which brought him to power. 2008 will be seen as a failed turning point, or at most a 1968 style election where the next electoral majority began to emerge, but failed to fundamentally change the existing course.

Equity Week in Review and Preview of the Upcoming Week/Month

Last week I wrote the following about the markets:

For the last few weeks, I've felt the market was going to be moving sideways. That is still my general analysis. I don't see any reason for a major correction right now; instead, I believe the markets and traders are in a wait and see position.

The market is facing some strong headwinds: the end of QEII, China tightening, Japan recovering from its earthquake, high gasoline prices, budget stupidity in Washington, continuing EU problems and high commodity prices. We're currently seeing a wave of first quarter GDP downward revisions, which will probably continue as we go forward. However, as I will write throughout this week, the latest Beige Book is surprisingly strong -- much stronger than I originally anticipated. This should give traders pause is selling all their positions.
I would now add two more concerns. The first is a big drop in consumer sentiment, as reported by the NY Times:
Americans are more pessimistic about the nation’s economic outlook and overall direction than they have been at any time since President Obama’s first two months in office, when the country was still officially ensnared in the Great Recession, according to the latest New York Times/CBS News poll.
The article notes that with high gas prices and still high unemployment, people have little to be happy about. This drop was also noted in the latest LEI release from the Conference Board which I analyzed here.

The second issue is a drop in the Philadelphia area manufacturing index last week.
Results from the Business Outlook Survey suggest that regional manufacturing activity continued to grow in April but at a slower pace than in March. Nearly all of the survey’s broadest indicators remained positive but fell from their readings in the previous month. Increases in input prices continue to be widespread, and a significant percentage of firms reported increases in prices for their own manufactured goods. The survey’s indicators of future activity fell notably this month; however, most firms expect continued growth over the next six months.
This is only one month worth of data, so take the concern with a large grain of salt. The NY Fed had a similar drop late last year, and came roaring back. However, the overall timing couldn't be worse. In short, the macro environment is turning neutral, which I believe will prevent a strong upward move in the equity markets.

Let's go to the charts:


On the daily five minute chart we see an upward bias. However, On Wednesday and Thursday prices gapped higher at the open but did not follow through. That means that a futures move kicked off trading higher, but there was no reason throughout the day to keep buying shares. As such, we see the following on the SPYs:


Note the very weak candles on the chart, which are accompanied by low volume. The EMAs are also in a tight bunch, indicating a lack of overall direction.

Adding to my overall concern are the transports:


Note the incredibly low volume and lack of any meaningful upward movement last week. The 10 day EMA has just recently turned higher and the upward angle of the 20 day EMA is very weak. Furthermore, prices rallied to the 97.5 area, only to fall quickly -- and that was after a big gap higher. Recently, prices have not mirrored the upward move of the broader equity markets, which is very concerning.


The Russell 2000 (IWMs) are also in pretty weak shape. While prices have gapped higher the last two days, the candles printed have been very weak and on low volume. And, the EMAs have the same problem as the SPYs EMAs.

In short, I still see the markets taking a wait and see attitude right now. There is concern about the underlying fundamentals that I believe will eventually weigh down any advance. Any move above technically important levels should be viewed with extreme caution unless accompanied by a fundamentally altering event such as a great unemployment report, a clear policy change from Washington that creates more fiscal stimulus, or a good GDP report that surprises the markets. I see the SPYs as being contained by the 134.5 level, the QQQs contained by the 59 level and the IWMs contained by the 86 level. I also see the possibility of prices beginning a consolidation phase where they form a standard consolidation pattern such as a triangle or rectangle.

This week we have consumer confidence which will provide much needed more data on the consumer's sentiment, along with durable goods orders and GDP. I am very interested to see how GDP prints and more specifically its overall internals.

While it is possible that I am reading the tea leaves too conservatively right now, I believe the fundamental backdrop warrants such concern. For more detail, see this link.

Friday, April 22, 2011

Weekly Indicators: R.I.P. Joe Battipaglia edition

- by New Deal democrat

The big monthly news this week was the continued advance of the Leading Economic Indicators for March, up 0.4. February was revised upward to up 1.0. The LEI was greatly helped by the strong monthly rebound of housing permits from February to March, and strong vendor deliveries in the ISM manufacturing survey, showing that manufacturing remains on a tear, and is powering the recovery. Similarly, the Philly Fed survey declined from stratospheric levels last month, but was still showing strong expansion. Other housing data - starts and existing home sales - also bounced strongly higher from February's poor readings.

Will strong manufacturing and associated exports help the US overcome the renewed Oil shock? Will there be a slowdown, or something worse? That's where we are now.

Turning to the high-frequency weekly indicators:

Oil finished the trading week at $112.29 a barrel, the sixth full week it has been above $100. It remains at a level above 4% of GDP. Gas at the pump increased $.05 more to $3.84 a gallon. In the last 6 months, gas prices have gone up over $1 a gallon. Gasoline usage at 9062 M gallons was 1% lower than last year's 9152. This YoY comparison has been negative for the last six weeks in a row, averaging -1.5% for the last four weeks. If this level of decline continues for another month or so, that will be equivalent to the decline near the end of 2007.

The BLS reported that Initial jobless claims last week were 403,000. The four week average has gone back up to 399,000, This series has not made a new low in seven weeks, and has been back over 400,000 for two weeks in a row.

Railfax was up 3.9% YoY. Baseline traffic is still barely ahead of last year's levels. Cyclical traffic's advance over last year is holding even. Only intermodal traffic (a proxy for imports and exports) continued significantly higher last week. Waste materials continued below last year's levels and shipments of motor vehicles continued well ahead of last year's pace.

The Mortgage Bankers' Association reported an increase of 10.0% in seasonally adjusted mortgage applications last week, to a level last seen in December 2010. Because this may have been due to special factors, expect a similar decrease next week. In general this series has meandered in a range since last June. Refinancing increased 2.7%, and remains near its June-July 2010 lows. But neither series is in a long term decline any more.

The American Staffing Association Index remained at 92 for the third week, after stalling at he 90-91 level for 7 weeks. So far this year this series' slow progress is similar to that of 2007 and 2008.

The ICSC reported that same store sales for the week of April 2 rose 3.0% YoY, and increased 0.3% week over week. Shoppertrak reported a meager 1.4% YoY increase for the week ending April 16. It also reported a WoW decline of 2.1%. Calendar affects (Easter week this year vs. last year) continue to strongly affect these results, but the Shoppertrak result in particular is not what one would expect getting closer to Easter. This is the first hint in these series of any fallout from $100+ Oil.

Adjusting +1.07% due to the recent tax compromise, the Daily Treasury Statement showed that for the first 14 days in April 2011, $105.5 B was collected vs. $96.6 B a year ago, for an increase of $8.9 B YoY. For the last 20 days, $133.7 B was collected vs. $126.9 B a year ago, for an increase of $6.8 B, or 5.4%. I suggest using this series with extra caution, because the adjustment for the withholding tax compromise is only a best guess, and may be significantly incorrect.

Weekly BAA commercial bond rates decreased .03% to 6.07%. This compares with an identical 03% decrease in the yields of 10 year treasuries to 3.51%. Over the last 6 months both series have seen higher interest rates, but government bonds have generally been weaker. There remains no sign of corporate distress here.

M1 was down 1.0% w/w, up 1.3% M/M, and up 11.9% YoY, so Real M1 is up 9.2%. M2 was unchanged w/w, up 0.2% M/M and up 4.7% YoY, so Real M2 is up 2.0%. Although Real M1 is still strongly in the "green zone" where it has been since before the end of the "great recession," Real M2 continues to fade further back into the "yellow zone" below 2.5%.

Finally, this week I want to pay tribute to market pundit Joe Battipaglia, who passed away suddenly last week. I first heard him in about 1994. Bears like Jim Rogers were persuasively making their case, the market would swoon 10%, Elaine Gharzarelli would say her market indicators now foretold a crash, and along would come raging bull Joe Battipaglia, making the case that tech advances were a tsunami of rising efficiency. Of course, the market would turn within minutes of Gharzarelli's pronouncement of Doom. Battipaglia wasn't just right. He was right for the right reasons. But he wasn't a permabull. He was much more sober and cautious at all of the right times this past decade, but bullish again in the last couple of years.

In short, amidst all of the pundits talking their book to the rubes, Joe Battipaglia stood out as someone who continued to be mainly right, and mainly for the right reasons. Allow me to pay him the highest compliment for a pundit: when Battipaglia talked, I stopped and listened. He will be missed.

Remember that all things must pass, including our own brief tenures. Carpe Diem! Enjoy this weekend.

Leading Indicators Up .4

From the Conference Board:

Says Ataman Ozyildirim, economist at The Conference Board: “The U.S. LEI continued to increase in March, pointing to strengthening business conditions in the near term. The March increase was led by the interest rate spread and housing permits components, while consumer expectations dropped. The U.S. CEI, a monthly measure of current economic conditions, also continued to rise, led by gains in industrial production and employment.”

Says Ken Goldstein, economist at The Conference Board: “The U.S. LEI continues to point to sustained economic growth through year end. Global disruptions, including unrest in the Middle East, rising oil prices and the Japan earthquake, may have some repercussions. However, it remains to be seen what the impact of these shocks will be on the United States and the broader global economy.”

Take a closer look at the underlying data:

Click for a large image

While the overall index is up, there are a few points about the data that is concerning.

1.) The average workweek is barely up since last September. Consider that data in light of this chart of the Index of Aggregate Weekly Hours of Production and Non-Supervisory Employees

The total dropped hard during the recession and is still barely recovering, indicating there is still tremendous slack in the labor market that employers can access before adding a bevy of new employees.

2.) Manufacturers new orders for non-defense goods tumbled last month. Consider that in light of the larger durable goods picture.

3.) M2 dropped slightly and the interest rate spread came in slightly.

4.) Consumer expectations took a tumble and accounted for a large percentage of the negative side of the LEI equation. This is probably the result of fuel prices. Here is more information on the situation:

Amid rising gas prices, stubborn unemployment and a cacophonous debate in Washington over the federal government’s ability to meet its future obligations, the poll presents stark evidence that the slow, if unsteady, gains in public confidence earlier this year that a recovery was under way are now all but gone.

Capturing what appears to be an abrupt change in attitude, the survey shows that the number of Americans who think the economy is getting worse has jumped 13 percentage points in just one month. Though there have been encouraging signs of renewed growth since last fall, many economists are having second thoughts, warning that the pace of expansion might not be fast enough to create significant numbers of new jobs.


Friday Linkfest

Corey looks at the Treasury and silver market.

Invictus takes Heritage to task (again) -- and Menzie Chinn follows up as well.

College loans weigh on graduates.

Housing lock is not preventing employment migration.

What -- US Worry?

Why Multi-nationals expand abroad.

Is export led growth still a viable strategy?

Thursday, April 21, 2011

Friday Dollar Analysis

Here is what I wrote about the dollar last week:

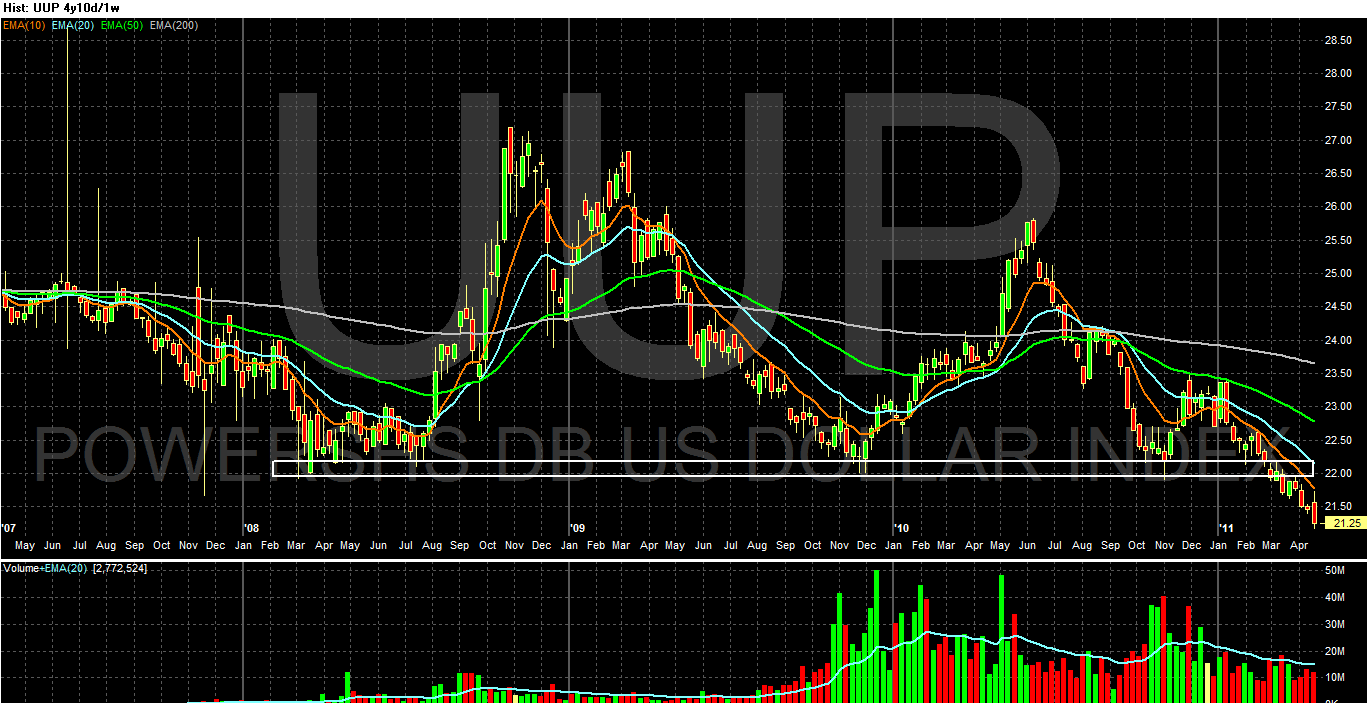
Adding all of these factors together, we get a chart that is fundamentally very bearish in multiple time frames. The multi-year chart shows prices breaking lower from a long consolidation pattern, the 6-month chart shows prices in a lower low, lower high structure and the technical indicators are all bearish. This is backed by the fundamental background.

1.) Other countries are raising rates, making their economies more attractive as a place to park short-term investments.
2.) It appears that US growth is slowing. This is adding to the bearish analysis.
3.) The long-term budget situation is still at best murky.
4.) There is concern about inflation, and whether or not the Fed is behind the inflation 8-ball.

However, over the next week or so, don't be surprised to see the dollar rise. Why?

On the chart notice that prices have gapped lower on slightly heavy volume. A rebound into the EMAs is possible at this level.


The 4-year, weekly chart of the dollar shows the market has clearly dropped below the 22 price level, which had provided technical support for the last four years. Also note the weekly EMA positions -- the shorter EMAs are below the longer EMAs, prices are below all the EMAs and all are moving lower. This is the most bearish orientation possible.


The daily chart is also extremely bearish. All the EMAs are moving lower, the shorter are below the longer and prices are below all the EMAs. While we should expect prices to rebound in a standard move, expect to see the EMAs provide upside resistance.


The technical position is still very bearish as well. The A/D and CMF show money leaving the market and the MACD shows no momentum whatsoever.

Given the above charts, and the fact nothing has fundamentally changed in the big picture for the dollar, my assessment of the dollar market for the coming week is the exact same as it was for last week: more moves lower with rebounds into the EMAs providing upside resistance.

Money Velocity Is Way Too Low

The velocity of money is defined thusly:

The speed with which MONEY whizzes around the economy, or, put another way, the number of times it changes hands. Technically, it is measured as GNP divided by the MONEY SUPPLY (pick your own definition). It is an important ingredient of the QUANTITY THEORY OF MONEY.

This statistic measures how fast money is moving through the economy. For example, suppose I get paid on Friday. If I spend most of my paycheck that weekend, the money velocity created by my spending will be high. However, suppose I put all my money in a bank account and don't spend it until a year later. That would lead to a lower money velocity and lower growth.

In light of that, consider the following charts of money velocity.


M2's velocity is slightly above multi-decade lows


M1's velocity is still high, but it dropped during the recession and continues to move lower.


MZM velocity is just above multi-decade lows.

In short, all the velocity indicators are telling us that the turnover of money is weakening, indicating slower transactional speed and hence weaker economic activity.

Obama approval: in fact it's a gas, too

- by New Deal democrat

Yesterday I discussed how Oil prices have shot up enough to be considered a "shock" to the economy. One person in particular who should be very concerned by that is President Barack Obama. Why? Because his approval ratings, like those of George W. Bush before him, have closely tracked with the price of Oil.

Prof. Pollkatz notoriously kept a record during the eight years of Bush's presidency of a graph he called "Bush Approval: In Fact It's a Gas":


If you look carefully, you can see how Bush's approval rating lagged changes in gas prices by about 2 to 3 months consistently throughout his presidency.

Now, let's look at a graph published yesterday of the ABC/Washington Post poll showing Barack Obama's approval ratings tied for their lowest to date, and conversely disapproval the highest:


Now here is a graph of gasoline prices from January 20, 2009 to date:


Notice that both Obama disapproval and gas prices have the same series of peaks and valleys, and keep in mind that Obama's approval ratings, like Bush's, appear to lag a couple of months behind gas prices - suggesting that the last surge in gasoline prices hasn't yet found its way into Obama's approval ratings.

There's no rocket science here. Presidential approval ratings tend to track the economy, and gas prices, especially as they reach the thresholds we discussed yesterday, take a few months to feed through into the economy as a whole.

Barack Obama should be thanking his lucky stars that it is 2011 and not 2012. And he'd better hope that Oil's choke hold on the economy loosens by then.

Beige Book, Part IV: Banking/Finance

From the Federal Reserve:

NY: Bankers report decreased demand for consumer loans and residential mortgages, increased demand for commercial mortgages and no change in demand for commercial and industrial loans. The decrease was most prevalent for residential mortgages. Bankers indicate steady demand for refinancing. Respondents report no change in credit standards for consumer loans and a tightening of credit standards for the other loan categories. No banker reported an easing of credit standards in any category. Bankers report a decrease in spreads of loan rates over costs of funds for residential mortgages but no change in spreads in the other loan categories. Respondents also note a decrease in the average deposit rate. Bankers report an uptick in delinquency rates for commercial and industrial loans but no change in delinquency rates for the other loan categories.

Philly: Total outstanding loan volume at most of the Third District banks contacted for this report has shown little change in recent weeks. Some banks in the region reported recent increases in lending extended on home equity credit lines, but other forms of consumer credit have been level or moved down. Some banks reported increases in commercial and industrial loans and some types of commercial real estate loans. One banker said, "We're making more small business loans, and commercial real estate lending is picking up except for retail properties." The outlook among Third District bankers interviewed for this report is that total loan volume will expand slowly this year, as overall economic activity advances, with gains mostly in commercial and industrial and consumer lending, but lending for residential or commercial construction is not expected to increase.

Cleveland:
Bankers reported that demand for business loans grew at a modest pace since our last survey. Although demand was characterized as broad-based, some bankers commented that applications were strongest from health-care providers and energy companies. On the consumer side, a majority of our contacts indicated that credit demand has picked up slightly, primarily for vehicle purchases (direct and indirect) and home equity lines of credit. Interest rates for business and consumer credit were stable, but competitive. Demand in the residential mortgage market is mainly for refinancings, although applications have slowed due to rising interest rates. Core deposits continue to grow, but at a lower rate, with almost all growth occurring in nonmaturing products. Credit standards were unchanged. The credit quality of businesses and consumer applicants was characterized as stable or improving, while delinquency rates were steady or trending down across most portfolios. Staffing levels have shown little change during the past few weeks, and only selective hiring is expected during 2011.

Richmond: Banking activity picked up across the District. Most bank officials whom we contacted noted a marked increase in interest from business clients, often to restart projects that had been delayed over the past two years. Several bankers also reported that their lending had grown from weak levels at the end of last year. A Virginia banker stated that consumer demand, while still quite soft, had improved, while a Richmond banker in a relatively affluent neighborhood cited a spike in equity line usage (often to be used for pre-sale home renovations). Most commercial bankers reported that small business lending had strengthened somewhat, with much of the funds going to equipment upgrades and plant expansions. A bank official in West Virginia reported that auto dealer inventory financing increased, but overall the bank's loan pipeline was slack and he was unenthusiastic about loan demand in general. Reports on mortgage lending activity were mixed.

Atlanta:
District bankers reported that demand for most types of loans remained low and lending standards remained tight in February and March. Many cited that credit was available but finding qualified borrowers continued to be difficult. Some community bankers noted encouraging reports of loan demand surfacing in the last few months, especially among small business owners.

Chicago: Credit conditions continued to improve in February and March.
Banking contacts indicated that the business loan pipeline was still not robust, but that there were some areas of growth in manufacturing, food processing, and healthcare. Competition continued to be fierce for high-quality commercial and industrial loans (both large and small) leading to more aggressive terms and pricing. In addition, bank and non-bank investment in commercial real estate assets was also noted to be increasing. Consumer lending was little changed from the previous reporting period. Mortgage applications decreased and those made were primarily for purchase, as refinancing slowed with a rise in mortgage rates. Several contacts raised concerns about the impact that uncertainty surrounding the future of Fannie Mae and Freddie Mac and the regulatory environment were having on mortgage credit availability.

St. Louis: Total loans outstanding at a sample of small and mid-sized District banks decreased 3.2 percent in the three-month period from mid-December to mid-March. Real estate lending, which accounts for 74.9 percent of total loans, decreased 1.3 percent. Commercial and industrial loans, accounting for 15.4 percent of total loans, decreased 8.7 percent. Loans to individuals, accounting for 5.0 percent of loans, decreased 2.6 percent. All other loans decreased 16.7 percent and accounted for 4.7 percent of total loans. Over this period, total deposits decreased 1.7 percent.

KC: In the recent survey period, bankers reported weaker loan demand, but also rising deposits and improvements in loan quality. Overall loan demand decreased as demand for commercial and industrial, residential real estate, consumer installment, and commercial real estate loans declined. For the fifth straight survey, credit standards remained unchanged in all major loan categories. Deposits increased further in the recent survey period. Bankers also reported improvements in loan quality compared to a year ago, and they expected further improvements over the next six months.

Dallas: Financial firms reported a slight improvement in overall loan demand. National banks reported some pickup in commercial and industrial (C&I) loan demand with increased corporate activity, while they continue to see weakness in commercial real estate (CRE). Regional banks noted that loan demand remains pretty flat, although there was a small increase in optimism regarding homebuilding and some CRE lending at the community-bank level. Most contacts said loan pricing remains aggressive amidst a highly competitive lending landscape. Outlooks are gradually improving in light of better outstanding loan quality and continued slow progress in lending conditions.

Frisco: District banking contacts reported that loan demand was up compared with the prior reporting period. Demand for commercial and industrial loans rose perceptibly, as businesses in a variety of sectors reportedly showed increased interest in expansionary capital spending. Demand for consumer credit also grew slightly. The reports indicated that competition among lenders to extend credit to well-qualified small and medium-sized businesses has intensified, placing downward pressure on rates and fees. Overall, however, lending standards remained somewhat restrictive for most types of consumer and business loans. Venture capital financing activity and investor interest continued to grow, particularly for companies focused on Internet and wireless applications and digital media.


Some thoughts, in no order of importance

-- Mortgage lending is at best very slow, although several districts reported an increase in home equity lines of credit

-- No district reported major drops in lending standards. In fact, I would argue that an overall increase in lending standards relative to the previous 10 years is a big factor in the slower loan growth.

-- The general tenor of lending activity was at best low increases, while several districts reported decreases

Let's look at total loans across the US, courtesy of the St. Louis Fed:


Total real estate loans are also decreasing


(remember, the large spike is due to a recalibration of the statistic, not to an actual increase in loans). Total consumer loans are decreasing, and have been throughout the expansion.


Total commercial and industrial loans have bottomed, but haven't really increased; they're still bouncing at a low level relative to previous activity.

The above chart indicates that credit is barely expanding, and that's only because of C and I loans. Consumer and real estate loans are still dropping. Part of this is due to tougher new lending standards, but some is also due to consumers cutting back on loans and businesses shying away from new indebtedness because of concerns about the future.

Thursday Oil Market Analysis

Last week, I wrote the following about the oil market:

Going forward, I would expect prices to continue moving lower. However, I would view this as a temporary development. The lower MACD print, strong downward candles and increased volume on the latest sell-off indicate profit taking is in order.

While there are signs of a slowdown, no one (except those who can't help themselves) is calling for a recession. Instead, analysts are noting that high oil prices will lead to lower growth.


In addition we are moving into the summer driving season, which historically leads to higher demand and therefore higher prices.


My thought process was essentially prices were in the middle of a correction, largely caused by the phrase, "the only cure for higher oil prices is high oil prices;" high oil prices strangle economic growth, lowering demand for oil, hence lowering oil prices. However, there is clear support in the market. Consider the 6 month chart:


There are two important trend lines on this chart. The first starts at a low in late November and the second starts at a low in late February. While the shorter one is a bit steeper, it is not parabolic, so it could conceivably hold for some time. The 50 day EMA is moving higher, indicating a rising, longer-term trend, but the shorter EMAs are less steep, indicating a pause. However, the EMAs are still bullishly aligned.

The declining MACD is concerning for the bulls, as the indicator has printed lower tops for higher price action, which is usually a sign of a stalling market.

In addition, consider this shorter chart:


Over the last few weeks, with the exception of today, the price action has been weak. There were two strong down bars, three weaker moves higher, another strong downward bar and then a weak up bar. Today's action is the only strong bar over the last 8 trading sessions.

The overall feeling I can't shake is that with gas at $3.84/gallon on average, traders are incredibly sensitive to the effect of higher oil prices on the expansion. This is probably what led Goldman to issue its sell recommendation on commodities last week. In short, I keep thinking we already have a top built into the market caused by economic fundamentals. On that order, consider this chart from the St. Louis FRED:


The chart compares Brent Crude and regular gas prices on a scale of 100. The last time gas prices were at or near this level was the beginning of the last recession. While we probably still have some upside room for gas prices before we hit recession inducting levels, we're a lot closer than we want to be at this point. In short, I have to wonder how much upside room oil prices have before we hit a slowdown, and hence have traders selling long positions.