Wednesday, March 6, 2019

This Friday, watch out for an outright decline in temporary employment


 - by New Deal democrat

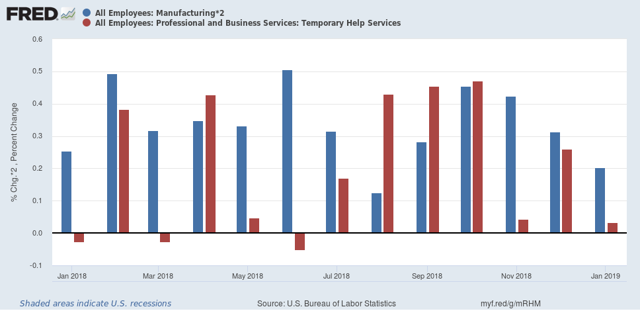
Almost a month ago I flagged the decelerating staffing index, and showed how it corresponded with the leading sector of temporary jobs in the monthly jobs report:
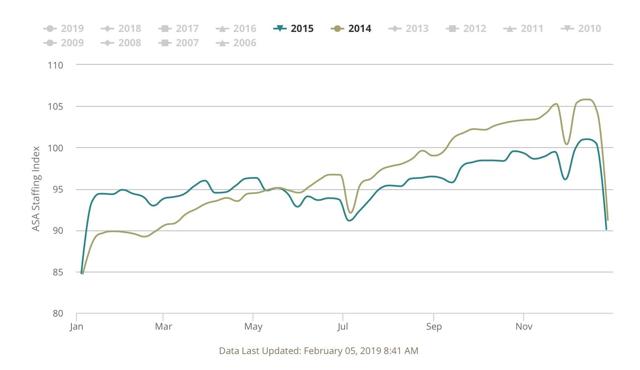
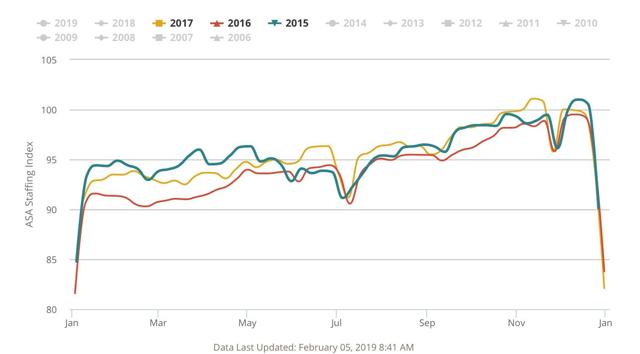
the Staffing Index isn’t seasonally adjusted, [so] you really have to compare each on a YoY basis. And while the two don’t turn positive or negative at the same time or for the same duration, they do correlate well on YoY direction; i.e., acceleration or deceleration in the YoY comparison.
I concluded:
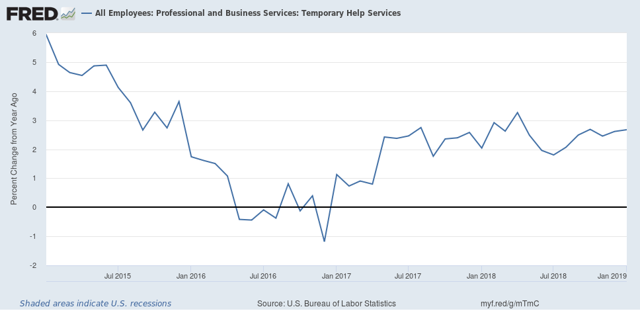
[This deceleration] makes me think that the deceleration of temp jobs in the monthly report for the last three months, as shown in the final graph below:
hasn’t just been noise, but - while still positive - is demonstrative of real weakness. 
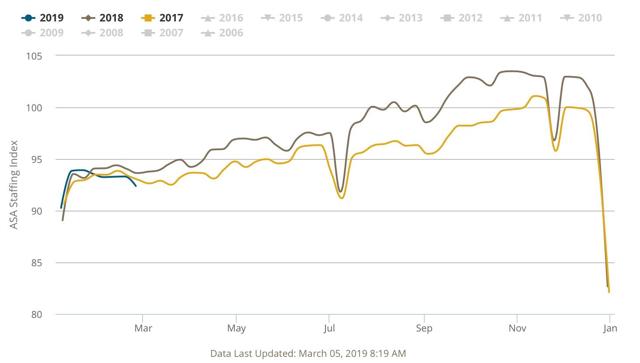
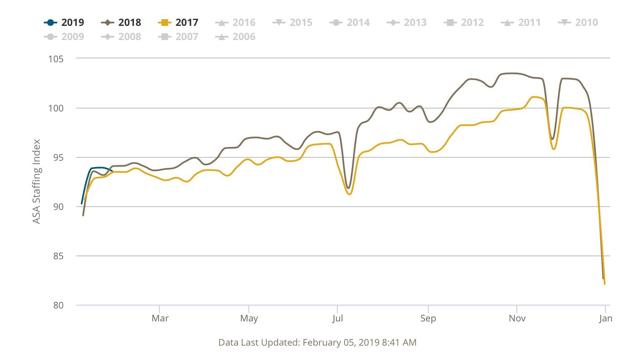
Since then, beginning three weeks ago, the Staffing Index has gone negative. As of this week, it is down over -1% from a year ago, and even negative compared with two years ago:

As a result, I expect at minimum that this Friday’s employment report will show that temporary help jobs have also decelerated YoY. Since in  last February 12,000 temp jobs were added, that isn’t much of a constraint.

But the average for the last three months has been declined to +3,000 per month. With the Staffing Index having continued to roll over since the beginning of this year, that is a more realistic ceiling on what I am expecting on Friday, and there’s probably a 50/50 chance of an outright decline will be reported for February.
The bottom line is that almost all of the other economic data has been validating the “slowdown” forecast I made beginning last summer, and I expect employment to follow — and temporary jobs will probably lead the way.

Tuesday, March 5, 2019

February services index strong; new home sales in line with bottoming scenario


 - by New Deal democrat

Just a quick note on this morning’s economic data.

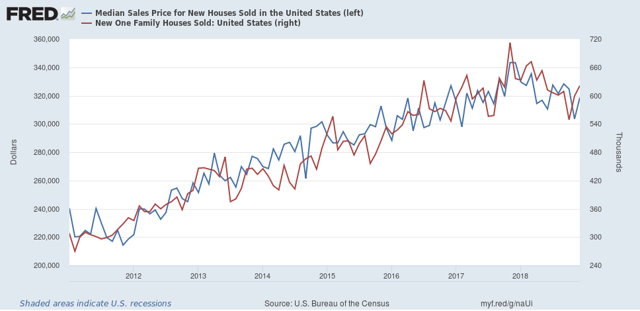
First, new home sales improved in December from October and November’s relatively dismal pace (blue in the graph below). We are back to the levels of last summer, but still down from one year ago (including as the more stable, less noisy 3-month rolling average)(red shows prices, which have been moving in tandem with sales during this expansion): 


This is of a piece with yesterday’s December permits and starts data. Both metrics are down, but look likely to bottom within a few months in response to lower long term interest rates.

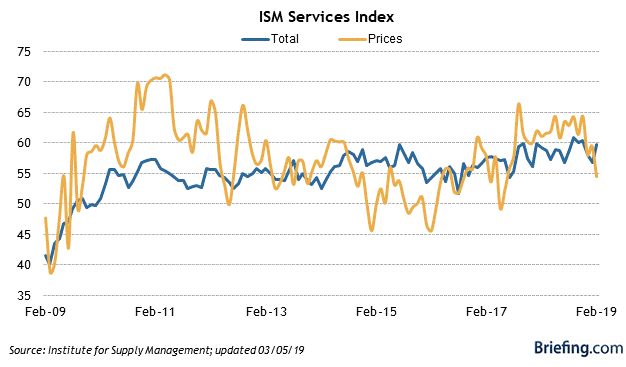
Second, the ISM services, or non-manufacturing, index came in at a very good 59.7. Here is that metric for this expansion (via Briefing.com):


As you can see, this metric is doing very well.

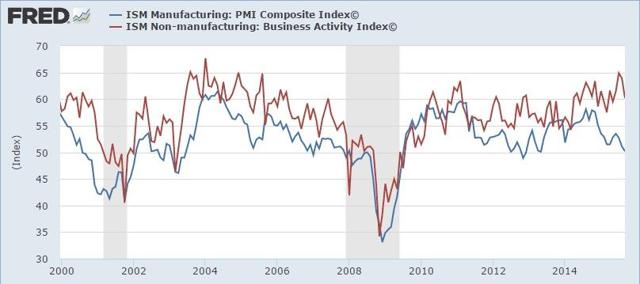
ISM doesn’t let FRED publish their data any more, but fortunately there are long-term graphs since the beginning of the series 20 years ago that are still around. Here’s one from 5 years ago, comparing services with manufacturing:


The important thing here is that, unlike the manufacturing index, which is a leading indicator, services are a coincident, and possibly even lagging indicator (look at 2008). If and when ISM services slips to 50, that will probably mean that a recession is imminent or has already started.  But no worries for the moment!

Monday, March 4, 2019

Residential construction declines in December, but looks to be bottoming


 - by New Deal democrat

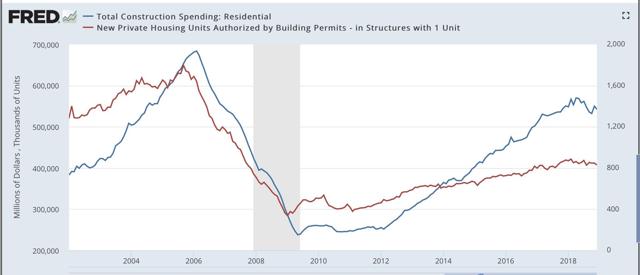
Residential construction spending lags sales, permits, and starts. But it still leads the economy overall, and it is a much smoother data series, with little noise. It is almost all signal, and so it is an important confirmation of the more leading data.

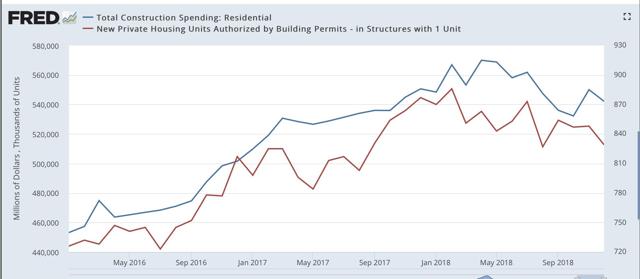
In December, residential construction spending did decline vs. November and also vs. one year ago, but it was higher than September’s and October’s numbers. 

Let’s go to the graphs. Here’s the absolute level of residential construction spending (blue) vs. single family permits (red), first a long term look, and then focusing on the last several years.  As usual, I choose single family permits because they are the least noisy of all the more leading data:


That permits lead construction is easy to see. In the second graph, the declining trend in 2018 with construction following permits with a brief lag is also apparent.

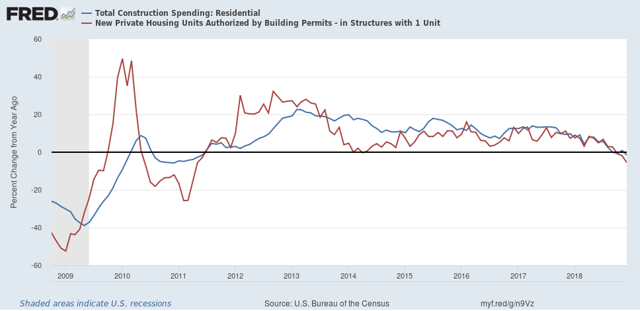
Here is the same data as YoY% changes since the bottom in 2009:


Both series are down YoY.

That neither series has made new lows in several months is encouraging. Although I think there is a little further to go in the next few months, Unless the Fed surprises nearly everybody and raises rates again, I strongly suspect that the bottoming process in new home building is ongoing. 

December housing summary at Seeking Alpha


 - by New Deal democrat

I haven’t done a comprehensive update on housing in a few months, in large part because of the lapse in data during the government shutdown.

With last week’s report on December housing permits and starts, plus several house price indexes, I put up an update over at Seeking Alpha .

As usual, clicking over and reading should be educational for you, and helps me with a bit of $$$.

Also, we’ll get December construction spending later this morning, and new home sales tomorrow. I’ll update further as warranted once these (especially spending) are reported.

Sunday, March 3, 2019

Climate change is the detonation of the Population Bomb


 - by New Deal democrat

You know the drill ... it’s Sunday so I speak my mind on things non-economic.....

Way back in the days of the dinosaurs when I was a young teen, I concluded that there were really only two extinction level threats to humanity:
1. Nuclear war 
2. Overpopulation (a/k/a “The Population Bomb”)

As to the first, fortunately we have gone over 70 years since Hiroshima and Nagasaki. But I find it difficult to conclude that unless something changes, over a long enough time horizon, like 500 years, a nuclear war won’t happen. Just consider the likes of Donald Trump and Kim Jung Un with their fingers on the button, and wonder how long till someone like them makes a fatal mistake.

As to the second, we have the example of Easter Island, where the last tree is cut down, and the last food-source is exhausted. Humanity disappears.  All you need to consider is whether the Easter Island experience can be scaled up to the entire planet.

I have thought a lot recently about climate change, and increasingly think it is ultimately a manifestation of the Population Bomb.

I am currently reading historian Yuval Noah Harari‘s “Sapiens: a Brief History of Humankind.”  I’m not sure if the book as a whole is very recommendable. Much of it comes across as broad-brush sociological speculation, some of it provocative (e.g., money is the most universally accepted part of human culture. One culture may hate another, but will universally be willing to trade in their accepted coin or currency.), and some of it flimsy (e.g., why patriarchies are much more common than matriarchies). Perhaps the most interesting observation is that what sets humans apart from other social animals is our willingness to cooperate on both an individual and massive scales with complete strangers. A look at human population growth shows just how successful that has been.

The first modern human, our “Eve,” lived about 200,000 years ago. Probably the genetic mutation that she spawned was the dropping of the voice box further into the throat, enabling speech (as opposed to, e.g., grunts or gestures). So magical was the ability to speak that those endowed with it - the new human species - expanded through Africa and then ultimately out of it to Europe and Asia about 70,000 years ago.

What does that have to do with climate change and overpopulation? According to Harari, along the way, something alarming happened. 
 - About 45,000 years ago, humans arrived in Australia. Shortly thereafter, almost all of the large predator and prey species went extinct.
 - About 16,000 years ago, humans arrived in the Americas. Shortly thereafter, almost all of the large predator and prey species went extinct.
 - About 800 years ago, humans arrived in New Zealand. Within 200 years,  most of the large predator and prey species were extinct.

(As an aside, it’s possible that humans had a partner in crime in these extinctions.  Below is a still of the last frame of the move “Alpha,” a fictional account of the first wolf that partnered with a human:
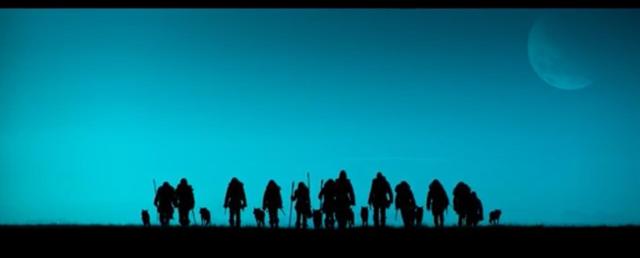

I don’t know about you, but if I were a prey animal and I saw a combined human-wolf-pack like that coming at me, I would be thinking, “Oh, sh#t! We are SO dead!” The evidence is that wolves were domesticated long before humans settled into agricultural communities, so almost certainly hunting as a team had something to do  with it.)

But that’s not the point. The widespread extinctions of “megafauna” that coincided with the arrival of modern humans on the scene is just one example of the global impact of the “anthropocene” epoch.

Here is a graph of the entire world population over the past 7000 years:
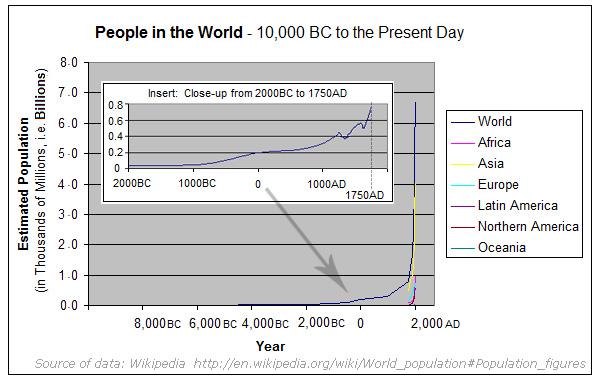
 

But this is a case where a chart might is even more devastating, as in the below, which based on figures cited by Harari and others, is what human population growth has looked like ever since that first “Eve” 200,000 years ago:

Years ago.     World population   doubling rate
200,000                      1
 75,000              80,000
 12,000         8,000,000  ~10,000 years
   3,000       80,000,000     ~2800 years
      200     800,000,000       ~850 years
Present  8,000,000,000         ~60 years

Not only has the human population exploded in raw terms, but its rate of growth has actually been accelerating ever since the “agricultural revolution” that began roughly 12,000 years ago.

Meanwhile, the last megafauna on the planet, like Siberian Tigers and African Elephants, teeters on the edge of extinction. Two thousand years ago megafauna that we associate with sub-Saharan Africa was also present along the temperate region along the Mediterranean coast. It disappeared via the Roman Coliseum. A little over 100 years ago, partly as an effort to exterminate the Indian tribes, American buffalo were hunted down to about 400. Now we are busy driving even ocean life, for example cod and lobster, towards extinction.

As these resources decline, their cost increases dramatically. Two hundred years ago lobster was junk food. Caspian Sea caviar costs a year’s salary. And need we talk about the concept of “peak oil”?

Just in the last year, evidence was adduced that possibly the death of up to 90% of Native North and South American tribes due to diseases introduced from Europe after 1492 caused so much re-forestation that it contributed to the “Little Ice Age.”

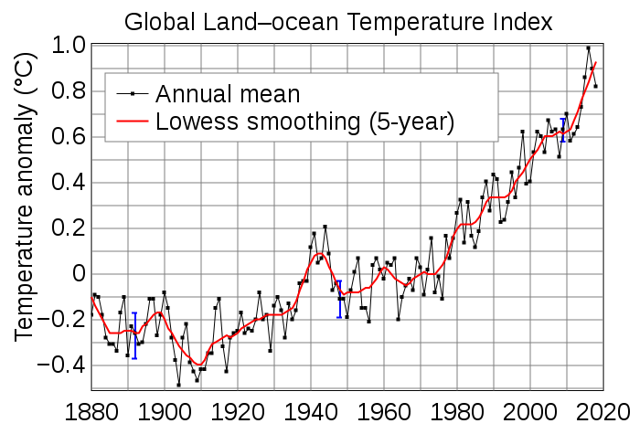
And so now we come to global warming. Here’s a graph of average ocean temperatures in the past 150 years:


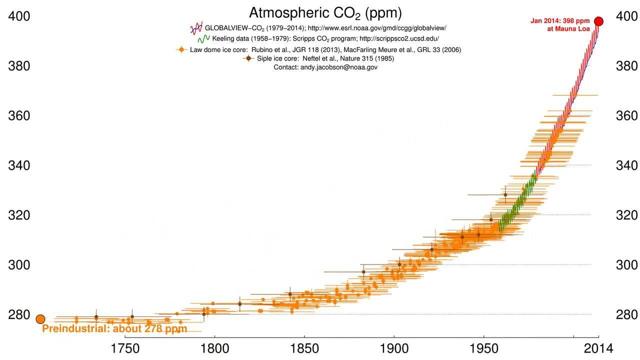
And here is carbon dioxide levels in the atmosphere for the past 300 years:


Does anyone seriously think that the half measures and quarter measures being contemplated — and fiercely opposed — are going to make a meaningful dent in the trend in those two graphs?

The simple fact is, humanity has been slowly — but at an accelerating rate — turning the entire planet into Easter Island. I strongly suspect that we have already crossed the threshold beyond the Earth’s long term carrying capacity for the human race. The planet could handle 8 million, 80 million, and even 800 million humans without widespread damage. There is evidence everywhere in the animal, ocean, and atmospheric environment that it can’t handle 8 billion humans for long.

Want to defeat climate change? A global one-child policy for two generations, bringing total human population down to where it was in about 1950 might be enough. It almost certainly will never happen.

But if human population has already exceeded the carrying capacity of the planet, humanity will get there, willingly or not.        
Saturday, March 2, 2019

Weekly Indicators for February 25 - March 1 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

Last year the most significant developments were in the long leading indicators. Now that is translating into the short leading indicators.

As always, clicking and reading not only should be educational for you, but rewards me a little bit for my efforts.

Friday, March 1, 2019

Manufacturing holds on in February


 - by New Deal democrat

The theme for most reports remains that the government shutdown in December and January, plus a 30 year record cold snap for a week in January, put a real dent in the economy. That certainly was the message of December personal spending and December and January personal spending this morning.

But it looks like there was no significant damage to manufacturing. This week three regional Fed banks reported February manufacturing in their region, followed by the Chicago PMI, and finally ISM manufacturing this morning.

At the end of January, the average new orders reading of the five regional Feds was +5. After much storm and drang, notably a big downdraft in the Kansas City region, but an even bigger updraft in Richmond, the average for February increased +1 to 6.

One regional Fed that does not report is Chicago, but the Chicago PMI’s new orders index, which has been running hotter than the other regional reports for months, also bounced back strongly in February, from 53.2 to 68.4 (which is still not quite as positive as it was for a number of months earlier last year). Subtracting 50 to make this compatible with the Fed indexes gives us an increase in the average from +5 in January to +10 in February.

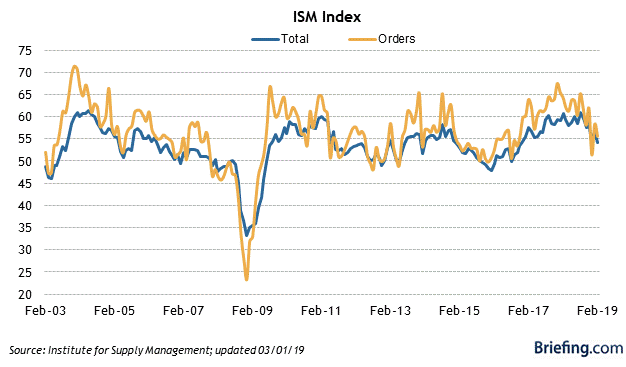
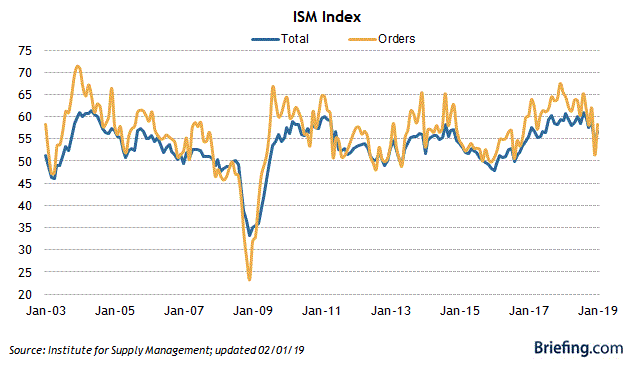
Finally, this morning the ISM new orders index for February declined to 55.5 from January’s 58.2 reading. The total index declined from 56.6 to 54.2, the lowest in nearly two years (h/t Briefing.com):


This of course is still well into positive territory, and in line with most of this expansion. It is also in line with the average of the regional Fed reports. Chicago looks like the outlier.

The bottom line remains that manufacturing is decelerating from its torrid pace last summer, but is still expanding decently. Because I anticipate further slowing in the economy over the next 6 to 9 months, I am still expecting further deceleration in manufacturing. Whether it goes beyond that into outright contraction is very much an open question.

Thursday, February 28, 2019

Initial claims not at cautionary levels yet


 - by New Deal democrat

Initial jobless claims are an important short leading indicator, typically turning up 3-9 months before a recession. A problem is the necessity of filtering out signal from noise.There are two ways I measure claims in order to do so: (1) how much has the less noisy four week average risen from its low? And (2) have initial claims, averaged monthly, turned higher YoY?

Let’s start with the first measure. A 10% increase off of an interim low in claims is not unusual, and has happened every year or two for the entire 50+ year period that records have been kept. By the time they are up 15% from their bottom, not only is it almost always a signal of recession, but frequently the recession is imminent.
To distill signal and still give reasonable warning, the caution signal I employ is a rise of over 12% from a low. Measuring so, we see that initial claims as of this week are up about +11.5% off their lows:
Note that I am discounting the previous few weeks because they were distorted by layoffs due to the government shutdown. The four week average now does not appear to have any special factors.
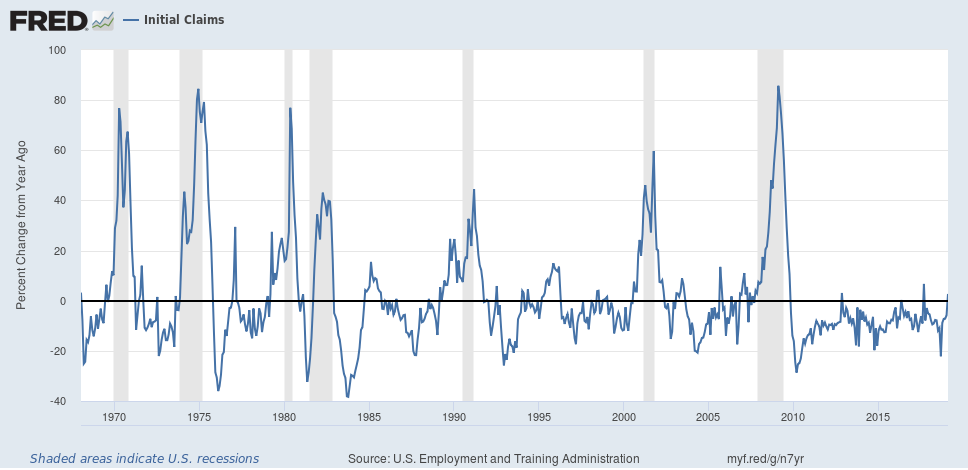
Next, here is the long view of initial claims YoY measured monthly:
In any given expansion, there is usually at least one month where claims are higher YoY. But if that happens for two months in a row, more often than not it has signaled that a recession is approaching.
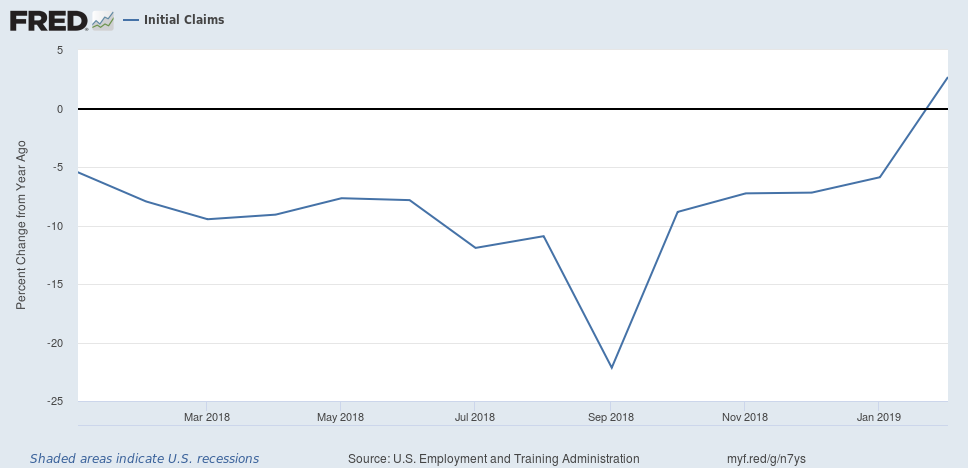
Here is what all of 2018 plus the first two months of 2019 look like:
Note that the big distortion in claims happened at the end of January. Even so, on average January 2019 was lower than January 2018. But February saw more initial claims being filed on average than one year ago. Still, we won’t have a caution signal unless March also sees higher claims than March of last year.

The bottom line is that, while initial claims are close to the levels at which they would give a warning, they aren’t quite there at this point.

Q4 GDP: mixed signals for the future (UPDATED with graphs)


 - by New Deal democrat

I didn’t post anything yesterday, so I’ll make up for it with two posts today.

This morning we finally got the very delayed first look at Q4 GDP. As per my usual practice, I am less interested in what happened in the rear view mirror, which was an annualized gain of +2.6%, than what the number tells us about what lies ahead.

The two forward-looking components of GDP are (1) private fixed residential investment, and (2) corporate profits. Both of these are long leading indicators, I.e., giving us an idea about where the overall economy will be a year or more out from here.

In that regard, the news was mixed.

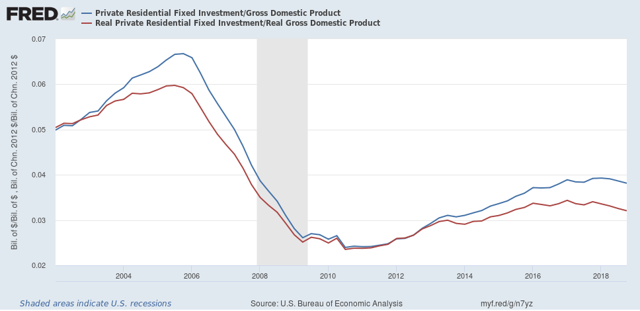
Private residential fixed investment declined -0.9% q/q. This is in keeping with the downturn in housing construction that we have seen in the monthly data. Note that residential investment as a share of GDP declined in both nominal (blue) and real (red) terms:


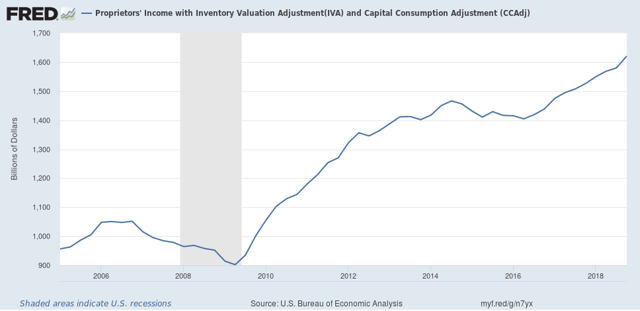
Meanwhile, corporate profits as is usual won’t be reported until the final revision in GDP one month from now, but proprietors’ income rose, was. While it does not always move in the same direction as corporate profits, and sometimes lags, it a good placeholder.  Here the news was positive, as proprietors’ income rose +2.6% q/q:


I’ll supplement the above with graphs later. (UPDATE: DONE)

 But the takeaway is, that in the rear view mirror, there was no recession in Q4. While one important leading sector of the economy, housing, continued to deteriorate, the producer side of the economy in the form of proprietors’ income, kept humming along. While enough long leading indicators of the economy did decline in 2018 to continue to justify being on “recession watch” for later in this year, and particularly Q4, there is no sign of deterioration on the producer side of the economy, so if a recession does develop, it will likely be centered on consumers and secondarily on manufacturing.

Tuesday, February 26, 2019

December housing permits and starts mixed, support slowdown scenario


 - by New Deal democrat

This morning we finally got December housing permits and starts. Remember that starts are more volatile than permits, and single family permits are the least volatile of all.
  
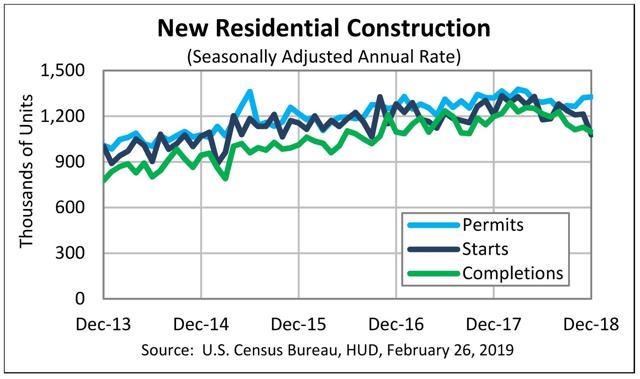
Here’s what the overall data looks like:

While starts and completions laid an egg, permits actually went up a little bit.
In particular, for housing to be outright recessionary, I would want to see single family housing permits down -10% from peak at minimum. This morning’s data has them down only about -6.5% off peak, just slightly above their worst showing of 2018.
In other words, this morning’s report says slowdown rather than recession to me.
On a side note, the talking heads on CNBC were bemoaning that lower mortgage rates hadn’t led to an substantial increase in housing starts. But as I’ve pointed out many times, permits and starts follow interest rates with about a 3 to 6 month lag. In other words, consistent with a bottom in housing construction this spring.
I’ll have more to say probably tomorrow at Seeking Alpha. When the post goes up, I’ll link to it here. 

Monday, February 25, 2019

At last! Missing long leading metrics and manufacturing in the spotlight this week


 - by New Deal democrat

This week manufacturing and some important data long delayed by the government shutdown will be in the spotlight.

First, manufacturing: as the below graph of ISM manufacturing and new orders shows, in the last 8 months, manufacturing has slowed from white hot expansion to just weakly positive:


As of last Friday, the rolling average for new orders in the five Fed regional indexes was just +1 above completely stalled — it had been as high as +28 in spring 2018!

Between today and Thursday, three remaining Fed regions — Richmond, Kansas City, and Dallas— will report their February manufacturing indexes. Also on Thursday, the Chicago PMI gets published. That one has been the most positive of any region for the past year.  Finally, on Friday ISM publishes its national February manufacturing report.

It’s possible that by the end of this week we will have evidence that manufacturing is in outright contraction. We’ll see.

Meanwhile, data on three long leading indicators — building permits, residential investment, and proprietors’ income — that have been delayed by as long as two months, finally get reported, on Tuesday (permits for December) and Thursday (as part of the Q4 GDP report).

A couple of weeks ago I went ahead and made a “preliminary” forecast for the second half of 2019, using substitutes for this data, that included me going on “Recession Watch” for Q4 of this year. The missing data, once reported, could either consolidate or alleviate that forecast.

Saturday, February 23, 2019

Weekly Indicators for February 18 - 22 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

The short leading indicators have sunk to a level that is consistent with an oncoming recession in the next 3 - 8 months.  But the recent government shutdown may still be skewing some of the data.

As always, not only is clicking and reading hopefully informative for you, but it also helps reward me a little bit for the effort I put in to this work.

Friday, February 22, 2019

Housing may bottom this spring


 - by New Deal democrat

Despite yesterday’s poor existing home sales report, which was the worst in over three years, the bottom in housing may be near.

This post is up at Seeking Alpha. As always, reading the post should be helpful to you, and renumerates me just a bit for my efforts.

Thursday, February 21, 2019

Industrial transportation stalls out


 - by New Deal democrat

The two main forms of transporting goods, rail and trucking, have both gone negative YoY, and on average over the last 3+ months are only slightly better than zero. This both has implications for the broader economy, and confirms some other poor data.

This post is up at Seeking Alpha.

Wednesday, February 20, 2019

100 years of industrial production


 - by New Deal democrat

This is a post that can literally be written only once in 100 years!

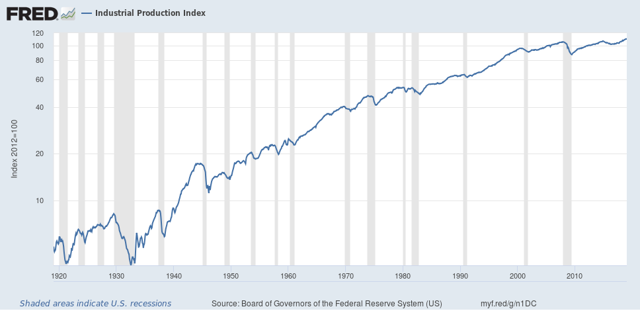
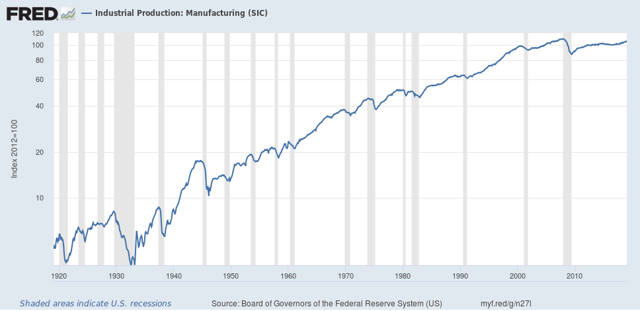
Because as of last Friday, it has been exactly 100 years since the first publication of industrial production by the Fed in January 1919. So this is a good time to take a sweeping historical look at production in the United States.

The first graph below is the entire 100 year history, on log scale so that equal percentage changes in each time period are calibrated equally:
A few features stand out: the Great Depression, the World War 2 boom, and two downshifts in the long term trend: first in the 1970s-1999, and second from 1999 to the present.

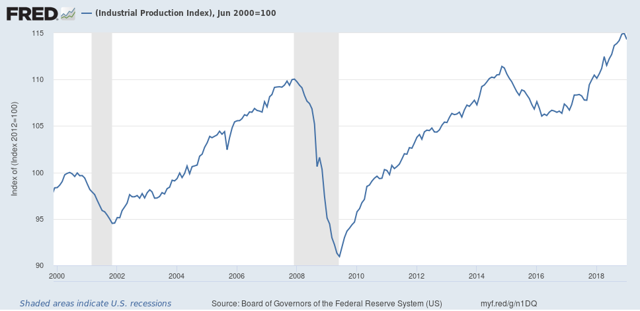
In fact, the past 20 years have been the slowest secular period since publication of industrial production started 100 years ago. As shown in the below graph, normed to 100 in June 1999, production has only grown 15% in the 20 years since. It grew just under 10% during the 2000s expansion, and only about 5% in the last 11 years:

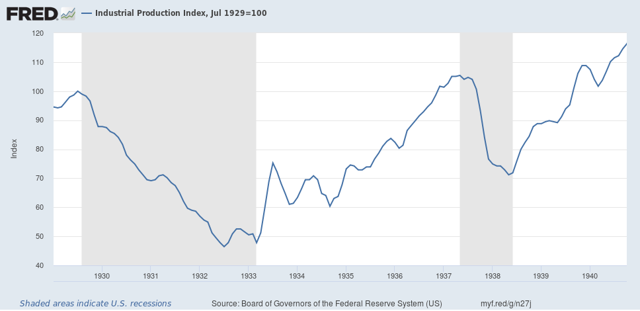
The worst previous period was the 1929-37 portion of the Great Depression, but even there production grew 6% by the end of that 8 year period, and exceed a 15% gain from 1929 by late 1940, 11 years later:

The situation is even worse when we subtract mining and utilities, and focus just on manufacturing. Here’s the 100 year log scale growth in that sector:

Note that growth has for all intents and purposes stopped since 1999.

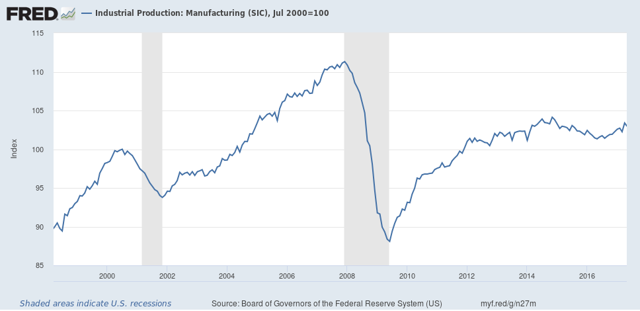
Again focusing just on the last 20 years, we see that manufacturing production grew just 11% during the 2000s expansion, and even now 11 years later, has still not equaled the 2007 peak:
Total growth over the last 20 years in manufacturing has been just 3.4%.

Taking the long historical view shows the relative — and in the last decade, absolute — decline of the US as a manufacturing power. And it also puts paid to the notion that, at least in the last 20 years, the decline in manufacturing employment is mainly about productivity and mechanization. If it woeren’t for the rebirth of “Saudi America” in the energy sector over the last 10 years, industrial production growth in the US would have completely stopped.

Tuesday, February 19, 2019

Wages continued to improve through January


 - by New Deal democrat

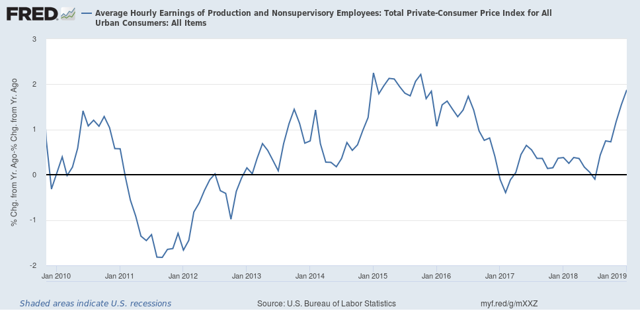
One item I didn’t get around to in the last couple of weeks is how wages performed as of January’s jobs report. And the basic answer is: pretty good!

The first graph below shows real, inflation adjusted average wage gains for non-managerial workers measured YoY:
As of January they were up +1.9%. This is the best showing except for a few months in 2015.
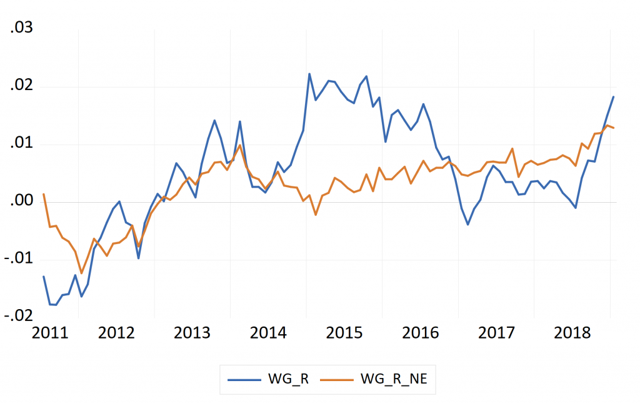
As Jared Bernstein has shown, the “real” gains in wages have a lot to do with the price of gas (blue in the graph below). But in the last two months they have risen the most in the last 8 years in real terms ex-energy:
So average workers are finally making some real headway.

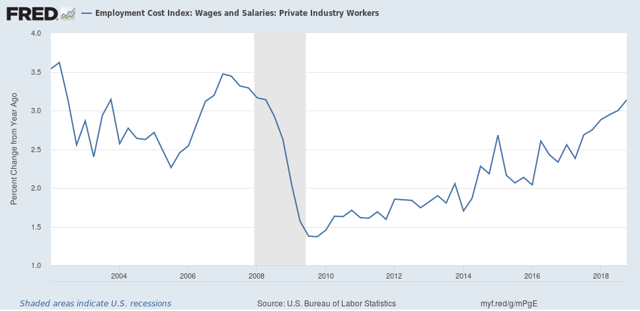
By the way, this also shows up in the Q4 2018 Employment Cost Index that was released three weeks ago:

The ECI measures *median* wages, i.e., the 50th percentile level, and so does away with the “Bill Gates enters a bar” problem. At +3.1% YoY, this is the best showing since late 2006-early 2008.

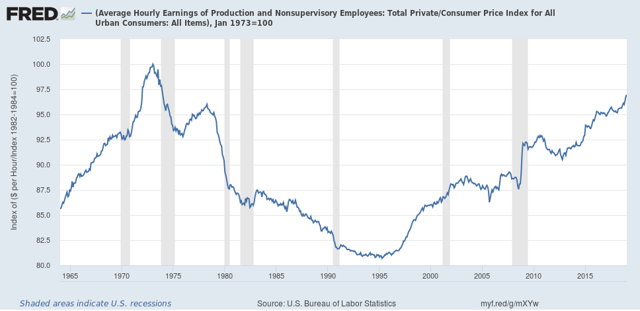
Returning to real inflation adjusted average wages, they improved again and are now only 3% below their 1973 peak:

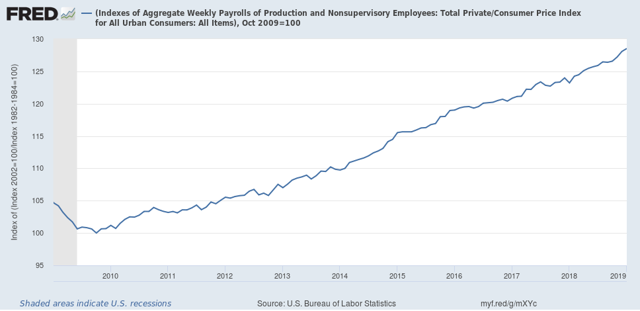
Finally, total wage growth for non-managerial workers since the bottom in October 2009 is now up +28.5%:

Total wage growth from this entire expansion has only been exceeded by the 1960s and 1990s expansion. The bad news, of course, is that it took 9 years to get here.

Monday, February 18, 2019

It’s Presidents Day, and we’re still basically flying blind on the eoncomy


 - by New Deal democrat

Not only are the markets closed today for President’s Day, but this entire week is about the emptiest I can ever recall for economic data. Literally the only data of note is going to be released on Thursday, and except for weekly jobless claims, even that is not what I would generally consider first-order metrics.

Even worse, we are still basically flying blind due to the government shutdown. The only data of note that had been on hiatus, and has been updated since it ended was last week’s retail sales for December. And that report was jarring enough to justify worrying that not only did the shutdown make us economically blind, but it itself may have further weakened an already weakening economy. So we may be in for some more jarring surprises when December housing starts and permits, December income and spending, and Q4 GDP finally get released next week.

There are a couple of series I’ve been meaning to update, so maybe I’ll get around to them. But, don’t be surprised if I don’t post any material for a day or two, or post a brief note on a political topic.

Saturday, February 16, 2019

Weekly Indicators for February 11 - 15 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

There was some widespread deterioration among both the short leading and coincident weekly data, as well as the monthly data.

This is similar to what happened during the 2011 “debt ceiling debacle,” which makes me think that the government shutdown had a more pronounced (but hopefully transient) impact on the economy.

Friday, February 15, 2019

Industrial production face-plants, but hold the DOOOM for now


 - by New Deal democrat

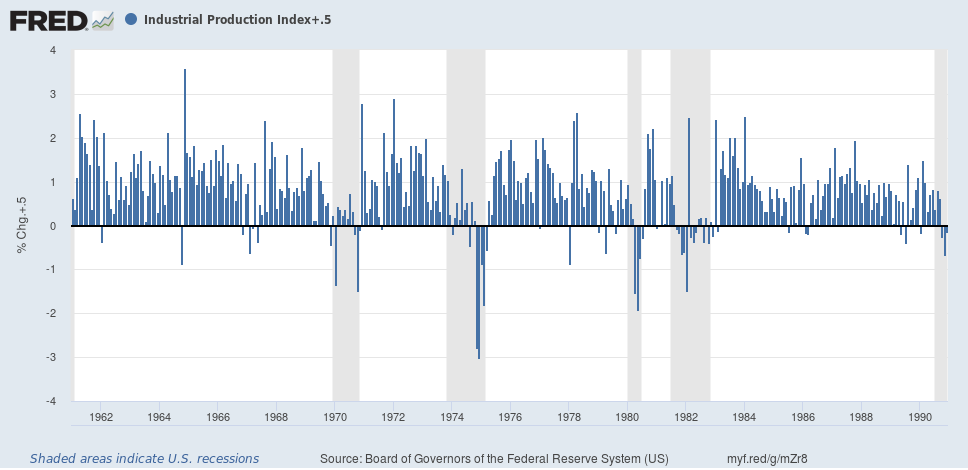
For the second day in a row, a major piece of economic data face-planted. Industrial production for the month of January declined -0.6%. Worse, almost all of the decline was in manufacturing.
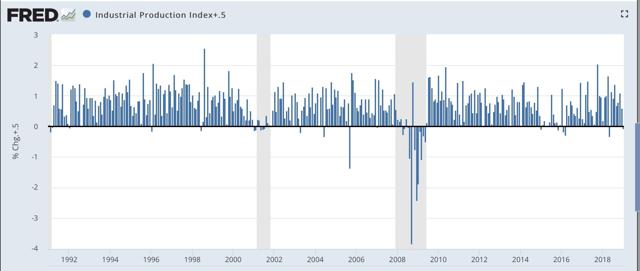
This kind of decline is most consistent with the onset of a recession, or at very least a significant slowdown, as shown in these two long-term graphs covering the last 50+ years, which have been normed so that only a monthly decline in excess of -0.5% shows as negative:
1961-82
1982- present
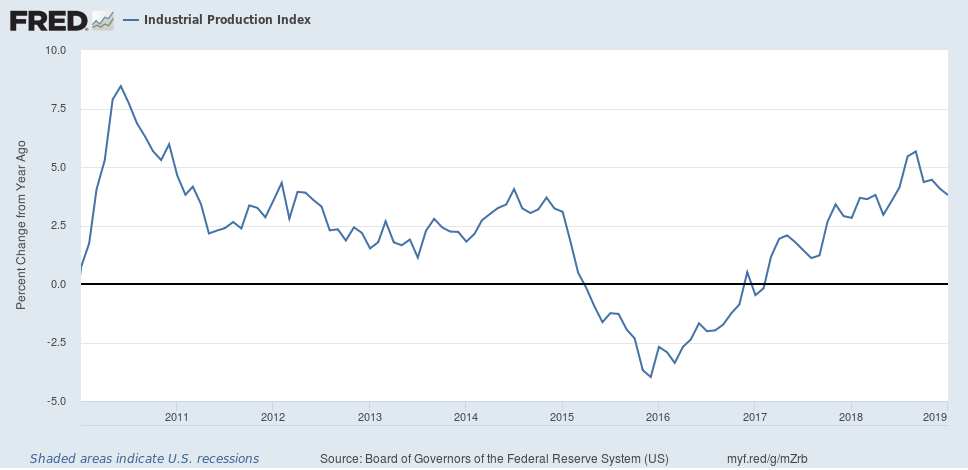
Zooming in on this expansion, the YoY% change in industrial production, at 3.8%, while certainly backing off from its “boom” readings of half a year ago, is still in the high range of average:

While the combination of yesterday’s retail sales number for December and today’s January industrial production number are pretty awful, I recommend treating each with caution, for two reasons.
First, the government shutdown - which started in late December - may have had a bigger effect on production and consumption than earlier believed. If so, I would expect the situation to reverse in the next month or two.
Second, at least in the case of January, the worst cold snap in the last 30 years hitting the industrial heartland almost certainly had some effect on production. The typical rejoinder to this is that winter comes every year. But winter weather is particularly variable from year to year, and waxes and wanes over its three month length at differing times from year to year as well.
So: definitely not good. Definitely consistent with a slowdown at least. But we need to see all of the data caught up through February before we can really judge if it is temporary or not.
Thursday, February 14, 2019

More signs of a slowdown: initial claims and real retail sales


 - by New Deal democrat

This morning we got two negative data points. One is cause for concern; the other - not quite yet.
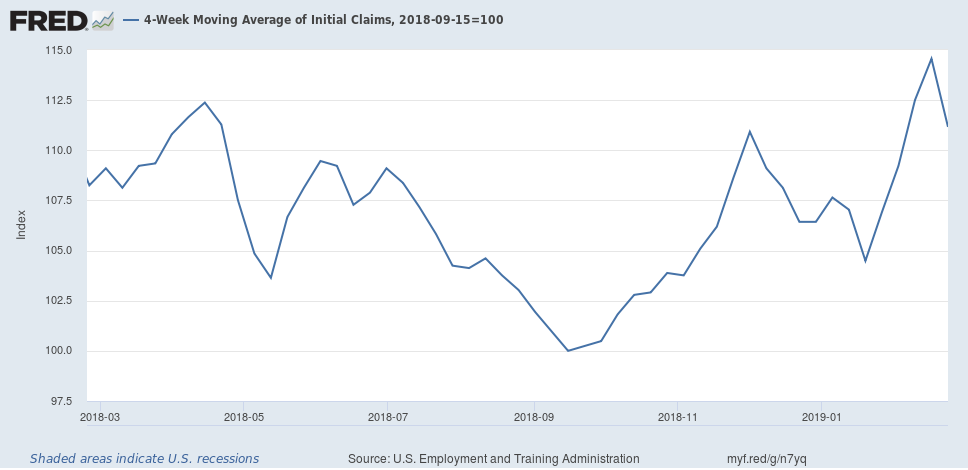
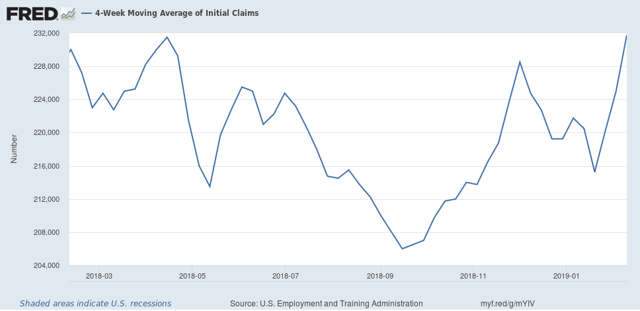
Let me start with the “not yet” first. Initial jobless claims rose 4,000 to 239,000. That means that the 4 week moving average rose to 231,750:


This means that the number is both higher YoY, and 12.5% above its 206,000 low in September.

Ordinarily that would be cause for concern. BUT, the biggest factor in the increase is the week of 253,000 claims two weeks ago, which was almost certainly due to the government shutdown. That week, in turn, was immediately preceded by the week of 200,000 claims, which was the lowest in nearly 50 years.

The bottom line is, although the trend is clearly higher since September, I would prefer to wait two more weeks for both of those outliers to pass out of the 4 week moving average before hoisting a yellow flag on jobless claims.

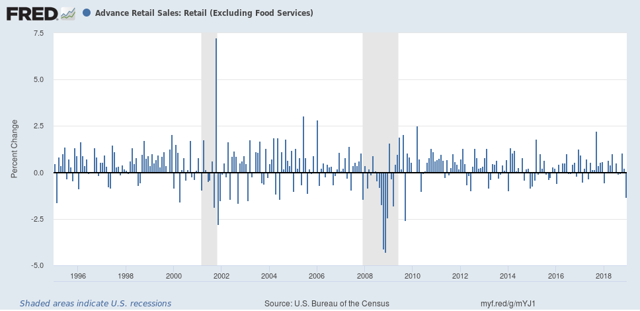
Now let me turn to the number that *is* a cause for concern now: real retail sales, which cratered by -1.2% in December. That is the worst monthly reading since just after the Great Recession, and consistent with readings in the year before both of the last two recessions, so unless this reading is revised away, it is a definite sign of a slowdown. On the other hand, in the longer view monthly readings of -1% or more aren’t that uncommon during expansions:


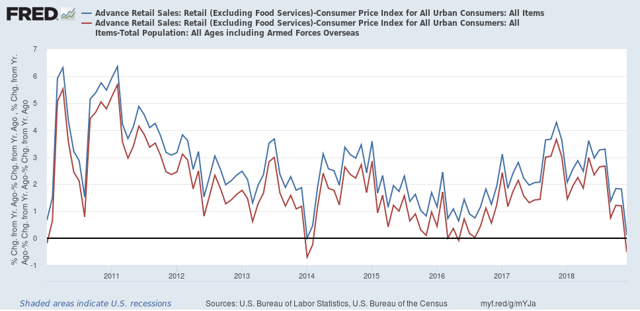
What this does do is  bring YoY real retail sales down to a meager +0.1%(!), the second lowest of the entire expansion.  Real retail sales per capita (red in the graph below) actually turned negative YoY:


In absolute terms, real retail sales per capita still made an expansion high only one month ago, so I am not ready yet to move this signal from positive to neutral yet:


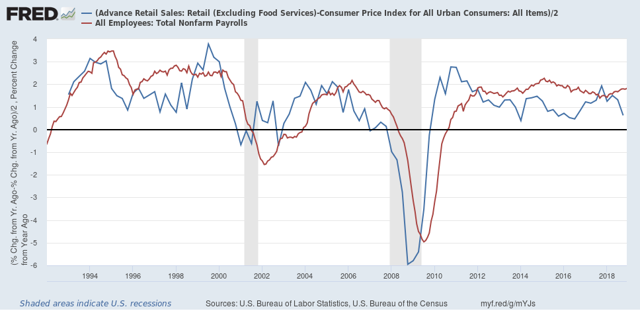
Finally, real retail sales are a good if noisy leading indicator for YoY employment, shown in red in the graph below (note: real retail sales averaged quarterly to cut down on noise):


If the poor December number isn’t revised away, or reversed by a big gain in the next months’ report, this portends a significant deceleration in jobs growth in the monthly employment reports over about the next 6 months.

Wednesday, February 13, 2019

The 2017 GOP tax scam may hurt the economy this spring


 - by New Deal democrat

It turns out that part of the GOP tax scam of 2017 might hurt the economy this year. That’s because the total decline in the amount of tax refunds going to tax filers this looks like it is going to be enough to affect consumer spending significantly this spring.


Special bonus: a few RW commenters there really don’t seem to like it!

Tuesday, February 12, 2019

December JOLTS report: mixed but with strong positive revisions


 - by New Deal democrat

The JOLTS report on labor is noteworthy and helpful because it breaks down the jobs market into a more granular look at hiring, firing, and voluntary quits. Its drawback is that the data only goes back less than 20 years, so from the point of view of looking at the economic cycle, it has to be taken with a large dose of salt. 
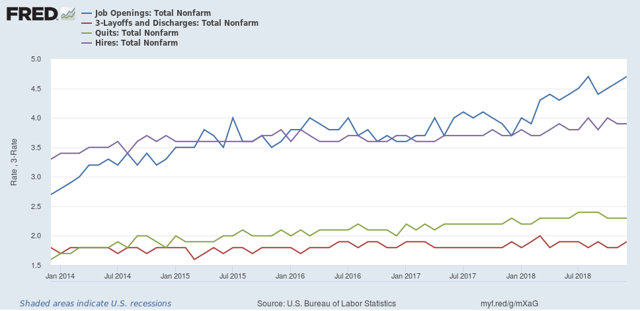
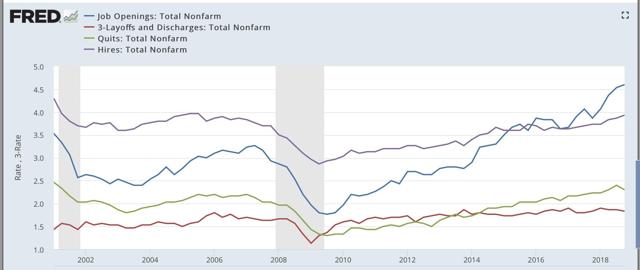
With that disclaimer out of the way, Tuesday’s JOLTS report for December was mixed, and for the second month in a row was soft relative to the strength of the overall jobs gain for that month. With the exception of one new high, the other series are off their best levels, and two continued to decline, with the good news being that there were generally positive revisions in the previous month’s data:         
  • Quits declined for the 4th month in a row, and are about 5% off peak.
  • Hires rose and are only 0.3% off their peak set two months ago.
  • Total separations declined and are off 4% from August.
  • Job openings made a new all time high.
  • Layoffs and Discharges declined (a good thing), but remain up about 10% from their recent low last March.
Let's update where the report might tell us we are in the cycle.
First, below is a graph, averaged quarterly through the fourth quarter, of the *rates* of hiring, quits, layoffs, and openings as a percentage of the labor force since the inception of the series (layoffs and discharges are inverted at the 3% level, so that higher readings show fewer layoffs than normal, and lower readings show more):
During the 2000s expansion:
  • Hires peaked first, from December 2004 through September 2005
  • Quits peaked next, in September 2005
  • Layoffs and Discharges peaked next, from October 2005 through September 2006
  • Openings peaked last, in Spril 2007
By contrast during and after the last recession:
  • Layoffs and Discharges troughed first, from January through April 2009
  • Hiring troughed next, in March and June 2009
  • Openings troughed next, in August 2009
  • Quits troughed last, in August 2009 and again in February 2010
Now here's what the four metrics look like on a monthly basis for the last five years:

As indicated above, job openings, quits, and hires all surged higher through August of this year. While openings have continued to rise, hires have gone sideways, and  quits have deteriorated.
. 
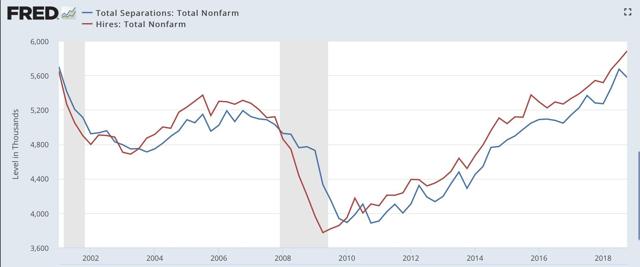
Next, here's an update to the simple metric of "hiring leads firing," (actually, "total separations"). Here's the long term relationship since 2000 through Q4 of 2018:
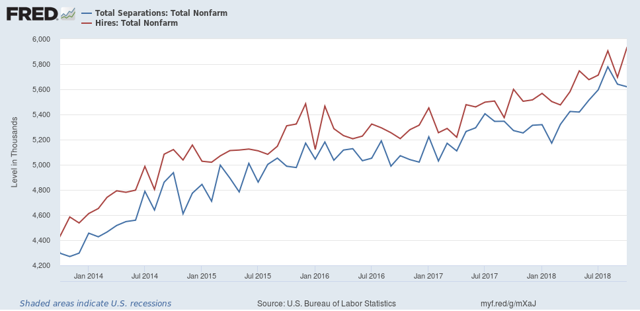
Here is the monthly update for the past fiv e years:

In the 2000s business cycle, hiring and then firing both turned down well in advance of the recession.  With the positive revisions, there is no significant downturn shown here.

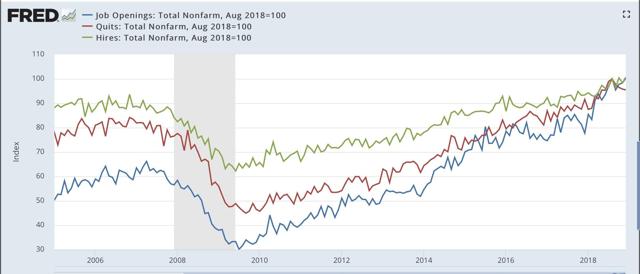
Finally, let's compare job openings with actual hires and quits. As you probably recall, I am not a fan of job openings as "hard data." They can reflect trolling for resumes, and presumably reflect a desire to hire at the wage the employer prefers. In the below graph, the *rate* of each activity is normed to 100 at its August 2018 value:


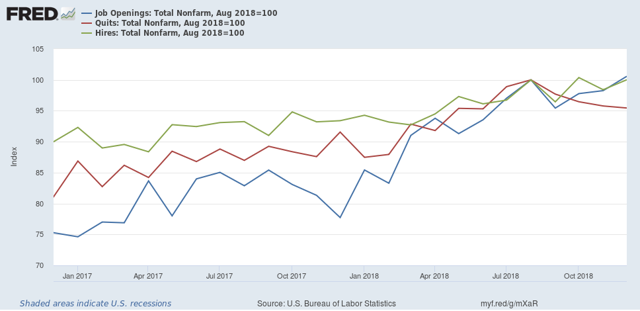
Now, here is a close-up of the last two years:
When I first presented this graph, I noted that while the rate of job openings was at an all time high, but the rate of actual hires has only just reached its normal rate during the several best years of the 2000s expansion, and was below its rate at the end of the 1990s expansion.  With the positive revisions, that story has completely changed, as all three rates are better than their best rates in the 2000s expansion.
In 2018, both hires and quits accelerated, with hiring decisively above its level from the last expansion. My take  has been that employees have reacted to the employer taboo against raising wages by quitting at high rates to seek better jobs elsewhere. Last month I wrote, “If the dam is finally breaking, we should see the hiring rate increase, and quit rate level off.”  Although similar, instead hires have leveled off, while quits have declined.
In summary, the December JOLTS report was generally strong. As I expected it to be given the headline jobs number, but had soft spots. My expectation remains  that this will start to cool down during the first six months of this year as a slowdown begins to take hold. but this won’t happen as long as the headline numbers remain so strong, as they were agiain in January. 

Monday, February 11, 2019

A decelerating Staffing Index suggests that weakening temporary jobs in the monthly employment report is not just noise


 - by New Deal democrat

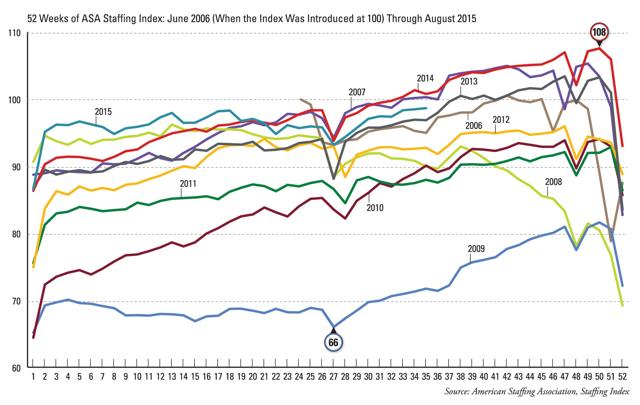
Every week I report the YoY 4 week rolling average of American Staffing Association’s Index. It’s been decelerating recently, and last week was up only +0.5% YoY. On a single week basis, though, it went negative.

Because I have written several posts in the last couple of months emphasizing the leading aspect of temporary jobs in the monthly employment report, I thought I would compare the Staffing Index against it.

Here’s what I found: since the Staffing Index isn’t seasonally adjusted, you really have to compare each on a YoY basis. And while the two don’t turn positive or negative at the same time or for the same duration, they do correlate well on YoY direction; i.e., acceleration or deceleration in the YoY comparison.

The Staffing Index only began to be published in 2004. Since then, there have only been two periods when staffing turned negative YoY: the Great Recession and the 2015-16 energy patch downturn.

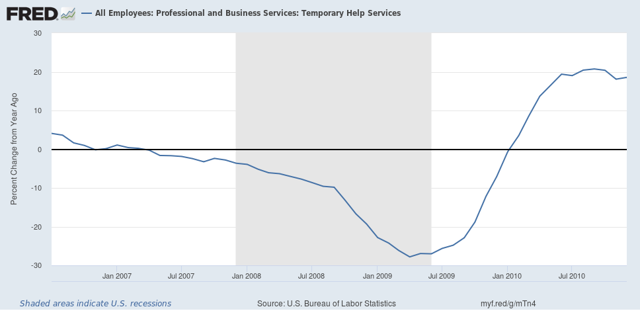
As the first two graphs below show, at the time of the Staffing Index lagged the monthly jobs report by half a year in 2007, and led it by one month at the end of 2009:


At the time of the energy patch downturn, the Index turned negative YoY in May 2015:
And continued negative until June 2017:
Meanwhile,monthly temp jobs number did not turn negative except most of the last 9 months of 2016 — although it started its rapid deceleration almost exactly when the Index went negative:

Note that decelation in the YoY number corresponded with the Staffing Index’s turning negative in 2015, and continued to improve until mid-2017.

Most recently, the YoY comparisons started to deteriorate in the Staffing Index in November, and have been barely positive so far this year. 

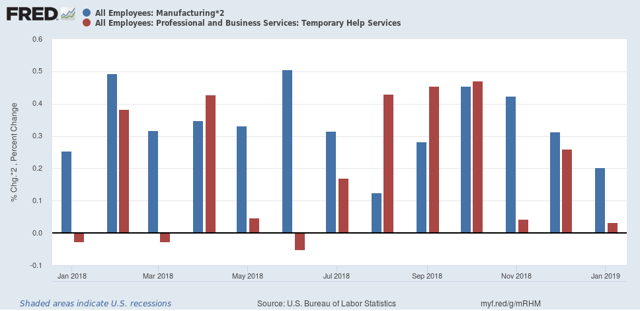
All of which makes me think that the deceleration of temp jobs in the monthly report for the last three months, as shown in the final graph below:
hasn’t just been noise, but - while still positive - is demonstrative of real weakness.