Saturday, March 21, 2015
Weekly Indicators for March 16 - 20 at XE.com
- by New Deal democrat
My Weekly Indicators post is up at XE.com.
Continuing weakness in steel production and domestic rail carloads are warning flags for a continuing slowdown in industrial production.


Friday, March 20, 2015
No, the yield curve is NOT forecasting mediocre growth. Right now it actually isn't forecasting anything
- by New Deal democrat
A 3 dimensional view of the yield curve in the treasury bond market at the New York Times has gotten a lot of play in the econoblogosphere yesterday.
Why pay attention to the yield curve, i.e., the difference in interest rates paid by short term vs. long term treasury bonds? Here's why: an inverted yield curve, I.e., short term interest rates higher than long term interest rates, is a nearly perfect warning of a recession 12 to 18 months in the future. In the last 100 years, it has had only one false positive (1966).
If we are sure we will have inflation rather than deflation in the next several years, a normally shaped yield curve is also a perfect indicator for the economy about 12 to 18 months later. In times of deflation, however, a normal yield curve is not reliable. An inverted yield curve in the presence of deflation is much to be feared. It has only happened twice in the last century – in 1928 and 2006.
The NY Times 3D graph is not animated, and not interactive. For the last 15 years, however, Stockcharts has had the aptly named interactive Dynamic Yield Curve, a tool which I have made use of frequently over the years. Here is a snapshot I made today comparing the present yield curve (lower) with the yield curve in Q1 2003, one year before the best YoY real GDP growth of the 2000s:

The yield curve is founded on a solid economic signal. Since normally you would want to be paid more interest in order to take the risk of holding on to a bond for a longer time, when the curve inverts, it means bondholders think current rates are too high compared with the longer term – they expect weakness.
One statement in the NY Times article, however, looks flat out wrong: “The yield curve is fairly flat, which is a sign that investors expect mediocre growth in the years ahead.”
Not so. Below is a graph of the spread between 10 year and six month bonds, currently at 2%. The graph then subtracts 2 so that the current spread = 0.

Prof. Menzie Chinn of Econbrowser has posted a similar graph for the 10 year vs. 3 months and 10 year vs. 2 year Treasuries:

While the spread between the 10 year and 3 month bond is in the lower half of the distribution, the spread between the 10 year and 6 month treasuries (my graph) and 10 year vs. 2 year (red in Prof. Chinn's graph) is steeper than most other times during the last 30 years.
It is also equivalent to if not steeper than almost all times between 1933 and 1954 (blue is long term government bonds, red is 3 month treasuries):

during which time the US saw the strongest growth in its entire history:

So,*NO,* the yield curve is not telling us there will be mediocre growth. Because we are presently in deflation, even though the yield curve is positive, it actually isn't forecasting anything.
Thursday, March 19, 2015
Is 2% core inflation the Fed's target, or a ceiling?
- by New Deal democrat
I really don't have much to add to what you have probably read elsewhere about the Federal Reserve's policy statement, except that it appears to me that 2% inflation isn't really being treated as a target so much as a ceiling.
Their estimate of NAIRU has declined to 5% - 5.2% unemployment, which is an acceptance of the reality that there is zero pressure on inflation from wage growth at this point, and likely won't be for awhile.
All well and good, but here is the Fed's high end estimates for inflation for this year and the next two years:
Core inflation
2015 1.4%
2016 1.8%
2017 2.0%
The Fed doesn't expect core inflation to hit their 2% target for two years! Yet here is what they say:
[T]he Committee expects inflation to rise gradually toward 2 percent over the medium term as the labor market improves further and the transitory effects of energy price declines and other factors dissipate..
.... In determining how long to maintain this target range, the Committee will assess progress--both realized and expected--toward its objectives of maximum employment and 2 percent inflation. ... The Committee anticipates that it will be appropriate to raise the target range for the federal funds rate when it has seen further improvement in the labor market and is reasonably confident that inflation will move back to its 2 percent objective over the medium term
Since lower gas prices are likely to cause core inflation to slightly decrease over the next year as they feed through into the broader economy, it will take well over a year for such factors to "dissipate." But the Fed is going to raise rates in advance of 2% YoY core inflation, to ensure it does not exceed that level.
In practice that's a ceiling, not a target.
Wednesday, March 18, 2015
The S&P Case Shiller Index as objective evidence of a housing bubble, and a leading indicator for core inflation
- by New Deal democrat
Recently I had a pretty good and spirited discussion about macroeconomics and forecasting the Great Recession.
One issue is, how easy or not was it to spot the housing bubble? Dean Baker certainly did. But was there objective evidence? There was.
Home prices themselves are not part of the CPI, although "owners equivalent rent," the housing portion of CPI, constitutes over 1/3 of that index. Ideally the inflation rate for each should stay relatively close, since rent is presumably the trade-off for housing. But in a bubble, that trade-off ends because "Everybody knows house prices only go UP!!!"
At that point, the tradeoff vanished. Rent inflation was subdued because renters wanted to become homeowners. And look what happened to the cost of housing (via the Case Shiller 10 city index) vs. owner's equivalent rent (in the linked graph, both are normed to 100 in 1987):

House prices went from about 1.15x the rent index to 1.85x the rent index, a 50%+ increase, in just 4 years. That is the signature of a bubble.
House prices went from about 1.15x the rent index to 1.85x the rent index, a 50%+ increase, in just 4 years. That is the signature of a bubble.
What did the Fed do in the face of that objective evidence of a bubble? Nothing, until it was far too late. Tim Iacono of "The Mess That Greenspan Made" came up with a great way of looking at housing inflation, by substituting the Case Shiller Index for the Owners' Equivalent Rent in the CPI, calling the result the CS-CPI. The below graph shows the CS-CPI in blue, and the Fed Funds rate in red:

The Fed treated inflation as subdued, and kept the Fed funds rate at 1%,when measured by the CS-CPI it was as high as nearly 10%. (I have always suspected Greenspan held off for political reasons, to assist the re-election of W. But Greenspan would never be political, would he?) Not only that, but the Fed subsequently kept the funds rate at 5% after the bubble had completely burst.
The run-up in house prices vs. rents in 2012-14, by contrast, is pretty subdued.
An interesting by-product of this is that the Case-Shiller house price index appears to lead owners equivalent rent by about 1 year:

There has been a big downturn in the growth of the Case Shiller index in the last year, that doesn't appear to have fed through into owners' equivalent rent. Nor has the recent big downturn in gas prices fed through into the direction of core CPI, which typically also takes about a year. Together, these two trends strongly suggest that core CPI inflation, already below 2%, is going to decrease further. Which by the way means that the Fed ought to hold off on rate increases, and let (hopefully) higher wage growth and lower unemployment continue.
With a Yield Over 5%, Take A Long Look At Phillip Morris
This article is not a solicitation to buy or sell these securities. You might also want to do your own research into this; heck, you just might learn something.
Recently, Morningstar wrote a story titled, "The Ultimate Stock Pickers Top 10 Dividend Stocks" which contained a total list of 20 stocks whose dividend was higher than the S&P 500 and whose shares were owned either by a leading manager or leading fund. Topping one of the lists was Phillip Morris (PM).
Let's start by taking a look at the weekly chart:

The chart is certainly not one to get excited about. It's been trading in a fairly tight range of 75-89, with a tighter range of 79-89 over the last three years. However, the stock price has recently dropped to the 78 level, making it attractive. So, let's take a deeper look at the company.
According to their latest 10-K, Phillip Morris and "[o]ur subsidiaries and affiliates and their licensees are engaged in the manufacture and sale of cigarettes, other tobacco products and other nicotine-containing products in markets outside of the United States of America. Our products are sold in more than 180 markets and, in many of these markets, they hold the number one or number two market share position. We have a wide range of premium, mid-price and low-price brands. Our portfolio comprises both international and local brands." Their market cap is about 120.5 billion, making them the largest cigarette company according to the Finviz.com website. They are one of the top three cigarette makers, with British American Tobacco and Altria group close second and third runners-up.
Their operations are entirely international, with the following regional breakdown (click for larger image):

In the last three years, the Eastern Europe segment has gained 7.9% of the companies overall sales while the Asian market has decreased 10.3%. Consider this situation in relation to the high level of the dollar, and the negative impact that will have on earnings. Many multi-national companies have stated that the strong dollar is seriously impacting their financial performance; don't expect anything different from PM.
The biggest risk the company faces is litigation and the potential downside of a massive award against the company. As this table shows, the company currently faces 93 different lawsuits (click for a larger image):
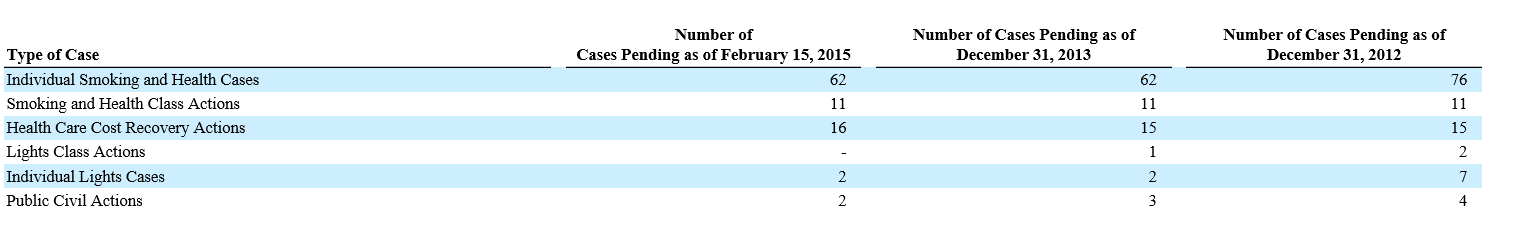
But, the company has been very successful at defending these causes of action. From the 10-K: "Since 1995, when the first tobacco-related litigation was filed against a PMI entity, 433 Smoking and Health, Lights, Health Care Cost Recovery, and Public Civil Actions in which we and/or one of our subsidiaries and/or indemnitees were a defendant have been terminated in our favor. Ten cases have had decisions in favor of plaintiffs. Nine of these cases have subsequently reached final resolution in our favor and one remains on appeal."
While this is no guarantee that future litigation will lead to the same result, it does indicate that Morris' litigation team has been strikingly effective.
PM is a leading brand with very high barriers to entry.
Financials
The chart above indicates this is a pure dividend play. While there is upside potential on the current chart, the fairly predictable trading range of the security over the last three years indicates that once the stock hits the mid-80s, bears will take over. This means the most important consideration for any investor is dividend safety. Obviously, the insure a continual payment of the dividend we need, at minimum, revenue and margin predictability.
For the last 5 years, revenue has risen a bit going from $27.2 billion in 2010 to $29.7 billion in 2014. Revenue was higher between 2011-2013, coming in a bit over $31 billion. Expenses have been very predictable over the same period:
COGS: 33%-35%
Operating expenses: 23%-25.6%
Net Income: 25%-28%
The above numbers indicate that revenue and expenses have been very predictable and should continue to be so over at least the next year.
The dividend payout ratio has fluctuated between 55.7% in 2011 to 80.5% in 2014, meaning the company pays out a large percentage of its net income to shareholders.
Just as importantly, PM is a company that prints money, with free cash flow to the firm of between $6.5 billion in 2014 to $9.6 billion in 2011. Their primary operating expense is property investment, which is very predictable, with the figure right around $1.1 billion over the last three years. This is only 14% of the lowest number for operating cash flow for the last five years, meaning the company is flush with cash.
The only drawback to the balance sheet is the company has loaded up on debt, with their long-term debt totals increasing from $13.3 billion in 2010 to $26.9 in 2014. This makes their long-term debt position a whopping 76% of total assets. But, their interest coverage ratio at these high levels is 10.86. And with EBITDA reported at between $12.1 and $14.7 over the last five years (not to mention the company's very strong cash flow position), a default isn't on the horizon.
Conclusion
In a record low interest rate environment, high paying dividend stocks become exceedingly attractive, so long as there is a consistency to the underlying company's financial performance. PM has such a profile, with steady earnings and expenses, a more than adequate cash flow and a strong policy of passing earnings onto shareholders. These factors make PM a solid stock for dividend investors, especially at these levels.
Tuesday, March 17, 2015
Ignore housing starts, housing permits were encouraging
- by New Deal democrat
You don't need decent weather to get a housing permit. You need decent (or at least not horrendous) weather to actually start building a house. That makes winter housing starts particularly volatile.
In general, housing starts (red in the graph below) are twice as volatile as housing permits (blue). I've squared the results so that they are all positive, making it easier to see the volatility:

That's why I focus on permits rather than starts. Plus permits tend to lead starts by a month.
So what is going on with permits? Here they are in absolue terms:

And here is the YoY trend:

Housing permits in February were only exceed by last October. And the YoY trend has turned up mildly. So consider me unperturbed by the morning's housing starts miss, and encouraged by the good permits number.
February may have seen a sharp intensification of deflation
- by New Deal democrat
I have a new post up at XE.com. According to the Billion Prices Project, consumer prices fell sharply in February.
If so, that puts entirely different gloss on the February decline in nominal retail sales, and suggests that real Q1 GDP will not be as poor as feared.
Monday, March 16, 2015
Sunday, March 15, 2015
Saturday, March 14, 2015
In which I look strangely at Paul Krugman
- by New Deal democrat
Prof. Paul Krugman writes today: "When I tell people that macroeconomic analysis has been triumphantly successful in recent years, I tend to get strange looks."
Consider me looking strangely. Yesterday Krugman acknowledged that few macroeconomists saw the Panic of 2008 coming, but once it happened many (like him) immediately saw how it needed to be addressed:
"Well, very few [macroeconomists] saw the crisis coming — mainly, I’d say, for two reasons. First, most economists (me too) failed to understand how the growth of shadow banking, which lacked a deposit-insurance safety net, had recreated the possibility of old-fashioned financial panics. Second, we didn’t pay nearly enough attention to household debt. So the crisis came as a surprise.
"But these were failures of observation, not fundamental conceptual problems, and the sensible half of the profession quickly took them on board — basically realized that we were seeing old issues in new bottles. Or as I tend to think of it, we collectively went “Aha! Diamond-Dybvig-Irving Fisher yowza!” and all was clear."This is rather like an air traffic controller who allows two jumbo-jets to crash in midair, but afterward is really good at directing to which hospital to send the mangled living among the smoldering carnage. You know, "sorry about that midair collision, but please have 30 ambulances on runway 15W to take the survivors to Metro Hospital STAT!"
Krugman excuses macroeconomists for failing to see the crash coming due to "failures in observation." Well, this is me on November 30, 2007, describing the coming "Panic of 2008:"
This is NOT the Great Depression II. Nor is this the stagflationary 1970s. It is going to unfold as some other Beast. Only the broad outlines of this Beast appear discernable now: it will likely feature (1) increasing import prices; (2) wage stagnation (that does not keep up with price inflation; (3) real asset deflation; and (4) possibly a Japan-style "liquidity trap." In fact, while I believe we are already in a recession, I suspect there will be a business upturn late next year.
Furthermore, I believe there will be NOT any "runs" on FDIC-insured bank deposits. Period. In fact, I suspect they will turn out to be the best havens in the storm. But this slow motion bust, this Panic of 2008 (and thereafter), will be painful, and it will unfold. I do not think it can be avoided any more."
I followed that up on January 7, 2008 with this description of a "slow motion bust."
"I constantly describe the era we are in as a "Slow Motion Bust." A few days ago economist/blogger Prof. Brad DeLong published an excellent article that describes just what I have been trying to convey by that term."Whoever inherits the White House on January 20, 2009 is likely to confront serious and urgent economic conditions unlike any we have seen in our lifetimes. For the mortgage crisis is only part of a bigger insolvency crisis that has already taken longer to unfold than most economic downturns in our history."...
"[T]he problem has slowly worsened over the last year -- in other words, it has become "a slow motion bust." Let's first note that housing prices probably peaked nationwide by early 2006. By February 2007, as noted by Calculated Risk, there were serious problems with subprime mortgage- backed investment paper. By August, the problems had spread far beyond subprime mortgages, and banks and hedge funds were facing liquidity problems.
"Prof. DeLong's article describes perfectly why I have been calling this a "slow motion bust". Very much unlike its 19th and 20th century predecessors, instead of going from boom to deflationary spiral suddenly, in a matter of mere months, this bust began to implode a year ago, and bit by bit financial assets (what blogger Russ Winter calls "fictitious capital") are being written down or written off entirely. Only now are serious financial thinkers beginning to worry about the "third mode" of a deflationary spiral."
If not all the data was out there publicly, enough of it was to get an idea about the risks of what was coming. Not just a point or two off of GDP, not just a little recession, but a modern variation on an old-fashioned bust, due to too much debt and leverage in the system. If yours truly could see it - and could see how it was likely to play out - why couldn't, by Krugman's own admission, macroeconomists?
So consider this me giving Paul Krugman a strange look.
Weekly Indicators for March 9 - 13 at XE.com
- by New Deal democrat
My Weekly Indicators post is up at XE.com.
The effects of the West Coast port strike are abating. Meanwhile, the question is, just how much outright deflation is the US importing?
Friday, March 13, 2015
The 3 dimensional Phillips curve as a forecasting tool
- by New Deal democrat
Why do I continue to harp on the Phillips curve being best viewed as 3 dimensional, with the third dimension being basic commodity prices? Because it helps forecast where the traditional, 2 dimensional Phillips curve is likely to be in a year or so. And since the Fed is focused on the "non-inflationary rate of unemployment," we at very least want to maximize employment and wages without causing self-defeating inflation. Which means we don't want the Fed to apply the brakes too early.
I can actually show you this very neatly in traditional, two-dimensional graphs. Some might object that I am "double-counting" inflation, since one axis is commodity prices, the other consumer prices. But commodity prices do not move in sync with consumer prices. In the graph below, both commodity and headline consumer prices are normed to 100 in 1982:

You can see that over the long term, commodity prices have gone up at less of a rate than consumer prices, but with significant exceptions in the early 1970s and the 2000s.
Now let's take ratio of commodity prices to consumer prices, and compare it with the "misery index" which is the addition of the two components of the Phillips curve, the unemployment rate + the YoY consumer inflation rate:

With just a few exceptions, (the late 1960s and 1989-90), for the last half a century the two have moved in tandem. This is strong evidence that the relative strength of commodity vs. consumer prices does indeed move the Phillips curve along a third axis. Furthermore, note that the "misery index" lags the ratio of commodity to consumer prices. By knowing the relative YoY% changes in commodities vs. consumer prices, we can forecast where the Phillips curve will be about 12 months later.
And to be clear, here is the YoY% change in commodity prices (blue) vs. core inflation (red, first graph) and the unemployment rate (red, second graph):


Commodity prices (the Z axis on the 3 dimensional Phillips curve) lead both core inflation and the unemployment rate.
Finally, here is a scatterplot of commodity prices and the unemployment rate over the last 5 years:

The values have been consistently shifting to the lower left, with the last two months at the extreme bottom left. This tells us that the 2-dimensional Phillips curve has also been shifting downward and to the left.
In short, treating the Phillips curve as 3 dimensional gives us the ability to forecast the values of the traditional two dimensional Phillips curve 1 year out. In 2015 this means the traditional Phillips curve should shift to downward and to the left of where it has been in the last few years. Since the values of the last several years already indicated an overshoot of the Fed's inflation target of less than 1%, the 3 dimensional Phillips curve forecasts that unemployment can fall well below the Fed's range of 5.2%-5.5% without triggering core inflation in excess of 2%.
February Retail sales: how big of an 'Ouch!'?
- by New Deal democrat
I have a new post up at XE.com, discussing yesterday's retail sales report.
Hold your fire until you see what the inflation adjustment is.
The Phillips curve in 3 dimensions, animated
- by New Deal democrat
Yesterday I wrote that the Phillips curve might best be considered as three-dimensional, where the third axis was commodity prices, and in particular Oil. A shock to underlying commodity prices would also "shock" the unemployment vs. inflation trade-off, moving the curve along the third dimension.
Thanks to the help of a reader, I am able to show you this animated gif of the Phillips curve. The X axis is the unemployment rate, the Y axis is YoY headline CPI, and the Z axis is YoY PPI commodity prices.
Since there are many points with the same UNEMPxCPI (x,y) value, the mean PPI for those values was used. As you can appreciate, the distribution is noisy, so as my correspondent noted, the "data does not suggest a smooth function."
With that introduction, here is the Phillips curve in 3 dimensions as an animated gif;

Thursday, March 12, 2015
The Phillips curve in the 21st century (or, The Phillips curve as a 3 dimensional foil)
- by New Deal democrat
This is my third post about the possibility of the Fed raising rates as early as June.
In the first post, I pointed out that both wage growth and inflation are at historic, half-century lows. Further, the heightened number of involuntary part-time employees and those who want a job now, but have completely given up looking, suggest additional slack as compared with other instances of 5.5% unemployment, There is not the slightest pressure on inflation from wages at present.
In the second post, I showed that since the turn of the Millennium that CPI inflation, ex-Oil, has never exceeded 3%, even with 4% unemployment or 4% YoY wage growth. Further, it is likely that core inflation in the next 12 months will actually decrease somewhat as the collapse in oil prices feeds through the economy.
Now let's look at the 21st century Phillips curve, i.e., the tradeoff between inflation and unemployment.
To begin with, the Phillips curve is regaining respectability as some economists (pdf) consider it is not a 2-dimensional curve, but a 3-dimensional foil, similar to this graph, which was the best visualization of the concept I could find:

The insight is that labor is one of many commodity inputs. A significant change in the cost of other commodities changes how much labor can be profitably employed. Thus the third dimension is the cost of non-labor commodities, and in particular Oil. An exogenous shock such as the 1974 Oil embargo, which suddenly and dramatically increased the price of a basic good, will shift the 2 dimensional Phillips curve along the third axis.
[Note: I apologize for the non-uniformity of the graphs below. Some were prepared quite some time ago, under the "old" FRED. The new and allegedly "improved" FRED is considerably less functional. I traded uniformity for clarity of presentation.]
So let's generally divide time periods into low and high priced oil. I'll start by showing the inflation-adjusted price of Oil:

The regimes are: (1) low prices from 1948-73; (2) high prices from 1974-85; (3) low prices from 1986-2000; and (4) high prices from 2001-14.
Here's the Phillips curve datapoints for each (The y axis is the unemployment rate. The x axis is the YoY% change in headline inflation):
The regimes are: (1) low prices from 1948-73; (2) high prices from 1974-85; (3) low prices from 1986-2000; and (4) high prices from 2001-14.
Here's the Phillips curve datapoints for each (The y axis is the unemployment rate. The x axis is the YoY% change in headline inflation):
1. Low prices from 1948-73:

2. High prices from 1976 through 1985:

3. Low prices from 1986 through 2000:

4. High prices from 2001 to the present::

Notice that high unemployment in excess of about 7.5%, only occurs in the eras of high priced oil. Contrarily, low unemployment below 4.5%, only occurs in eras of high priced oil. Here's a quick comparison of approximate unemployment rates common to all eras:
Notice that high unemployment in excess of about 7.5%, only occurs in the eras of high priced oil. Contrarily, low unemployment below 4.5%, only occurs in eras of high priced oil. Here's a quick comparison of approximate unemployment rates common to all eras:
2.5% Unemployment:
Era // Inflation
1948-73 // 7%
1974-85 // 10%
1986-2000 // 7%, 4%
2001-14 // 10%
5.5% Unemployment:
Era // Inflation
1948-73 // 4%
1974-85 // 7.5%
1986-2000 // 4.5%
2001-14 // 5.5%
The Phillips curve has shifted upward and outward on the 3-dimensional foil during periods of high oil prices.
For the rest of this piece, I'm going to focus on the era of 2001-present.
As you can see from the final graph above, headline inflation has almost always exceeded the Fed's 2% target in times of 5.5% unemployment or less.
But as I showed yesterday, ex-Oil inflation since 2001 has never gotten above 3%. Here's the Phillips curve for unemployment vs. CPI less energy:

It's still true that at 5.5% unemployment or less, CPI inflation ex-Oil is over 2%. But at the absolute worst it is no more than 3%.
Finally, here is the Phillips curve of unemployment vs. core inflation. Craig Eyermann of Political Calculations graciously calculated a regression. Note that the axes are reversed compared with previous graphs):

Similarly, the worst inflation is less than 3%, even at 4% unemployment.
Granted that under all 3 inflation calculations, since the year 2000 an unemployment rate under 5.5% has almost always correlated with an inflation rate in excess of 2%. But even so, even if the unemployment rate should fall as low as 4%, the risk is that we overshoot 2% YoY CPI by less than 1%.
Further, if we have at least temporarily entered a period of low oil prices, then the Phillips curve should once again shift downward and to the left on the 3-dimensional foil, and there is evidence that it is already doing so, as shown in this graph zooming in on the last 5 years:

As Oil prices rose by 40% YoY in 2011-12, the inflation rate hit 3% even with high unemployment, but since then the Phillips curve has shifted downward and to the left as gas prices stabilized. Further, note the two overlapping dots at 5.6-7% unemployment and 1.88% CPI less energy. The Phillips curve is now shifting even further downward and to the left in response to the collapse in gas prices. Thus, consistent with the late 1990s and the post WW-2 period, we could have as low as 4% unemployment without inflation exceeding 2%.
As Oil prices rose by 40% YoY in 2011-12, the inflation rate hit 3% even with high unemployment, but since then the Phillips curve has shifted downward and to the left as gas prices stabilized. Further, note the two overlapping dots at 5.6-7% unemployment and 1.88% CPI less energy. The Phillips curve is now shifting even further downward and to the left in response to the collapse in gas prices. Thus, consistent with the late 1990s and the post WW-2 period, we could have as low as 4% unemployment without inflation exceeding 2%.
Considering we have just endured 5 of 6 years with inflation under the Fed's target with subpar wages and high unemployment, the risk of a 1% overshoot -- or possibly no overshoot at all! -- hardly justifies tamping down on improvements to laborers.
Wednesday, March 11, 2015
Inflation in the 21st century: Oil, not wage growth or unemployment, is the issue
- by New Deal democrat
This post follows up on my last piece, in which I argued that there are historically non-existent wage or inflationary pressures in the economy, so the notion that the Fed should raise short term rates now to contain such pressures doesn't pass muster.
I'm going to show you that by looking at the Phillips Curve (the tradeoff between the unemployment rate and inflation) in my next piece.
But I can cut to the chase with just one graph. Here is the CPI for all items (green) compared with core CPI (blue), and CPI less energy (red):

Focus on two things.
First, the red line. While consumer inflation for all items have gone as high as 5.5%, once we subtract Oil, inflation has only been as high as 3%, and has only exceeded the Fed's target range of 2% once (2012) in the last 6 years, and that only by +0.6%.
Second, as I pointed out in my first piece, the relationship between core and headline inflation is a two way street. Think of the earth-moon system. The center of gravity is not the center of the earth. The moon doesn't just revolve around the earth, to a limited extent the earth "revolves" too, wobbling in its orbit in the direction of the moon. Similarly, just as headline inflation rate tends to revert in the direction of the core inflation over the ensuing 24 - 36 months, so headline inflation accurately forecasts the direction of core inflation over the next 12 months.
Let me delete CPI less energy, and zoom in on that relationship:

Since 2000, there have been 4 peaks and 3 troughs in headline and core inflation. Here's the record:
PEAK
Headline // Core
3/00 // 2/01 (11 month lag)
9/05 // 9/06 (12 month lag)
7/08 // 7/08 (simultaneous)
9/11 // 4/12 (7 month lag)
TROUGH
Headline // Core
6/02 // 12/03 (18 month lag)
11/06 // 9/07 (10 month lag)
9/09 // 10/10 (13 month lag)
So to summarize:
- core inflation has been below the Fed's target with 1 exception for the last 6 years.
- core inflation is likely to decline further below 2% in the next 12 months.
- most importantly, inflation ex-oil has been no higher than 3% in the last 15 years, (i.e., irrespective of the unemployment rate or wage growth during that period).
Literally the ONLY thing driving inflation above 3% in the last 15 years has been the secular rise in the price of Oil. Even at the high point for wage growth and the low point for unemployment.
Raising interest rates in the face of this data would mean that the Fed is treating 2% inflation as a ceiling rather than a target, that it is subordinating its goal of full employment to that ceiling, and that it is beginning to apply the brakes on the economy - and depress wage and job growth - solely because of a possible 1% overshoot, or the possible impact of unrelated higher oil prices in the future.
I'll flesh this out further by showing you the actual Phillips curves in my next post.
Monday, March 9, 2015
Dear Federal Reserve: *Now* is the time to raise interest rates? RLY?? SRSLY?!?
- by New Deal democrat
I am at a complete loss as to why the Federal Reserve might think that now is the moment to begin raising interest rates. I cannot see a scintilla of hard evidence in support, and potent evidence against.
The theory is that the Federal Reserve must start to "normalize" interest rates in order to stave off inflationary pressures, particularly inflationary pressures from wages.
Here is the last 65 years of consumer inflation YoY:

In that entire time, the only occasions on which there was less inflationary pressure than there is now is immediately after the 1950, 1952, and Great Recessions.
The situation is even more compelling when we look at the rolling 3 month average of average hourly earnings:

(h/t Doug Short for preparing this graph)
In the last half a century, there have only been 2 three-month periods, from November 2011 through February 2012, when there was less inflation than there is now.
In other words, of the last 600 measurements, only 2 of them have been less than now. That's 1 in 300. In other words, we are in the bottom 0.05% of all measurements. 99.5% of the measurements have shown more inflationary pressure than now.
And it's not likely, based on your own core measure, that we will see much inflationary pressure in the next 12 months. Because as you well know, just as core inflation tends to predict the direction of all prices in the next 24 to 36 months, so it takes 12 months or so for current gas prices to feed through into the rest of the economy:

In other words, it is likely that the core inflation reading is going to move lower for the rest of 2015.
Now let's look at wage "growth." Here is nominal YoY wage growth for the last 50 years:

Wages now are putting less pressure on prices than at any time in the last 50 years with the exception of 8 months in 2012. This is wage pressure??? Again, of the last 600 measurement periods, only 9 of them have shown less pressure than at present. That puts us in the bottom 1.5% of all time periods in the last 50 years for wage pressure.
I realize that the unemployment rate just fell to 5.5%, and you think that inflationary pressures might start to build as unemployment falls to 5%.
But your own staff has just published a paper indicating that the percentage of long-term unemployed (i.e., people unemployed 27 months or more) is an independent factor in calculating when wage pressure might begin to build. And here's what that looks like now:

Higher than at any point in the last half century with the exception of the last few years, and coming out of the 1981-82 recession.
And 5.5% unemployment now is not the same as 5.5% unemployment 10 or 20 years ago. Here is the percentage of the labor force consisting of full-time employees (blue) compared with inflation (red):

In 1998 and 2002 when inflation started to increase off the bottom, the full time employees were 78.3% and 77.6% of the labor force. Now they are only 77.0% of the labor force.
And that's not all. Here is that same information (red) compared with full time employees as a percentage of the labor force plus those who want a job now, but are so discouraged they have dropped out of the labor force (blue):

In 1998 and 2002 respectively, those not in the labor force who wanted a job were 2.7% and 2.5% of the total. Right now they are 3.1% of the total.
So, to summarize, inflation is in the lowest 1% of all times in the last half century, wage growth is in the lowest 1.5% of the last half century, we still have extraordinarily high long-term unemployment, and a unusually high percentage of part-time employees and discouraged workers even taking into account the current unemployment rate.
Finally, just consider the historical record, limited as it is, of when the Federal Reserve has raised interest rates in the present of out-and-out deflation.
This has happened only once since World War 2:

and three times before - in 1928, 1930, and 1937:

Correlation is not causation and all that, but that's 3 out of 4 times with disastrous results. Do you like those odds?
In short, you know that raising rates will put additional pressure on wages and employment. So you think NOW of all times is the appropriate time to raise interest rates. Really?? Seriously?!?
Subscribe to:
Posts (Atom)