Friday, March 19, 2021

Coronavirus dashboard for March 19: yes, vaccinations are working


 - by New Deal democrat

The three big Western standouts for vaccination progress have been Israel, the UK, and the US, respectively. And in all three, there have been dramatic declines in both cases and deaths.


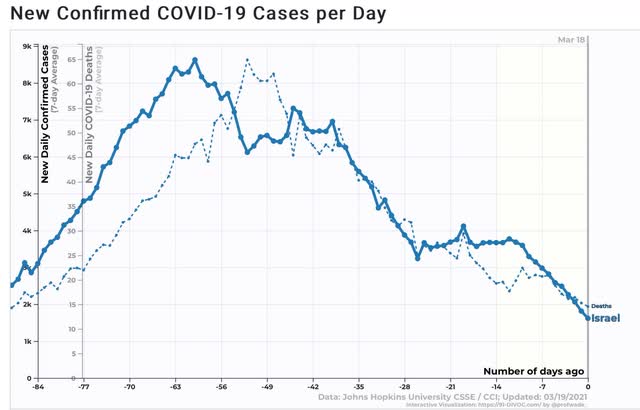
Let’s look at them in order. First, Israel:


56% of all Israelis have had at least one dose of the Pfizer vaccine. 50% have been fully vaccinated.

Cases have declined 81%. Deaths have declined 77%.

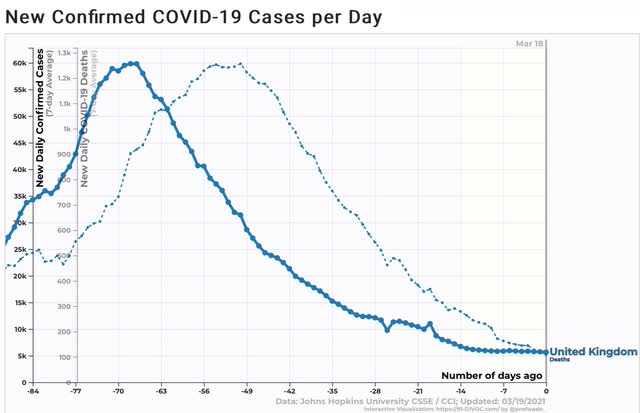
The UK’s vaccination program has coincided with a partial lockdown that began on January 4:


40% of the population has had at least one dose. 30% is fully vaccinated.

Both cases and deaths have declined by 91%.

The US is in 3rd place:


23% of the US population has received at least one dose. 12.5% has been fully vaccinated.

Cases have declined by 78%. Deaths have declined by 65%.

Vaccinations are working. Hopefully as those opposed to taking the vaccine see their family, friends, and neighbors returning to close to normal lives without contracting the virus, they will lose their hesitancy and do the obvious, rational, and easy thing.

P.S.: Here is an updated graph on hospitalizations in the US:

This is more evidence that serious illness and death among the institutionalized elderly from COVID has all but disappeared.

Thursday, March 18, 2021

Disappointing weekly increase in new jobless claims, but monthly trend improves; expect a 200,000+ number of new jobs in next Employment Report


 - by New Deal democrat

New jobless claims are likely to the most important weekly economic data for the next 3 to 6 months. They are going to tell us whether my suspicion is correct that, as a critical mass of those vaccinated is reached, there will be a veritable surge in renewed commercial and social activities and attendant consumer spending, leading in turn to a strong rebound in monthly employment gains.

More specifically, now that further COVID relief has also been passed by Congress, last week I set a few objective targets: I am looking for new claims to be under 500,000 by Memorial Day, and below 400,000 by Labor Day. 

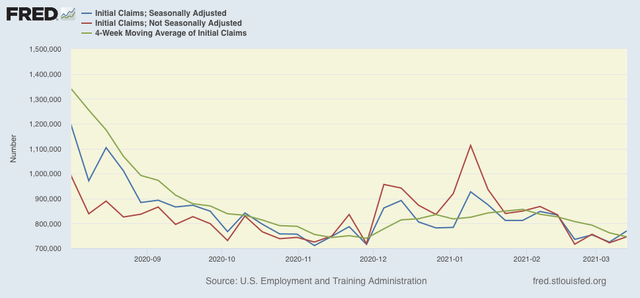
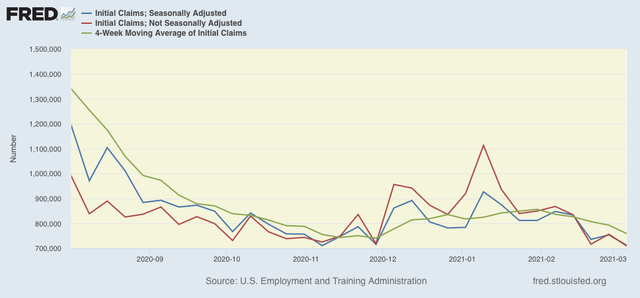
This morning’s data didn’t help. On a unadjusted basis, new jobless claims rose by 424,318 to 746,796. Seasonally adjusted claims rose by 45,000 to 770,000, the highest level in 4 weeks. The 4 week moving average, however, declined by 16,000 to 746,250.  

Here is the close up since the end of July (these numbers were in the range of 5 to 7 million at their worst in early April): 

While both adjusted and unadjusted claims remain above their worst levels at the depths of the Great Recession, the outbreak-related wintertime surge has abated.

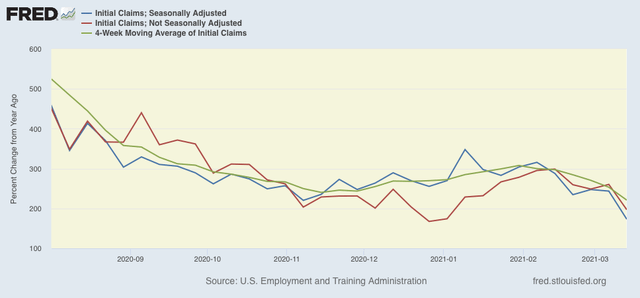
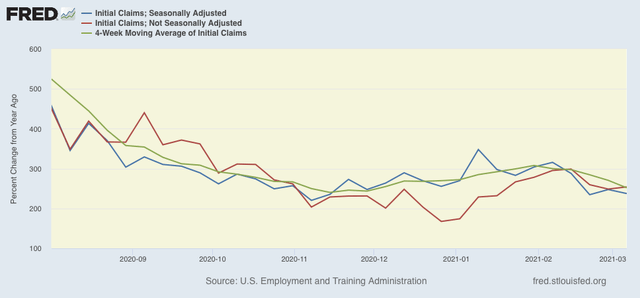
Because of the huge weekly swings caused by the scale of the pandemic, a few months ago I began posting the YoY% change in the numbers as well, since they are much less affected by scale, so there is less noise in the numbers, and the trend can be seen more clearly:

This is at levels last seen in November and December, and confirms that the recent increase in new claims has reversed. In fact, all 3 metrics are at pandemic lows of increases of 175%-225%. An important caveat is that YoY numbers are starting to be compared with the horrific initial pandemic losses of last March and April, so I will probably discontinue this metric in the next several weeks.

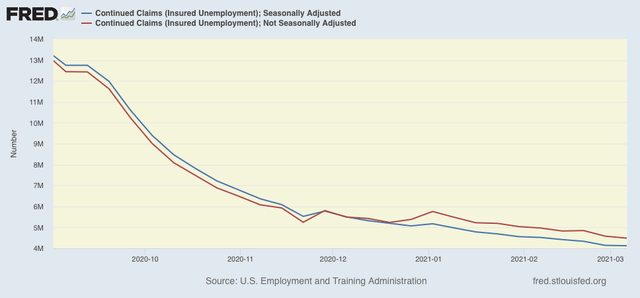
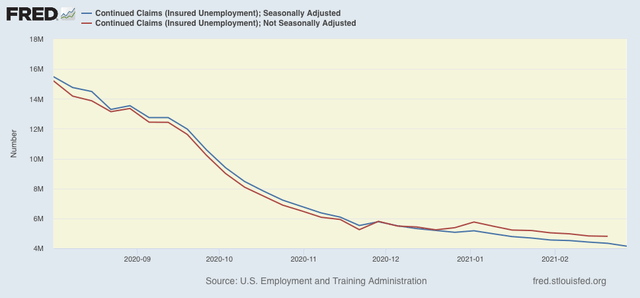
Meanwhile continuing claims, which historically lag initial claims typically by a few weeks to several months, made new pandemic lows yet again this week. Seasonally adjusted continuing claims declined by 18,000 to 4,124,000, while the unadjusted number declined by 95,541 to 4,486,389:


Nevertheless seasonally adjusted continued claims remain at levels last seen at the end of 2010.

Bottom line: although this week’s number of new jobless claims was disappointing, I remain bullish that the ever-increasing pool of fully vaccinated adults - 40,000,000 as of yesterday, or 15.5% of the adult population - together with a seasonal shift from indoor to outdoor activities, is going to result in new pandemic lows well below the existing low of 711,000.

Further, the monthly change in the 4 week average of initial claims ending last week is the best we have seen since November, when 264,000 jobs were added to the economy. As a result, I am looking for a similar number in the March jobs report which will be released at the beginning of April.

Wednesday, March 17, 2021

February declines in housing permits and starts: another likely effect of the Big Texas Freeze


 - by New Deal democrat

Housing is an important long leading indicator. What we see now in mortgage applications, new home sales, permits and starts is informative of what the economy will be like 12+ months from now in 2022.


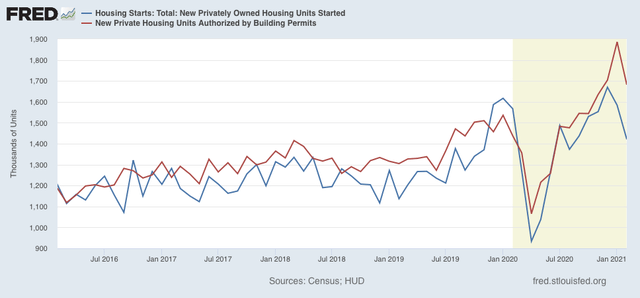
The headline numbers for both permits and starts for February, released this morning, were both poor, off -10.8% and -10.3%, respectively. The temptation is to say, “higher interest rates, We’re DOOOMED!!!” Not so fast. In context, the declines were well within normal month to month variation, and at least some of the declines looks like more fallout from the Big Texas Freeze that we saw yesterday in industrial production and retail sales.

Here is the headline graph covering the last 5 years for both starts (blue) and permits (red):


Two things are of interest here: (1) note that starts fell much more than permits, similar to what happened in the last two winters; and (2) while typically permits lead starts by a month or two, this decline in starts began *before* permits. Neither of these facts are conclusive, of course, but they do suggest an external reason for the pattern - e.g., an outsized winter “event” in February.

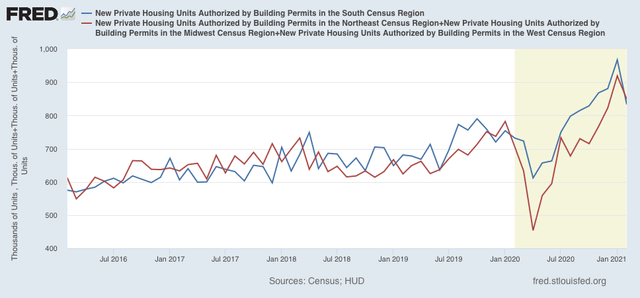
I’ve also separated out the South Census Region that includes Texas from both permits and starts in the other three Census Regions (Northeast, Midwest, West) combined in the below two graphs. First, here’s permits:


Note that while both declined, the Southern region had the bigger one.

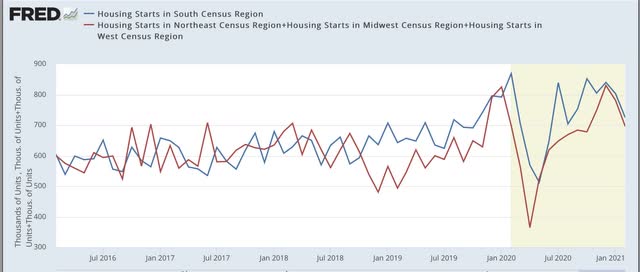
Now, here’s starts:


Again, note the outsized declines in the other three regions including both northern ones in the last two winters, that hasn’t occurred this year. Put another way, the decline in the South, including Texas, was a *relatively* outsized one.

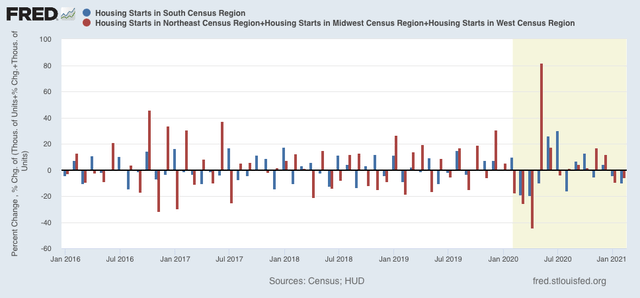
Finally, here is the above regional data for starts shown as a month over month % change:


As I wrote above, February’s declines are hardly noteworthy as monthly declines from the perspective of monthly changes in the past five years. And the February decline in starts in the South this year is bigger than that of the other three regions combined, unlike the last several winters.

I don’t want to oversell this, because the above information is hardly conclusive. But all of this information suggests that, while interest rates most likely did affect at least permits in February, the bigger reason for the relatively big declines in permits and starts was the closure of government offices and inability to undertake new construction in Texas and other nearby areas affected by the Big Freeze.

Tuesday, March 16, 2021

Big (weather related) declines in February production and sales


 - by New Deal democrat


This morning we got the most important single metrics for both the consumer and producer side of the economy for February, respectively, retail sales and industrial production. Both were big misses, one explicitly and the other likely due to the big freeze in Texas and neighboring States.

Let’s turn to production first.

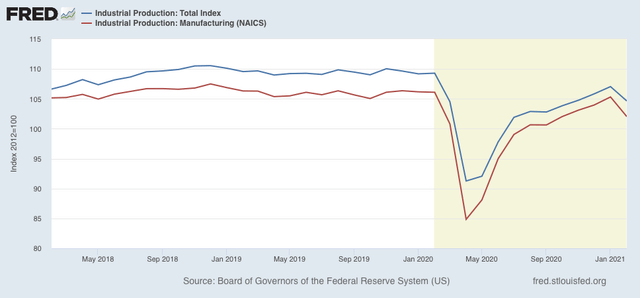
Total industrial production declined by -2.2% in February, while manufacturing production declined -3.1%. Both of these were the first declines of any significance since last April:


Before the DOOOMERS go screaming, “Double-dip!” however, here is the what the Fed itself had to say about this report:

The severe winter weather in the south central region of the country in mid-February accounted for the bulk of the declines in output for the month. Most notably, some petroleum refineries, petrochemical facilities, and plastic resin plants suffered damage from the deep freeze and were offline for the rest of the month. Excluding the effects of the winter weather would have resulted in an index for manufacturing that fell about 1/2 percent and in an index for mining that rose about 1/2 percent.

Because manufacturing is the biggest component of the report, even without the Big Texas Freeze the total index probably would have declined, but by something less than -0.5%. Since in January the total index rose a revised 1.1%, the combined January-February number would still be positive, and the highest since the onset of the pandemic last March.

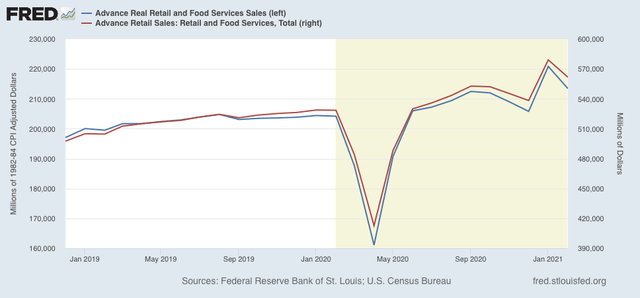
A similar dynamic was present in the retail sales report, although the Census Bureau explicitly does not take weather into account. Nominal retail sales declined -3.0%. After adjusting by the CPI, real retail sales declined -3.4%. Here’s what the last 2.5 years including February look like:


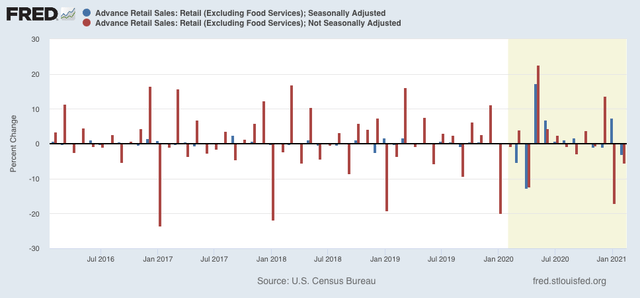
Of course winter occurs every year, but if and when a particularly bad stretch happens might be in December one year, January another, and February still another. So the below graph shows the unadjusted as well as the seasonally adjusted percentage change each month for the same time period. Note that January and February each year, combined, show the steepest month over month decline:


If you look at the unadjusted numbers, it’s pretty clear that January this year had the least decline of the last 5 years, while February’s was the worst. So the below lists the combined January + February declines for the previous 5 years and compares them with this year:

2016: -21.8%
2017: -24.3%
2018: -23.6%
2019: -22.1%
2020: -20.6%
2021: -21.6%

Of the 5 previous years, only 2020 was better than this year. On a seasonally adjusted basis, the combined January-February period this year still showed a gain of 3.7% from December, which would be the highest total since the pandemic started.

In conclusion, don’t sweat these two declines. Ex-the Big Texas Freeze, both production and sales probably did decline, but only slightly, and real retail sales for the two month period combined absolutely rose. 

Monday, March 15, 2021

Coronavirus dashboard for March 15: good news, and cause for concern


 - by New Deal democrat

A year ago today I wrote about the accuracy of Jim Bianco’s forecast of exponential spread of COVID-19. At that time there were exactly 2952 cases, but increasing at 30% each day, and I wrote, “I have not seen any government action significant enough to stop this exponential projection being correct.” 

As of yesterday, there have been 29,438,775 *confirmed* cases - 9% of the total US population. There have certainly been many more cases which have never been confirmed by testing, primarily but not always because they were mild or asymptomatic.


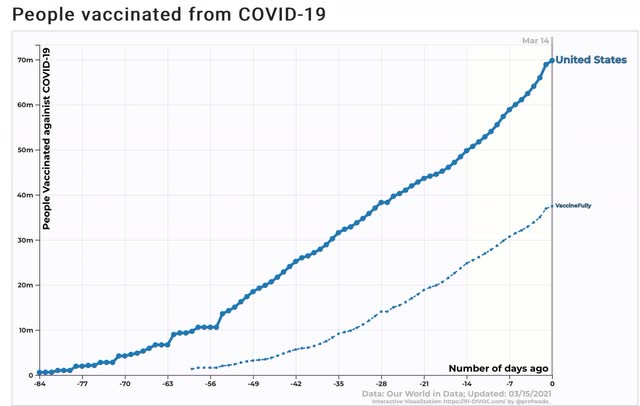
The good news is that vaccinations in the US are making better and better progress. In the past week, about 2.5 million doses were administered each day. At this rate the entire adult population could be vaccinated by the end of June.   

Here’s the total number of people who have received at least one dose (just shy of 70 million), and those who are fully vaccinated (about 37.5 million):


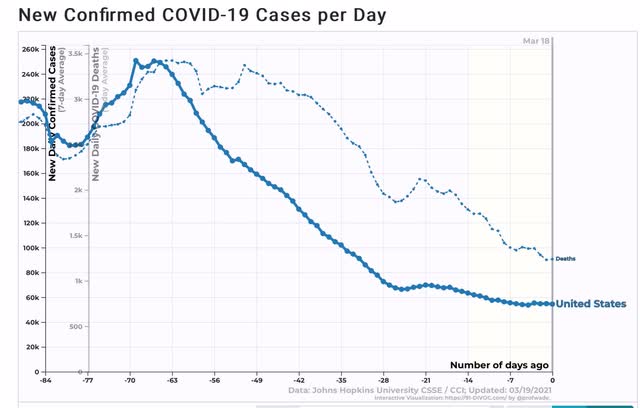
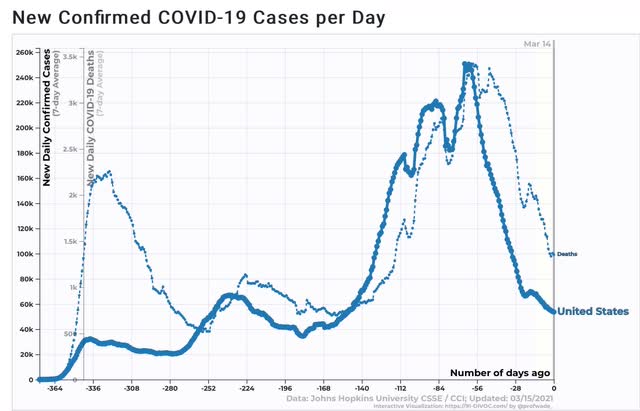
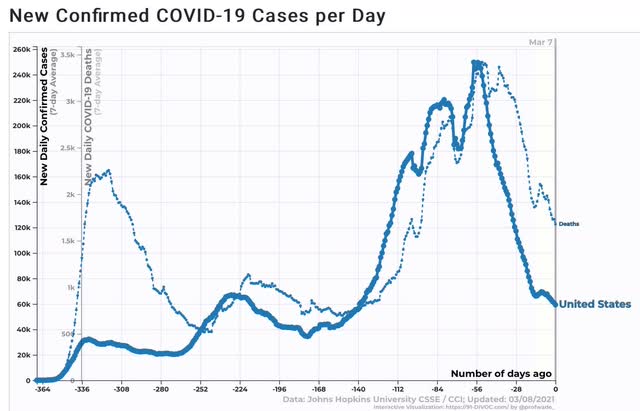
At least partly as a result, both new cases and deaths have declined by over 75% and 60%, respectively, since their wintertime peaks:


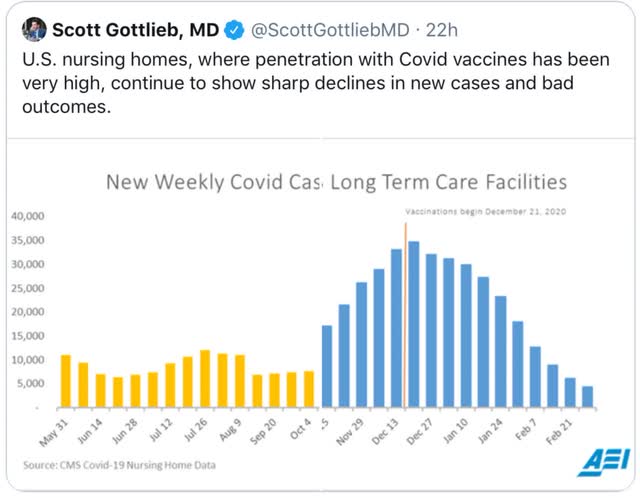
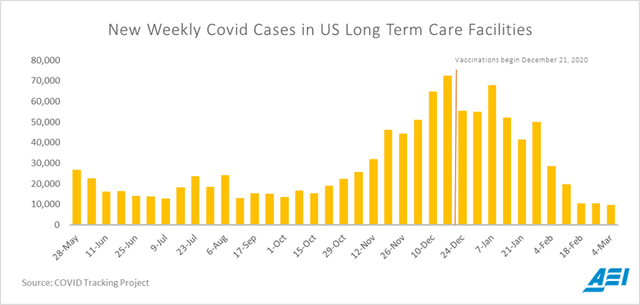
And new cases in long term care facilities have declined by about 90% to the lowest level in at least 10 months:


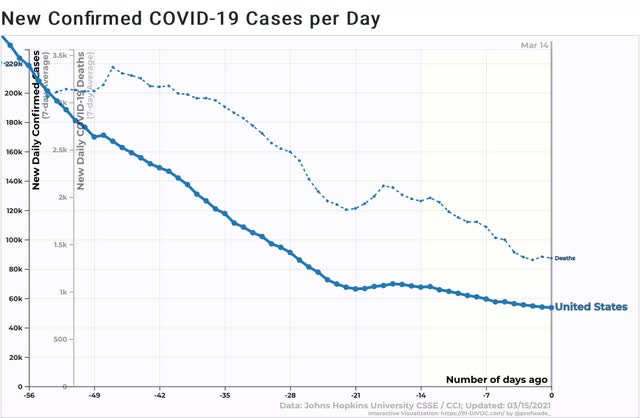
But the bad news, as Dr. Fauci has repeatedly pointed out in recent days, is that the declined are plateauing, as shown in this close-up of the past 8 weeks:


Incredibly reckless behavior by the usual government suspects, particularly the governors of Texas and Florida, is almost certainly contributing to this plateau.

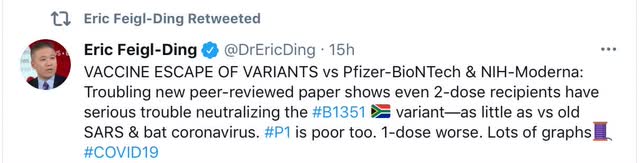
This is particularly of concern because there is at least some evidence that one of the new variants of COVID may not be inhibited by either of the two primary vaccines:


Declaring premature victory, as the governors in those two States have done, is a recipe for emergence of a mutation which evades the effectiveness of the vaccines. If this becomes a real issue, I hope Biden will not hesitate to quarantine those two States and any others (e.g., Mississippi) which are similarly reckless.

Saturday, March 13, 2021

Weekly Indicators for March 8 - 12 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

Although rising long term interest rates are likely to have consequences in 2022, 2021 is shaping up to be a blowout year for economic (and hopefully employment) growth, driven by dual huge monetary and fiscal stimuli.

As usual, clicking over and reading should bring you up to the figurative moment, and reward me just a little bit for my efforts.

Friday, March 12, 2021

January JOLTS report: during the wintertime pandemic surge, hiring hit a brick wall


 - by New Deal democrat

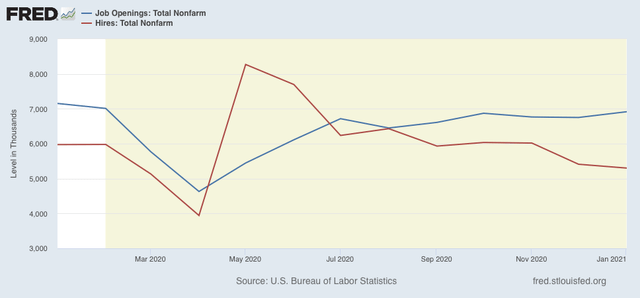
Yesterday morning’s JOLTS report for January was confirmatory of the weak jobs report for that month, showing a largely paused recovery. Further, for the second month in a row, hires were down sharply. Let’s examine this in accord with the data from the prior two recoveries covered by this report, which has only a 20 year history.

In the two past recoveries: 
  • first, layoffs declined
  • second, hiring rose
  • third, job openings rose and voluntary quits increased, close to simultaneously

What we will see below is that the big decline in hiring in December and January is a big outlier compared with the prior two recoveries. The remaining data is largely in accord with the
 pattern from the last two early recoveries: the first two data series to turn - layoffs and hires - did indeed turn, while the last two - job openings and voluntary quits -  bottomed more gradually and have since risen less dramatically.

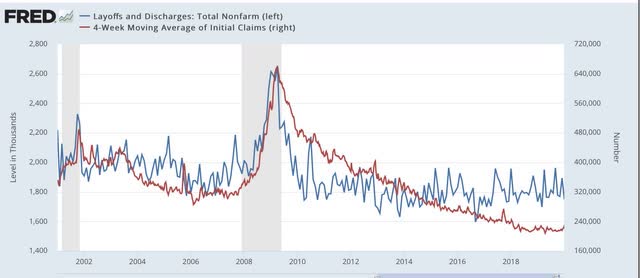
This first graph compares layoffs and discharges (blue) with the 4 week average of initial jobless claims (red) prior to this recession, for reasons of scale since March and April would be “off the charts”:


You can see that, by the end of the recessions, layoffs were already declining, and continued to decline steeply over the next 3-8 months before reaching a “normal” expansion level. The turning point coincides exactly with the much less volatile, but more slowly declining, level of initial jobless claims.

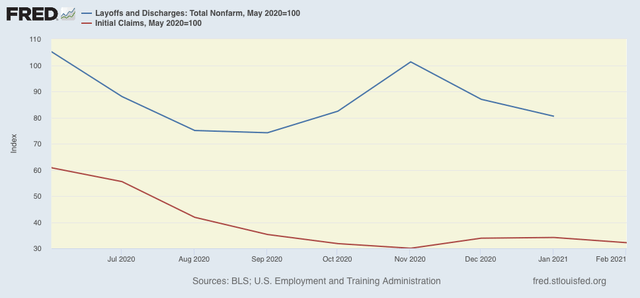
After the initial lockdown period, layoffs and discharges had already declined to their “normal” level in May, while initial jobless claims peaked one to two months later, and continued to decline (slowly) into autumn. In November, layoffs and discharges increased, then decreased in December and January, and initial claims followed suit with a one month delay: 


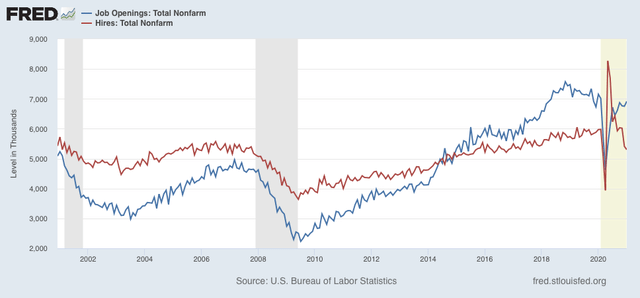
Next, here is the entire historical relationship between hires (red) and job openings (blue) through January 2021:


In the past two recoveries, actual hires started to increase one to two months before job openings.

This time around, the relationship is different. While job openings have been generally in a slow uptrend since last June, hires have reversed, stagnating and then declining sharply since last May:


Basically, there was an initial quick rebound from the lockdown periods, and then actual hiring hit a brick wall.

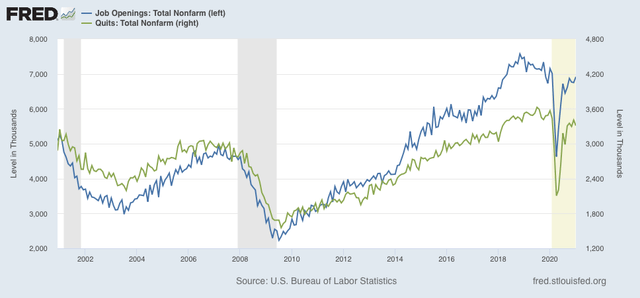
Next, here are quits (green) vs. job openings (blue): 


In the past two recoveries, openings rose first, followed by quits, suggesting it is openings that leads to the increase in voluntary quits. That has been the case in 2020 and into 2021 as well.

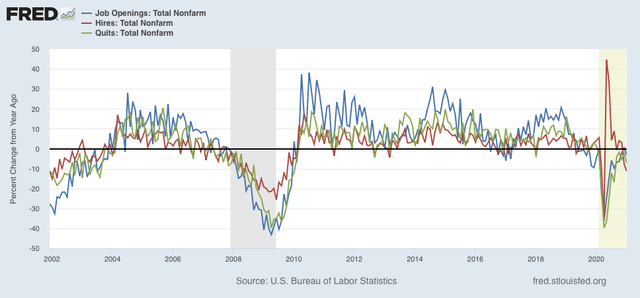
Because of the enormous moves during this pandemic year, seasonal adjustments might not be leaving us with a true picture, so here are job openings (blue), hires (red), and voluntary quits (green), measured YoY instead, for the entirety of the series up through the present:


We can see that hires rebounded first following the 2001 and 2008-09 recessions. Quits and openings moved generally in tandem with a slight lag. The same pattern generally appeared in 2020, with quits perhaps slightly lagging, until the anomalous decline in hiring in the last two months of data. Note also that job openings, as revised, were actually *higher* YoY in December.

In general, the January JOLTS report showed:

1.  A pattern generally consistent with the past 2 recoveries, with layoffs having returned to normal levels, then hiring having increased, and finally quits and openings increasing as well; BUT

2. The late autumn and early winter surge in the out of control pandemic resulted in  increasing layoffs and separations, and a sharp downturn in hiring.

Last month I concluded by saying “I am expecting a positive reversal, but not until at minimum the JOLTS report covering this month [i.e., February],  which will be released in April.” Since February’s jobs report was considerably better than either December or January’s, I continue to expect this to be the case. Further, if I am correct and there will be a sharp increase in hiring in the spring as vaccinations continue to increase and the pandemic abates, the positive reversal is likely to be quite sharp.

Thursday, March 11, 2021

New jobless claims continue to decline, just above pandemic low


 - by New Deal democrat

New jobless claims are likely to the most important weekly economic data for the next 3 to 6 months. They are going to tell us whether my suspicion that, as a critical mass of those vaccinated is reached, there will be a veritable surge in renewed commercial and social activities and attendant consumer spending, leading in turn to a strong rebound in monthly employment gains considerably greater than the roughly 250,000 we saw in February, is correct.

This week, the *relatively* good news continued. On a unadjusted basis, new jobless claims declined by 47,170 to 709,548. Seasonally adjusted claims declined by 42,000 to 712,000, only 1,000 above November’s pandemic low. The 4 week moving average declined by 34,000 to 759,000. 

Here is the close up since the end of July (these numbers were in the range of 5 to 7 million at their worst in early April): 

While both adjusted and unadjusted claims remain above their worst levels at the depths of the Great Recession, it is safe to say that the outbreak-related wintertime surge has abated.

Because of the huge swings caused by the scale of the pandemic - typically claims only vary by 20,000 or less from week to week, but since the start of the pandemic, swings of 50,000 or 100,000 per week have happened as often as not, recently I began posting the YoY% change in the numbers as well, since they will be much less affected by scale. As a result, there is less noise in the numbers, and the trend can be seen more clearly:

This is at levels last seen in November and December, and confirms that the recent increase in new claims has reversed.

Meanwhile continuing claims, which historically lag initial claims typically by a few weeks to several months, made new pandemic lows yet again this week. Seasonally adjusted continuing claims declined by 193,000 to 4,144,000, while the unadjusted number declined by 263,642 to 4,584,706:


Nevertheless seasonally adjusted continued claims remain at levels last seen in late 2010.

For the last several weeks, new jobless claims have validated my belief that with spring beginning in the warmer parts of the country, and consequent increased outdoor activities, together with an ever-increasing pool of vaccinated people, the worst of the job losses would be behind us. 

Now that further COVID relief has also been passed by Congress, I expect to see a continuing strong increase in consumer spending, which in turn will drive fewer layoffs and larger monthly gains in employment. Let me set a few objective targets: I am looking for new claims to be under 500,000 by Memorial Day, and below 400,000 by Labor Day. 

Here’s hoping I’m right.

Wednesday, March 10, 2021

February consumer inflation begins to heat up a little


 - by New Deal democrat

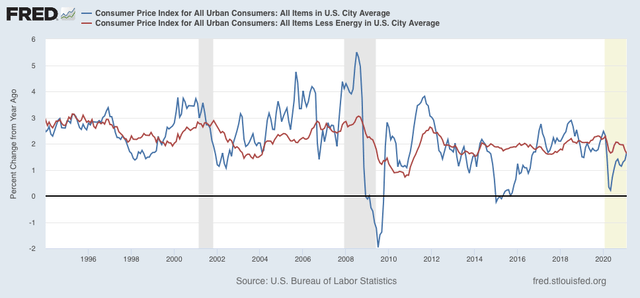
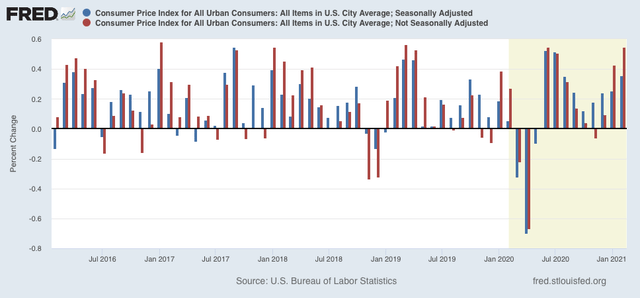
Seasonally adjusted consumer prices rose 0.4% in February. As a result, over the past several months there has been a significant uptick in YoY inflation to 1.7% from 1.1% in November. 

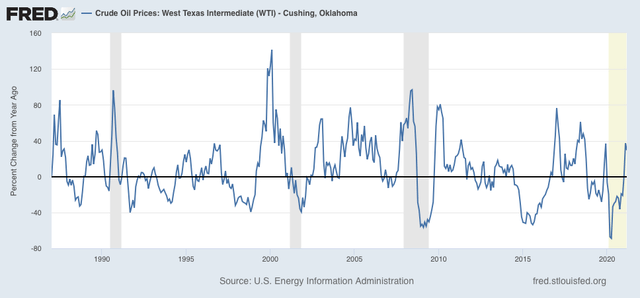
Aside from the pandemic, for the past 40 years, recessions had happened when CPI less energy costs (red) had risen to close to or over 3%/year, usually driven by increases in the price of oil by more than 40% YoY:


Despite recent increases in the price of oil, now up 30% YoY as shown in the graph below, as of this month CPI less energy is only 1.6%, showing no real price pressure at all: 

Because pandemic affects are probably influencing seasonality, below I show both the  m/m adjusted and non-seasonally adjusted change in CPI:


Here are the non-seasonally adjusted m/m% increases in prices in February for the past 5 years:

2016 +.1%
2017 +.3%
2018 +.5%
2019 +.4%
2020 +.3%

This February the non-seasonally adjusted m/m% increase was +.6%, the highest since 2005. An increase in inflation, as vaccinations take hold, the pandemic ebbs, and ever increasing numbers of people resume close to normal lives - meaning increased demand for things like travel and entertainment activities - is very likely, but unless there is a much more meaningful increase in the cost of energy, I do not see any significant cause for concern.

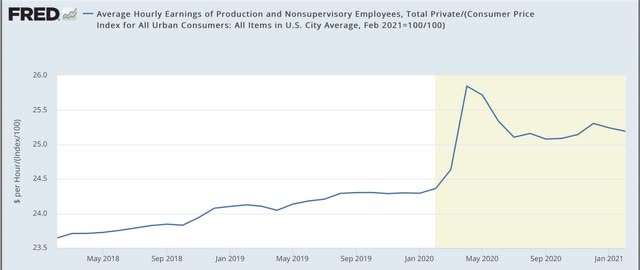
Now let’s take a look at how inflation has affected real wages. Because wages are “stickier” than prices, typically as recessions beat down prices (or at least price increases), in real terms wages rise, either during or just after a recession. That has been the case for the coronavirus recession as well. It is the “real” buying power of wages among those still securely employed during a recession that is one of the engines that usually restarts growth. 

Real wages declined -0.2% in February, and are -2.5% off their all-time high last April. Since last June they have been in a narrow range of -2% to -3% off that peak. Much of the volatility over the past year, of course, has been as a result of the skew in layoffs, which have disproportionately affected those in low-wage leisure and entertainment industries:

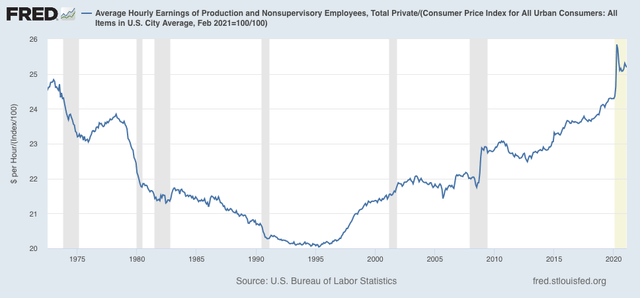
Here is the longer-term view, showing that current real wages remain above their previous 1973 peak:


A further decline in real wages as these workers are called back to employment is quite likely. That would be in accord with history, as real wages are a long lagging metric, that tend to increase long after an economic recovery has begun, and un- and under-employment fall to rates where employers must compete for relatively scarce workers.

Tuesday, March 9, 2021

Pandemic job losses: when should we begin a see a real improvement back towards “full employment”?


 - by New Deal democrat

Let’s take a deeper look at where employment stands as we begin to see the end of the pandemic in sight.


As I and many others noted last Friday, although with the exception of one month there have been job gains every month starting last May, at the pace of the last few months it would take 2 years or more just to get back to the level of employment just before the pandemic struck.

But breaking down those losses between aggregate hours and aggregate payrolls is illuminating. Here’s a look at the YoY% change in jobs, hours, and payrolls for the last 3 recessions and recoveries:
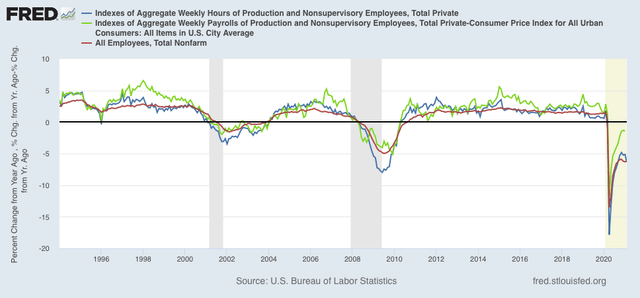

What we can see is that in both 2001 and 2008, hours were cut more than payrolls or jobs. In other words, many more employers reacted to the recessions by cutting employees’ hours rather than laying them off. That hasn’t been the case in the coronavirus pandemic. Both jobs and hours were cut by close to the same amount - I.e., employers laid off employees rather than have them work part time. What was cut far less deeply were payrolls. What this shows is that the brunt of layoffs were borne by lower wage industries. Relatively speaking, higher wage sectors were able to have their employees work from home, and avoided layoffs.

Now let’s slice up the jobs market by sectors to see where the deepest cuts have been. In all of the following graphs, I have normalized employment just prior to the pandemic (as of February 2020) to 100. Thus the graphs show the percentage of jobs lost.

Broadly speaking, employment can be broken down into goods producing and service providing sectors. The latter is by now about 6x the size of the former, which has been deeply cut by offshoring and mechanization. Here’s what that looks like for the pandemic:
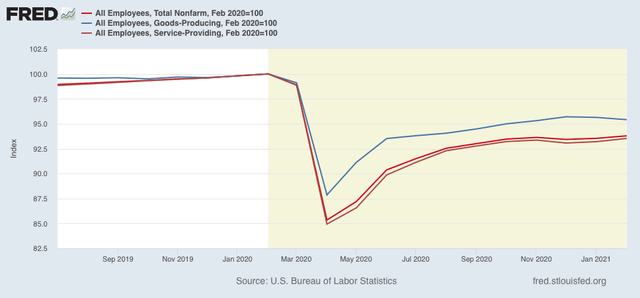

Goods producing jobs are down by “only” 4.6% as of last month, while service jobs are down 6.5%.

The two biggest portions of goods-producing jobs are manufacturing and construction, shown below along with the very leading sector of residential construction:
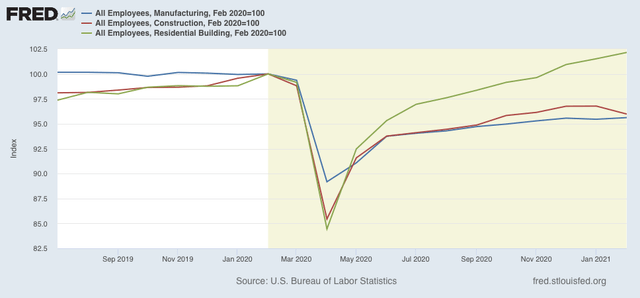

The housing boom brought about by super-low mortgage rates has enabled jobs in that sector to grow, while both construction as a whole and manufacturing are both down by roughly 4%, with losses of roughly 300,000 and 450,000 from the pre-pandemic peak, respectively.

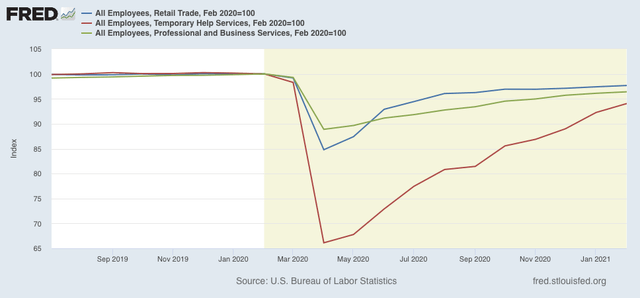
Turning to the services sector, retail trade has not been that badly hit, off 350,000 jobs or -2.3%. Temporary help, another very leading indicator for employment (employers generally hire temps first before extending full time offers), is off -6%, but this is a lower number at 175,000 jobs. The big decline is in professional and business services as a whole, off 770,000 jobs or -3.6%:

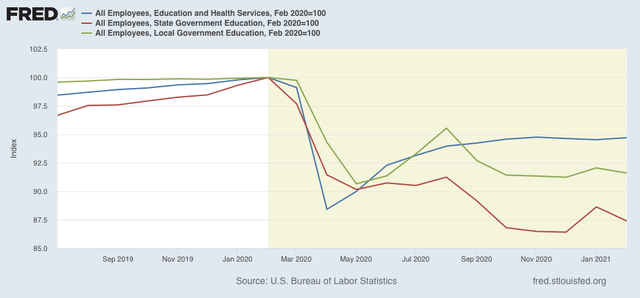
The educational sector has been a much bigger loser, off 1.3 million jobs in total, a decline of -5.3%. Local education is down -8.4%, for a loss of 700,000 jobs, and state education off -12.6%, or 350,000 jobs:

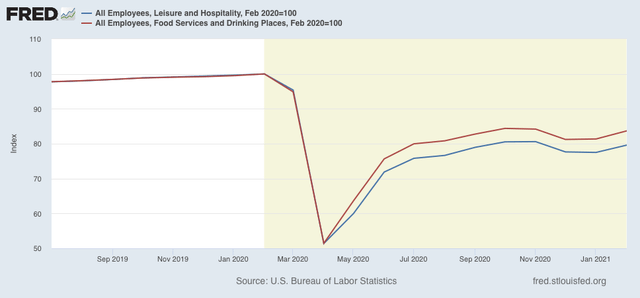
Finally, leisure and hospitality has been the hardest hit part of the economy, with a loss of about 3.5 million jobs, or over 20% of the entire employment in that sector. The food and drinking component is down -16.3%, or just over 2 million:

Putting the data together, we see that the lion’s share of the continuing losses in employment are:
- leisure and hospitality, including food and drinking -3.5 million
- education, -1.3 million
- professional and business services, -770,000
- manufacturing, -450,000
- retail trade, -350,000
- construction, -300,000

Leisure and hospitality, being an indoor activity focused on adults, and the food and drink components requiring being unmasked, is probably going to be the last sector to recover. 

Since children are mainly a concern for spreading the disease to adults, once older adults are largely immunized, the worry fades. In other words, it seems very likely that normal, or close to normal, instruction will be a able to begin in September.

The remaining big areas of losses should all start to improve in tandem with the percentage of the adult population that is immunized, so I would expect to see good improvement throughout the spring and summer. In other words, we might see substantially better jobs reports than we have seen in the past few months going forward from now through summer, and another jump with the beginning of the next school year. It would not be a surprise, though, to see a continuing slump in leisure and hospitality right through the end of the year, or until there is herd immunity (which means a large share of GOP ignoramuses getting vaccinated)
Monday, March 8, 2021

Coronavirus dashboard for March 8: update on the effect of vaccinations


 - by New Deal democrat

My first post on the coronavirus was almost exactly one year ago, on March 10, 2020, “This is what exponential growth looks like,” warning that exponential spread was exactly what had started to happen in the US.


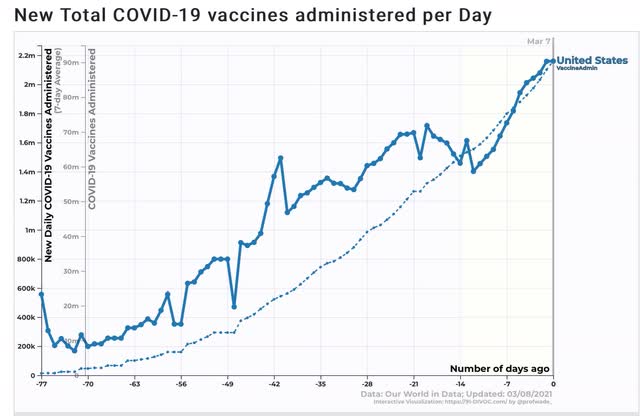
 We are now finally averaging the administration of over 2 million doses of vaccine per day, and according to the CDC almost 60 million people constituting nearly 20% of the US population have already received at least their first dose:


Nursing home cases have declined by about 55,000 per week since vaccines started to be administrated, although it is noteworthy that there has been a plateau in the past 3 weeks:


Meanwhile, the good news is that nationwide new cases are now averaging less than 60,000 daily, and deaths about 1,700, a 75% and 50% decline from recent peaks, respectively:


The bad news is that these levels are still near their summertime peaks, which was regarded as awful at the time.

I am hopeful that over the next 30 to 60 days we will see vaccinations begin to win the war against new infections and deaths, as in less than 20,000 new infections and under 1000 new deaths daily.