Saturday, April 4, 2015
Weekly Indicators for March 29 - April 2 at XE.com
- by New Deal democrat
My Weekly Indicators post is up at XE.com.
The US appears to have "imported" a near-recession limited to production and spending for the first time in over a century, while income and employment still show a good domestic economy.


Friday, April 3, 2015
March jobs report: the good streak is broken
- by New Deal democrat
HEADLINES:
- 126,000 jobs added to the economy
- U3 unemployment rate unchanged at 5.5%
With the expansion firmly established, the focus has shifted to wages and the chronic heightened unemployment. Here's the headlines on those:
Wages and participation rates
- Not in Labor Force, but Want a Job Now: down -169,000 from 6.538 million to 6.369 million
- Part time for economic reasons: up 70,000 from 6.635 million to 6.605 million
- Employment/population ratio ages 25-54: down -0.1% to 77.2%
- Average Weekly Earnings for Production and Nonsupervisory Personnel: up +0.2% from $20.82 to $20.86, up +1.8%YoY (this YoY change is a bounce from last month's +1.5%). (Note: you may be reading different information about wages elsewhere. They are citing average wages for all private workers. I use wages for nonsupervisory personnel, to come closer to the situation for ordinary workers.)
January was revised down by -38,000 from 239,000 to 201,000.
The more leading numbers in the report tell us about where the economy is likely to be a few months from now. These were generally negative for the second month in a row.
- the average manufacturing workweek declined -0.1 to 40.9 hours. This is one of the 10 components of the LEI and so will affect it negatively.
- construction jobs decreased by -1,000. YoY construction jobs are up 282,000 YoY.
- manufacturing jobs also decreased -1,000, and are up 188-,000 YoY.
- Professional and business employment (generally higher-paying jobs) increased 40,000 and is up 662,000 YoY.
- temporary jobs - a leading indicator for jobs overall - increased by 11,400.
- the number of people unemployed for 5 weeks or less - a better leading indicator than initial jobless claims - increased by 57,000 to 2,488,000, compared with December 2013's low of 2,255,000.
Other important coincident indicators help us paint a more complete picture of the present:
- Overtime decreased by 0.1 hour from 3.4 hours to 3.3 hours
- the index of aggregate hours worked in the economy fell -0.2 from 103.1 to 102.9.
- The broad U-6 unemployment rate, that includes discouraged workers decreased from 11.0% to 10.9%
- the index of aggregate payrolls rose by 0.2% to 122.1.
- the alternate jobs number contained in the more volatile household survey increased by 34,000 jobs. This represents a 2,535,000 million increase in jobs YoY vs. 3,128,000 in the establishment survey.
- Government jobs increased by 1,000.
- the overall employment to population ratio for all ages 16 and above was unchanged at 59.3%, and has risen by +0.3% YoY. The labor force participation rate declined -0.1% from 62.8% to 62.7% and is down -0.5% YoY, and is equal to its 2014 low (remember, this includes droves of retiring Boomers).
SUMMARY:
Obviously this was a disappointing report relative to the last year of reports. The headline numbers were positive or neutral, but most of the internal numbers declined. That there were downward revisions to the previous two months' numbers is also not something that happens in a robust expansion. Most of the leading indicators in the report also declined.
There were a few bright spots, as wage growth increased, and those not in the labor force who want a job now decreased. But these really just reversed last month's poor numbers.
In the longer view, while this is a bad month, I do not think the expansion itself is in danger. We are importing some of the global weakness, and the oil patch has a very focused decline, which has shown up in the initial jobless claims in the last month or two. In fact, the most noteworthy item in the report was that there have been -11,000 job losses in areas that typically support the oil and gas industries.
If we were to see a real decline of concern, it would show up in housing and vehicle purchases. We just got a good March report on vehicle sales, so the reports on the housing industry this month are of added importance.
Thursday, April 2, 2015
Chevron's 4% Dividend Is Safe
I own this. This is not a solicitation to buy or sell this security. Do your own research and come to your own conclusions.
Oil’s recent sell-off provided one of the best buying opportunities in the energy sector since the Lehman crash. Of course, the next logical question is, “what security?” I started by looking at the big, multi-national oil companies. What first attracted me to CVX was its dividend, which is currently yielding a healthy 4%. On deeper analysis, I believe the dividend is safe, making this a very attractive company, especially at current price levels.


Oil’s recent sell-off provided one of the best buying opportunities in the energy sector since the Lehman crash. Of course, the next logical question is, “what security?” I started by looking at the big, multi-national oil companies. What first attracted me to CVX was its dividend, which is currently yielding a healthy 4%. On deeper analysis, I believe the dividend is safe, making this a very attractive company, especially at current price levels.
Let’s start by
looking at the weekly chart:
Charts, however,
aren’t the whole picture. Let’s turn to
CVX’s valuation by looking at this table from Morningstar:
Turning to the
company’s financials, CVX’s balance sheet demonstrates the company is well managed. Accounts receivable has decreased from 11.24%
of assets in 2010 to the current level of 6.29%. Inventory levels have been consistently between
2.5% and 3%. The current ratio is 1.32,
giving the company a bit of financial flexibility. On the other side of the balance sheet, long
term debt is only 9% of liabilities. Value
investors should be impressed by the increase in book value, which rose from $105
billion in 2010 to $155 billion in 2014.
Although not bullet proof, CVX’s balance sheet is in good shape.
This is
fortunate, because the income statement shows some weakness. The company’s revenue fell from $254 billion in
2011 to the current level of $211 billion.
Over the same period, the cost of revenue has decreased from 66.2% to
56.4% while operating expenses have increased by the same amount. The result is net margin has consistently been
between 9%-10% for the last five years. Management
has been distributing a large minority of these earnings. The dividend payout ratio has increased from
30% in 2011 to its current level of 41%.
This is a key reason why the current dividend is safe. Top line revenue would have to fall by 40%
before the payout ratio was challenged.
With a company of this size, a drop of that magnitude is highly
unlikely.
Finally we have
the cash flow statement. Free cash flow
(operating cash flow – investment expenses) has been positive in all but one
year for the last five years. From
2010-2102, the company added $38 billion in cash before considering investment
activity; the only year of decreases saw a drop of $607 million.
To conclude, the
company is a bit undervalued. Its
balance sheet is solid, with a well-managed short-term asset position and a
reasonable amount of debt. Although
revenue has declined, it would have to drop at least 40% more to threaten the
current dividend. The company has been
cash flow positive for the 4 of the last 5 years. Finally, the 4% dividend gives the stock
built-in price support. At these levels,
CVX is buy.
Wednesday, April 1, 2015
The long leading indicators updated through Q1 2015
- by New Deal democrat
I have a new post up at XE.com.
What do those indicators that forecast the economy more than 1 year out say now?
Tuesday, March 31, 2015
Once more into the breach on wages and income since the Great Recession
- by New Deal democrat
Two articles were posted elsewhere this morning discussing wages and income during this expansion. Both have misleading aspects to a lesser or greater degree.
The first is an article by Pavlina R. Tcherneva of the Levy Economics Institute. While I do not disagree with its overall emphasis or conclusion, I do have a significant quibble, because there is one erroneous comparison which can be misleading.
Tcherneva says:
Tcherneva says:
"In the postwar period, with every subsequent expansion, a smaller and smaller share of the gains in income growth have gone to the bottom 90 percent of families. Worse, in the latest expansion, while the economy has grown and average real income has recovered from its 2008 lows, all of the growth has gone to the wealthiest 10 percent of families, and the income of the bottom 90 percent has fallen [through 2013]."
....
Consider what has happened to the incomes of the bottom 99 percent of families in the meantime. Average real income for the bottom 99 percent, which fell after the crash—from $50,400 (2007) to $47,000 (2008) —continued falling during the expansion, to $44,300 (until 2011). It finally showed a small uptick in 2012, to $44,900, but in 2013 it remained essentially flat. Thus, any “improvement” in the income distribution is not due to improvements in the well-being of the bottom 99 percent of households."
Included in the article is a graph, which is likely to see wide distribution, and which is the problem with this article:

The problem with this graph, and its description, is that it purports to measure income growth during entire expansions. But that's not quite true, since the current expansion did not end in 2013, but is ongoing. Thus the measure of the relative income shares of the bottom 90% vs. top 10% in prior expansions is not directly comparable.
To be directly, comparable, Tcherneva should have measured relative income shares during the first 4 years of each expansion. I should emphasize that, had she done so, the results would have been similar, using the Saez and Piketty tax return data, which can be found here,
Aside from technical accuracy, I am highlighting this issue because a slightly deeper look can give us much more information.
To begin with, the Saez and Piketty numbers are based on "tax units," i.e., tax filings. Thus it is very similar to, although not identical with, households. Thus the data is subject to all of the same issues that we get into when we discuss median household income - e.g., distortions based on the tsunami of Boomer retirements, and the importance of the unemployment rate (since the unemployed are counted in households and tax units, but not for purposes of median or average wages.
The second is best summed up in this graph, from Doug Short, which shows the real median income of the bottom 90% from the Saez and Piketty data, for the entire last century:

Note that income first peaked in the early 1970s, and has only exceeded that peak one time, briefly, during the tech boom of the late 1990s. Of particular interest is how long it took in each economic recovery since 1980, and also the plateauing of income in the late 1980s.
Tcherneva herself posted a graph several months ago showing what happened with the comparative incomes of the bottom 90% and top 10% from income peak to income peak:

This tells us the importance of three trends: (1) after the second Oil shock of 1979, and particularly in 1986, real gas prices fell dramatically, in contrast to the rise of gas prices from a low of $1.40 in 2009 to a high of $3.95 in 2012 and 2013; (2) household income rose dramatically in the early 1980s, despite a fall in real wages, due to the huge numbers of women entering the workforce; and (3) wage growth declines after particularly severe recessions like 1981 and 2008-09.
In short, if we want to explain Tcherneva's data, both during the current economic expansion, and over the longer term, we really don't have to look further than three things
- 1. the increase of gas prices post-Great Recession currently, and its volatility since 1974,
- 2. the decline in labor force participation rate since 2000, and its dramatic rise in the 1970s and 1980s due to women entering the workforce in huge numbers; and
- 3. the decline of labor bargaining power due to the collapse of unionization and the correlative rise of globalization.
The other article this morning deals with wages, and comes from the Cleveland Fed via Barry Ritholtz.
The purpose of the study was to determine what has happened with real wages during this economic expansion - are they stagnant or have they fallen? If so, why?
As the authors state, "This article answers the question: What fraction of recent changes in the average wage is due to changes in the occupation mix versus changes in wages within occupations?" The answer is given in the below chart:

Interestingly, the authors find that, through 2013, the jobs added in the recession have NOT been, as commonly assumed, low wage jobs, but have actually skewed towards higher paying jobs. They do find, however, that within occupations, real wages actually fell slightly.
My big problem with this article is in its explanation for the data. To begin with, it is not demographically normalized. While it is always true that old fogies retire and young whippersnappers take their places at entry level incomes, this has disproportionately been the case as Millennials move into the labor force as Boomers retire. This is likely to place some unusual downward pressure on wages.
But here is my real problem. The authors conclude:
You have got to be kidding me."Why did wages rise during the recession and fall during the recovery? It may be due to what are called “selection effects.” During recessions, firms tend to retain their most productive workers, both across and within occupations. ..."It is also possible that wages declined more in the recovery than in the recession due to what economists call “sticky wages.” Reducing real wages is one of the ways the labor market adjusts to drops in demand for labor. ..."
Wages rose during the recession because the price of gas fell was $3+ at the end of 2007 when it began and was under $2 a gallon when it ended. Wages fell from there to 2013 because the price of gas went up to $3.95 a gallon during 2012 and 2013 (red, right scale in the graph below). This translated into actual deflation during the later stage of the recession, and 3%+ inflation during 2011 (blue, left scale), while nominal wage growth slowly decelerated from 4% YoY to 1.5% YoY (green, left scale):
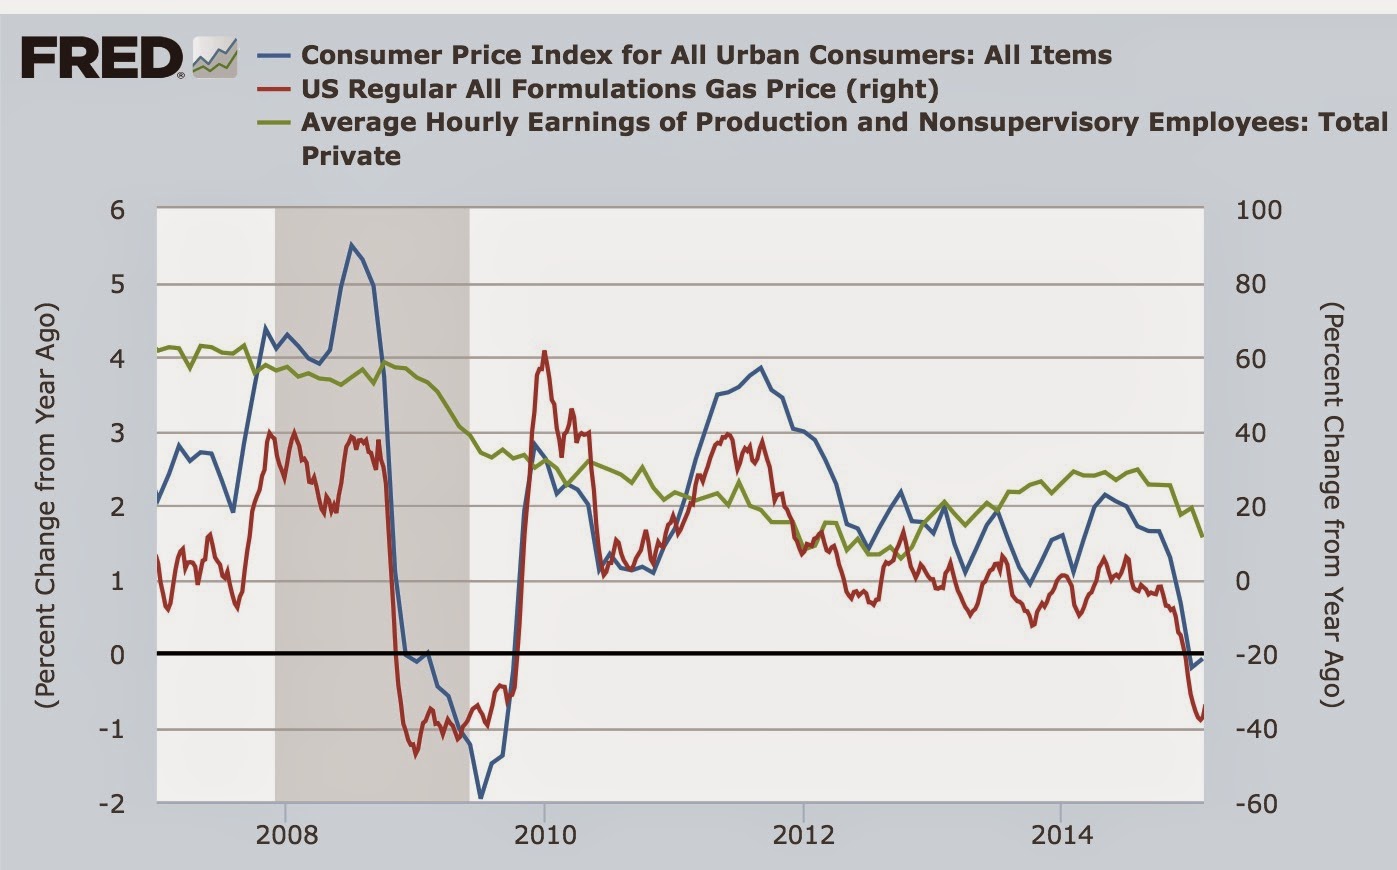
Period. End of story.
It continues to amaze me how the huge impact of the Oil Choke Collar has been almost completely overlooked.
Monday, March 30, 2015
Sunday, March 29, 2015
Saturday, March 28, 2015
Friday, March 27, 2015
Three very mixed forward looking signals from this morning's GDP revisions
- by New Deal democrat
I have a new post up at XE.com.
This morning's final revision to 4th quarter GDP actually contained 3 pieces of forward-looking news, and that news was decidedly mixed.
Thursday, March 26, 2015
Housing is still a positive for 2015
- by New Deal democrat
At the beginning of the year, I forecast continued growth, in large part due to lower mortgage rates and an improving outlook for housing.
My first update is up at XE.com. So far, so positive.
Wednesday, March 25, 2015
Kraft is a Great Company For Heinz to Purchase
Today’s
blockbuster news event was the announcement the Heinz and Kraft would
merge. Bloomberg provides a good,overarching analysis of the deal:
The deal creates a
stable of household names -- everything from Heinz ketchup to Jell-O -- with
revenue of about $28 billion. It also could presage more consolidation in the
U.S. food industry, which is struggling to reignite growth. Buffett and 3G, the
private-equity firm founded by Brazilian billionaire Jorge Paulo Lemann,
previously teamed up to buy Heinz in 2013 and they cut costs, a strategy they
aim to repeat with Kraft.
It’s impossible to argue against the logic of this
deal. Heinz, which, like Kraft, owns
numerous iconic American brands, was taken private a few years ago. Now that private equity has cut costs and
increased the company’s efficiency, the next logical business step is to go
into acquisition mode to increase the company’s product offerings and market
footprint. Not only do Kraft’s product
offerings complement Heinz’s, but the companies can potentially achieve a large
amount of synergy and cost savings from their respective positions as market
leaders in the consumer staples industry.
The deal illustrates why numerous investors still have tremendous
admiration for Buffet’s investing acumen.
Let’s take a look
under Kraft’s financial hood starting with their balance sheet. Asset structure has been remarkably consistent
for the last four years, with total assets fluctuating between $21-$23 billion
and the composition of those assets remaining near constant levels. In 2012 the company added $9.9 billion in
long-term debt. But, using their highest
interest expense and lowest EBITDA readings for the last five years, interest
coverage is still a healthy 4.74. The
current ratio stands at one. While this would
normally create a bit of concern, receivables and inventory levels are firmly
under control, indicating the company is very well managed financially.
Finally, with a large consumer staples company like Kraft, a tighter balance sheet should
be expected.
Kraft’s income
statement shows why this merger has tremendous opportunities. Top line revenue has stalled between
$18.2-$18.6 billion for the last four years.
Their biggest problem is the ease with which consumers can purchase
substitute goods -- an especially prevalent activity when overall wages have
stalled. There have also been some short-term issues. Last year the company had a
huge, 10% drop in their gross margin, which was entirely attributable to a
recalculation of pension liabilities.
Without this loss, EPS would have been 4.82. But with the loss, EPS was $1.74. While the company also had an increase in SGA
expenses, the overall level rose to one more consistent with recent history. Because Kraft and Heinz are in the same
business, the merger should create tremendous cost savings and synergy, leading to margin expansion over the
next 1-3 years.
Finally, free
cash flow to the firm has fluctuated between $1.4 and $2.5 billion for the last
five years giving the company ample
funds to self-fund all of their activities.
And their cash investing needs, which are solely derived from plant,
property and equipment investment, have been very predictable for the last five
years; they’ve fluctuated between $440 and $557 million.
Kraft was a great
company before the merger. It was the
owner of numerous brands that are a staple of the US market. The company managed its assets incredibly
well and literally printed money. Now
with the addition of another major US consumer staple company, the combination
can achieve major cost savings by eliminating duplicative operations and
achieving even larger economies of scale.
Tuesday, March 24, 2015
Five graphs to watch in 2015: second update
- by New Deal democrat
At the end of last year, I highlighted 5 graphs to watch in 2015. Now that we have all of the February reports, let's take another look.
#5. Mortgage refinancing
After a mini-surge at the end of January (light brown in the graph below), The Mortgage Bankers Association reported that refinancing applications fell back to somnolence during February, due to higher interest rates (blue) Mortgage News Daily has the graph:

Over the last 35 years, refinancing debt at lower rates has been an important middle/working class strategy. There is little room left for that strategy. David Stockman had an interesting graph last week showing that in this expansion, wage growth and consumer spending have been almost perfectly correlated. If mortgage refinancing stays turned off too long, and wages don't grow in real terms, then consumer spending falters and so does the economy.
#4 Gas prices
Here is a graph of gas prices (blue, inverted and averaged quarterly) compared with real GDP (red) over the last10 years:

Once gas prices reach a critical point, roughly $4 a gallon in present real terms, GDP falters. The cheaper gas prices are from that point, the more GDP can be expected to rise, with a slight lag. In February, gas prices rebounded as expected over $0.30 from their late January bottom. This is a typical seasonal increase and so is a neutral. All else being equal, by the 2nd quarter, this should be reflected in more positive real GDP.
#3 Part time employment for economic reasons
This is a graph of part time workers for economic reasons expressed as a percentage of the labor force:

In February this ratio continued to improve, bringing us equivalent to its levels in 1988, but still 2% (about 3 million) above the boom level of 1999 and about 1.5% (2.25 million) above the level of 2007.
#2 Not in Labor force but want a job now:

This moved in the wrong direction in February. It is now about 900,000 above its post-recession low of November 2013 (just prior to Congress's cutoff of extended unemployment benefits) and some 1.9 million above its 1999 and 2007 lows.
#1 Nominal wage growth
After an anomalous decline in average hourly wages in December, and a big positive reversal in January, wages for nonsupervisory workers were totally flat in February. Nominal wage growth YoY has now declined back to its post-recession low.

The decline in the last 6 months is troubling.
Compare our present expansion with the previous three. In the 1980s and 2000s, by the time we improved to 5.5% unemployment, nominal wage growth was approaching 3% YoY. In the 1990s expansion, at worst wage growth was on the cusp of acceleration, but was nevertheless 3.5%. Unless wage growth starts to accelerate now, the pattern is not holding.
There have been a few interesting notes about the lack of wage growth. The staff of the Federal Reserve has done a study indicating that the number of long-term unemployed plays an important role (since presumably these people are more desperate). It has also been suggested that the disproportionate (compared to normal times) percentage of relatively highly paid employees (Boomers) retiring from the labor force, and being replaced by younger workers, is holding down wages.
Two months of data into the year shows two series positive (gas prices, involuntary part time employment), and no or little improvement in the other three (refinancing, discouraged dropouts from the labor force, and nominal wage growth). Should wage growth not improve, and mortgage refinancing remain dormant, we are going to run into trouble, and I will be looking for other long leading indicators to start rolling over.
#5. Mortgage refinancing
After a mini-surge at the end of January (light brown in the graph below), The Mortgage Bankers Association reported that refinancing applications fell back to somnolence during February, due to higher interest rates (blue) Mortgage News Daily has the graph:
Over the last 35 years, refinancing debt at lower rates has been an important middle/working class strategy. There is little room left for that strategy. David Stockman had an interesting graph last week showing that in this expansion, wage growth and consumer spending have been almost perfectly correlated. If mortgage refinancing stays turned off too long, and wages don't grow in real terms, then consumer spending falters and so does the economy.
#4 Gas prices
Here is a graph of gas prices (blue, inverted and averaged quarterly) compared with real GDP (red) over the last10 years:
Once gas prices reach a critical point, roughly $4 a gallon in present real terms, GDP falters. The cheaper gas prices are from that point, the more GDP can be expected to rise, with a slight lag. In February, gas prices rebounded as expected over $0.30 from their late January bottom. This is a typical seasonal increase and so is a neutral. All else being equal, by the 2nd quarter, this should be reflected in more positive real GDP.
#3 Part time employment for economic reasons
This is a graph of part time workers for economic reasons expressed as a percentage of the labor force:
In February this ratio continued to improve, bringing us equivalent to its levels in 1988, but still 2% (about 3 million) above the boom level of 1999 and about 1.5% (2.25 million) above the level of 2007.
#2 Not in Labor force but want a job now:
This moved in the wrong direction in February. It is now about 900,000 above its post-recession low of November 2013 (just prior to Congress's cutoff of extended unemployment benefits) and some 1.9 million above its 1999 and 2007 lows.
#1 Nominal wage growth
After an anomalous decline in average hourly wages in December, and a big positive reversal in January, wages for nonsupervisory workers were totally flat in February. Nominal wage growth YoY has now declined back to its post-recession low.
The decline in the last 6 months is troubling.
Compare our present expansion with the previous three. In the 1980s and 2000s, by the time we improved to 5.5% unemployment, nominal wage growth was approaching 3% YoY. In the 1990s expansion, at worst wage growth was on the cusp of acceleration, but was nevertheless 3.5%. Unless wage growth starts to accelerate now, the pattern is not holding.
There have been a few interesting notes about the lack of wage growth. The staff of the Federal Reserve has done a study indicating that the number of long-term unemployed plays an important role (since presumably these people are more desperate). It has also been suggested that the disproportionate (compared to normal times) percentage of relatively highly paid employees (Boomers) retiring from the labor force, and being replaced by younger workers, is holding down wages.
Two months of data into the year shows two series positive (gas prices, involuntary part time employment), and no or little improvement in the other three (refinancing, discouraged dropouts from the labor force, and nominal wage growth). Should wage growth not improve, and mortgage refinancing remain dormant, we are going to run into trouble, and I will be looking for other long leading indicators to start rolling over.
Monday, March 23, 2015
Microsoft is Still a Growth Story
I do already own the company. But, this is not an invitation to either buy or sell these securities. Do your own research and figure it out for yourself.
It’s hard to
believe that a company such as Microsoft could still be considered a growth story. After all, a thirty-year old company that is
dominant in their industry is usually considered “mature” – a corporation whose
revenues grow incrementally at best. However,
this description does not apply to Microsoft which has had year-to-year top
line growth between 5%-11% since 2010. Buy-side
analysis, however, does not end here. Potential investors should avoid purchasing an
issue when solid growth is not supported by a strong balance sheet or solid
cash flow. Fortunately for potential investors
this tech company has a rock solid balance sheet and continuously strong free
cash flow. One additional factor is the
company’s current dividend yield of 2.889% and five-year history of increasing dividend
growth. When these fundamental factors
are added together, the decision to buy becomes a matter of when and not if. And, as an analysis of the chart shows, the
time to buy is now, as the security is trading about 5 points above is 1-year
low.
Let’s begin our
analysis by looking at their one-year price chart:

Microsoft rallied from May 2015 until early November, when
prices started to slowly move lower.
They consolidated in a triangle pattern from mid-December to
mid-January. Prices broke through
support at the end of January on a disappointing earnings report. Since then, they have been consolidating
between the lower and mid-40s.
At these price
levels, MSFT is slightly under-valued, as shown on this table from Morningstar:

MSFT is slightly under-valued on a PE, price/sales and price
to book level. This gives us room to
move a few points higher which is increased slightly when you consider the
company slightly outperforms their industry peers on ROA, ROE and net
margin.
Let’s turn to
their financials, starting with their balance sheet. Like most tech companies whose primary asset
is intellectual property, this is a beautiful financial document. The current ratio is 2.45 while the quick
ratio is only slightly lower at 2.24.
The company has been
keeping a close eye on receivables, with their percentage of assets dropping
from 15.1% in 2010 to 11.34% in fiscal 2014. They also keep a ton of cash handy; they’re got $85 billion on their
2014 balance sheet, with most of their holdings in short-term securities. Fundamental investors should like that their overall book value has increased from $46.175
billion in 2010 to $89.784 in 2014, which is almost a doubling in five
years. The only “drawback” is their
increased use of long-term debt, which now totals $20.6 billion. But with an interest coverage ratio of 50.8, it’s
difficult to be concerned. The balance
sheet indicates they have ample liquidity and have kept receivables
well-managed. Their near-doubling in
book value over a five year period also indicates they have shareholder
interests at heart. Finally, they most
likely tapped the debt markets to prevent a high tax bill from repatriation of
foreign holdings.
Their cash flow
statement is no less impressive. They’ve
had free cash flow to the firm of between $22 billion and $29 billion over the
last five years giving the company ample financial maneuvering room. This allows them to self-fund most small acquisitions (those
involving both companies and property) if they desire.
And finally, we
have their income statement. As
mentioned in the opening paragraph, the company is growing between 5%-11%/year. They did have a large 5% jump in COGS in
their latest annual statement. They
offered the following explanation in their 10-K: “Cost of revenue increased mainly due to higher volumes of Xbox
consoles and Surface devices sold, and $575 million higher datacenter expenses,
primarily in support of Commercial Cloud revenue growth. Cost of revenue also
increased due to the acquisition of NDS.”
This trend continued in their latest quarterly statement, increasing
COGS by 8.1%. While this is not an
optimal development, it is partially caused by their move into cloud based
computing, which most analysis (myself included) believe will provide solid
growth avenues for the foreseeable future.
In addition, there are continued costs related to the Nokia acquisition,
as they noted in their latest 10-Q: “Cost of revenue increased, mainly due to
the acquisition of NDS.” These increases
should subside in the next 4-6 quarters.
I have to admit
that I have made my fair share of Microsoft jokes, even referring to them as
the evil empire on more than one occasion.
But all kidding aside, it’s hard not to like the company. They have solid revenue growth, a very strong
balance sheet and the company literally prints money. They’ve been increasing their dividend for
the last five years, and have ample cash and potential revenue growth to
continue this practice for the foreseeable future. All these factors add up to a solid company.
Subscribe to:
Posts (Atom)