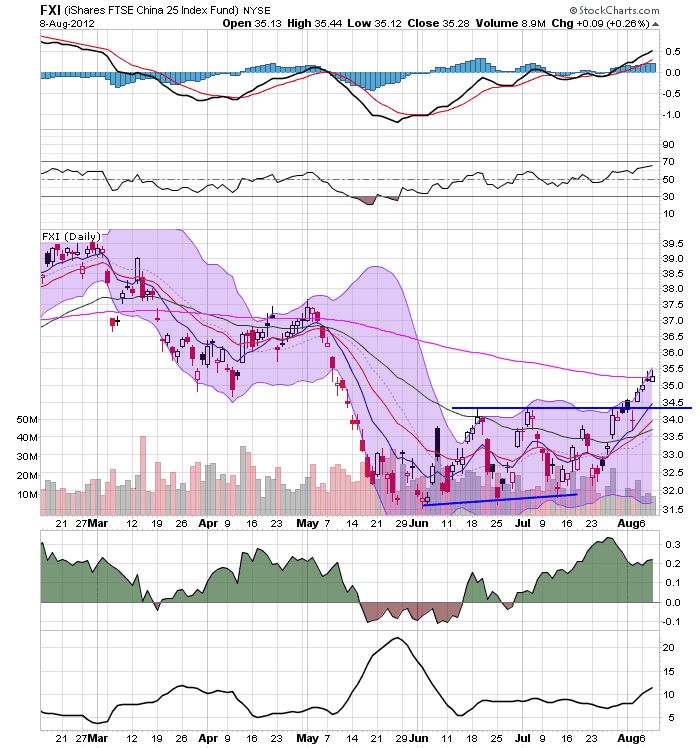
Both the Brazilian market (top chart) and Chinese market (bottom chart) have broken through resistance. The Brazilian market recently made the move; also note the rising short term EMAs (the 10 and 20 day) and that prices are above all the shorter EMAs. Also note the rising MACD and positive CMF. The Chinese market is right at the 200 day EMA. The 10 and 20 day EMAs have moved through the 50 day EMA and the CMF is positive.
The junk bond market is still in the middle of a multi-year rally. All the EMA are moving higher and momentum is positive. This move is to be expected, as the yields on treasuries are so low.
It looks like the industrial metals market is trying to bottom. We see a bottom around the 17.25/17.50 area and a descending top connecting the highs established in July. Also note the narrowing Bollinger Band numbers for July, indicating that volatility is dropping.
Oil bottomed at the end of June/beginning of July and has been rising since. Prices first hit the 200 day EMA in mid-July and is now rallying to that number again. The shorter EMAs have moved through the 50 day EMA.
Yesterday, I noted that every region in the world is being hit by a growth slowdown. The BRIC model of growth is producing diminishing returns, Europe is mired in what I believe to be their version of the US Constitutional Crisis and the US is dealing with the after-effects of a debt-deflation, economy wide credit bust. Today, I want to address what can be done about this -- if anything. Let me answer this by addressing the US' problems, followed by Asia's and than Europe's.
The US issues are actually fairly easy to deal with. Standard macro states that in the event of a credit bubble burst, counter-cyclical federal spending is in order. This will not be a new thought to readers of this blog, but it does need repeating as the "leaders" in Washington (and I use that term very liberally) are mired in their own stupidity. The US has several advantages right now: ultra-low government bond rates, a high level of blue collar unemployment and a massively out-of-date and dilapidated infrastructure. As one example of the latter, the Washington Post recently ran a story called, "Aging Power Grid on Overload As US Demands More Electricity," which noted:
The United States doesn’t yet face the critical shortage of power
that has left more than 600 million people in India without electricity
this week
But the U.S. grid is aging and stretched to capacity.
More often the victim of decrepitude than the forces of nature, it is
beginning to falter. Experts fear failures that caused blackouts in New
York, Boston and San Diego may become more common as the voracious
demand for power continues to grow. They say it will take a
multibillion-dollar investment to avoid them.
“I like to think of
our grid much like a water system, and basically all of our pipes are at
full pressure now,” said Otto J. Lynch, vice president of
Wisconsin-based Power Line Systems,
“and if one of our pipes bursts and we have to shut off that line, that
just increases the pressure on our remaining pipes until another one
bursts, and next thing you know, we’re in a catastrophic run and we have
to shut the whole water system down.”
As I've noted on more than one occasion, the American Society of Civil Engineers has given the US infrastructure a grade of "D." You also might want to watch a program called, The Crumbling of America, which ran on the History Channel, which highlights the infrastructure problems we face.
Right now the US can borrow at record low rates (the markets are, in fact, basically asking as to take their money), rebuild its infrastructure, hire a ton of unemployed manufacturing and construction workers and rekindle demand. We can also rehire a large number of teachers, police officers and other public servants who provide services we all extol but are seldom willing to pay for.
The Asian problem can initially be dealt with through a round of interest rate cuts. Consider the following levels of benchmark rates from around the region:
As the blog Money Illusions has noted in the past, the Australian central bank has been far more prone to lower rates in anticipation of coming problems, rather than waiting for the economy to falter and then act. I believe both China and South Korea also fall into that category -- banks that will and have demonstrated a proclivity to proactively manage and direct monetary policy to "lean against the wind." None of these economies are in terrible shape: China's latest Y/O/Y percentage change in GDP growth was 7.6%, Australia's was 4.3%, Taiwan's was -.16% and South Korea's was 2.4%. However, all are slowing and need an additional push which lower interest rates should help to accomplish.
The above problems are actually pretty easy to deal with -- at least for those of us writing on a blog. In practical matters, they are harder to implement because the powers that be are typically pretty useless. Now we move to the more intractable problems.
Two BRIC countries -- India and Russia -- face pretty daunting political problems that may be impossible to overcome. India's political system is mired in a level of gridlock and graft, as noted by the Economist:
But India's slowdown is due mainly to
problems at home and has been looming for a while. The state is
borrowing too much, crowding out private firms and keeping inflation
high. It has not passed a big reform for years. Graft, confusion and red
tape have infuriated domestic businesses and harmed investment. A
high-handed view of foreign investors has made a big current-account
deficit harder to finance, and the rupee has plunged.
Russia has a different problem. As recently noted by Barry Ritholtz over at the Big Picture Blog, (I'm paraphrasing here), there is no population in the world that has been more screwed over than the Russians, first by the Czars, than the communists and finally the mob. Russia was lucky in the fact that they had oil, which helped them to grow with the other BRICs. But needed reforms in the area of property rights and corruption have not been forthcoming. The country has grown since the recession, but at far slower rates (between 3.8% and 5) than their BRIC brethren. Until they pass and implement meaningful reform, they may fall back to their previous status as a country that really should do better, but can't.
China and Brazil are in an interesting situation. Both have seen tremendous growth over the last 10-20 years. But that growth is now petering out. Part of the reason for the slowdown is the overall global slowdown: China supplies manufactured goods to the developed world, while Brazil supplies raw materials to China. When the developed world slows, the demand for both country's goods understandably drops. But both also face an overall slowing growth rate, largely because of their own success; both countries now have a middle class (which was the primary object of their growth spurts) but both also face a slowing growth curve as the middle class now wants to spend a bit of its savings and enjoy its leisure. The growth of the middle class also means that international labor arbitrage is less likely to be used by corporations in moving to these countries. In addition, as China shifts to a more consumer driven economy, commodity exporters like Russia and Brazil will have lower demand for their goods.
In short, it's distinctly possible that the era of the fast growing BRICs is simply over. The situation is explained very well in this video from the Economist:
While other countries are now taking up the rapid growth mantel (Turkey, Columbia, Peru and Vietnam) these countries are simply too small to meaningfully impact world growth.
And finally, there is Europe. I previously noted that Europe is currently in a situation akin to the US under the Articles of Confederation. We have a group a states who have created a liberalized trading code between themselves, but who also lack enough centralized authority to meaningfully implement effective macro level policy. The Greek situation is a great example of this problem. Greece has been fiscally reckless for some time (as in years); their budgetary policies were usually in violation of some EU covenant. However, the central EU authority didn't have the requisite political power to stop Greece from enacting policies that violated EU dictates. So, the only way to actually solve the problem occurred when Greece was ready to default on its debt. Also consider the policy problem faced by the ECB; they have to set interest rate policy for strong countries like Germany and weak countries like Greece and Spain. In short, it's an insane proposition from a policy implementation perspective.
The EU needs to implement it's own version of the US' constitutional convention. They need to establish a new series and set of responsibilities and relationships between the central government and the individual countries. And this will mean the individual countries ceding a certain about of power to the central government. There is no other way for the group to survive without it.
In making this call, the primary objection would be that the convention could lead to a break-up of the union, which could lead to a world-wide recession or depression. I would have to concede that point on a theoretical level but not a practical. The union has already been in place for over 15 year; institutions and norms have already been developed and implemented. Integration has already taken place on numerous levels which can't be undone. In short, the union has come too far to stop now.
To sum up, we have the following propositions.
1.) The US needs to engage in infrastructure spending. Although easily conceived, practically impossible to implement considering the political players involved.
2.) The BRICs are no longer the source of massive global growth. While a lowering of interest rates in each region would help to mitigate the overall slown all the countries are experiencing, the basic model of growth in these countries is fundamentally changing. China is changing to a consumer led economic model, which is lowering its demand for commodities, thereby lowering the growth rate of other BRICs. More intractable problems in Russia, India and Brazil further hinder the possibility of a return to rapid growth.
3.) The EU has serious structural problems that need to be overcome. While their integration has come too far to be undone, the continent may lack the overall political will to meaningfully solve their problems in the short or medium term.
Put another way, muddling growth is probably here to stay for awhile.
Over the last few days, we've been watching the markets to see if the equity markets are going to start breaking out. Let's take a look at the charts to get an idea for what's happening.
The IWMs (top chart) has broken out, but the candle is very weak and volume could be stronger. On the plus side, the MACD is about to give a buy signal. The QQQs (middle chart) are by far the best chart; they've printed several days of rising prices after a move through resistance. The SPY's (bottom chart) have also moved through resistance, but, again, the bars are weak.
It's important to remember that there are ideal breakouts (those that only occur in texts and theory) and those that occur in real life in real time. The good news is two charts (the QQQs and SPY) have moved through resistance. The bad news is the charts aren't ideal. That doesn't mean the move isn't legitimate, but it does mean we'd like to see a stronger move before saying this is a legitimate break.
Let's look at the treasury market to see if we're getting any confirmation.
The IEIs (top chart) were above their trend line earlier in the week, but are now below it. The IEFs (middle chart) have made another move lower, as have the TLTs (bottom chart). Also note the continued deterioration in each respective MACD and CMF.
These three charts above add more credibility to the argument that the equity markets are moving higher.
Over the last few weeks, both NDD and I have taken a pretty exhaustive look at the world's economies. It started with my look at the Beige Book (see here for conclusion with links to various sub-parts) and NDDs look at the 2012 situation. I also looked at Asia and the EU. All of these reports had the same conclusion: growth was grinding slower. There is no sign of immediate or imminent collapse, but there is also no sign of any period of rapid growth. In short, we're stuck in the mud with no apparent way out. However, the question to ask is this: how did we get here, why is it happening and how do we get out?
It's first important to understand that we're in the middle of a post credit bubble expansion. That means we're dealing with a very different set of economic variables than a fed induced recession and recovery. In the latter, the Fed raises rates to squash inflation, and then lowers rates to stimulate growth. This is part and parcel of basic central bank theory and has been occurring for the better part of the our post WWII economic history. However, now we're dealing with a credit deflation recovery, which is characterized by far slower growth. The reason for this is actually pretty simple: consumers (who account for about 70% of US economic activity) are trying to pay down debt in addition to spending for various items. As such, consumer growth is lower, creating a demand vacuum. Until the total debt level reaches lower levels, lower consumer spending will be the norm, leading to slower growth. This fact-pattern was outlined in the Debt Deflation Theory of the Great Depression.
But there are two other contributing set of facts. The first is Europe. More has been written on this than I care to link to, but the basic problem is one of economic union without fiscal union. Put another way, goods and services now move in a far freer manner throughout the region, but each geographical unit still has tremendous fiscal control over its own affairs. It is this latter situation creating the problems as some countries (Greece) have been very reckless, while others have simply been in the wrong place at the wrong time (Spain). However, each country has just enough autonomy to make resolution incredibly difficult. Moreover, in order to realistically solve the problem, countries in general are going to have to give up a certain degree of fiscal sovereignty -- not exactly the kind of platform any politician wants to run on. But the easiest way to solve the problem (breaking up the union) is also not really in the cards as union has already come too far to stop now. And just to make the situation that much more convoluted, the politicians who should be solving the problem don't really seem to have any desire to step up to the plate and, well, solve the problems (see this commentary from Tim Duy as an example). I think the best analogy I can think of is to the US under the Articles of Confederation.
The second problem is that the BRIC method of expansion is running out of steam. It used to be that the BRIC's used their cheap labor (China and India) and abundant raw materials (Russia and Brazil) to rapidly grow, expanding the middle class and raising the respective country out of third world status. However, this model is running out of power, largely because of its overall success. China's labor costs are rising to the level where they are no longer as competitive on the world stage. India and Russia have political problems of the highest order. India's central bank has refused to lower rates despite slower growth partially because of inflation, but more so because of the government's overall intractable inability to solve big problems. Russia is still deeply corrupt to such a degree as to make expansion into the market a very dicey affair. And Brazil is slowing because its raw materials are needed to a lower degree than before because of slower growth. In short, the BRICs need to find a new model of expansion, and no one seems to be forthcoming with the next big thing.
To sum up, all major economic regions are now dealing with incredibly difficult and nuanced problems, none of which offer easy solutions. The US consumer still has to pay down his debt; Europe needs to politically integrate further (meaning each country has to give up a certain degree of sovereignty) and the BRIC countries need to find a new model of growth. None of this situations will be resolved quickly, leaving us where we started: stuck in the mud.
Remember, in the US markets, we're on the verge of seeing important downward trend breaks in the bond market and upward trend breaks in the stock markets. Let's see if these respective markets have made an major advances.
The QQQs have made a technical advance. However, notice the weak bar and weak volume reading. While no chart is perfect, this one has a fair amount to be desired.
The SPYs are in the same position; while prices have technically advanced, they really haven't made a strong enough advance from a technical perspective for this to count -- at least not yet.
And the IWMs are still contained by their downward sloping trendline.
Neither the IEFs nor the TLTs showed any meaningful downward move yesterday. Instead, prices were more or less unchanged.
So -- in short -- we're still waiting for the firm confirmation from either the stock or bond markets -- or both in tandem.
However, let me add these two charts above into the mix. Brazil (top chart) broke higher today and closed above resistance. The Chinese market (bottom chart) has clearly moved above resistance and is right below the 200 day EMA. Typically, these charts lead the US markets higher, so these are good signs.
Let's start with the Treasury curve, as there are some very important developments here. Notice that the IEFs and TLTs have both broken support. Neither have moved convincingly lower, but the break is clearly there. Both prices are right above the 50 day EMA and we see a declining MACD pattern that has been occurring for over two months. The IEIs are right at support as well. The treasury market has been taking money out of the equity markets as the safety bid has been very strong. The above charts indicates that might be ending now.
Also note the QQQs (top chart) broke out of their trading range on Friday, moving above the 65.5 level. The SPYs almost made it, but fell back at the end of trading. The charts above are not out of the woods yet; ideally we'd like to have a follow through day on decent volume.
The dollar has been trading in a range for the last tow months, moving between 22.4 and 23.1. While the dollar was the previous benefactor of the safety trade in the market, that honor is now bestowed on the Australian dollar and, to a lesser degree, the Canadian dollar.
The big monthly numbers this week were obviously the addition of 163,000 jobs in July and the uptick of the employment rate to 8.3%. July car sales held steady. Construction spending increased, especially private residential spending, yet another good sign for the housing rebound. The Case Shiller repeat sales housing price index also improved again month over month, and is very close to turning positive YoY. The ISM services report showed a slight uptick in expansion as did the Chicago PMI. Personal income rose 0.5%, as did second quarter median employment costs. Consumer confidence rose.
On the negative side, ISM manufacturing showed a very slight contraction for the second month in a row. Personal spending was flat. Factory orders declined -0.5%.
The high frequency weekly indicators are meant to be as close as we can reasonably get to observing economic trends in real time. Turns will show up here before they show up in monthly or quarterly data.
Let's start again this week with Same Store Sales, which were quite weak but remained positive:
The ICSC reported that same store sales for the week ending July 28 rose 1.8% w/w, and were up +1.7% YoY. Johnson Redbook reported a 1.1% YoY gain. Shoppertrak, did not report.
The 14 day average of Gallup daily consumer spending showed an upward spike at the end of July and at $77 was $2 over last year's $75 for this period. This is the first week of real strength after six weeks in a row of weakness. This is encouraging but we will have to see if this is just a one week outlier or if consumers are beginning to regain their footing.
Employment related indicators were also mixed to negative this week:
The Department of Labor reported that Initial jobless claims rose 12,000 to 365,000 from the prior week's unrevised figure. The four week average fell another 2250 to 365,500. The lowest 4 week average during the entire recovery has been 363,000. This number does not appear to be compatible at all with further economic weakness.
The Daily Treasury Statement showed that for July 2012, $144.0 B was collected vs. $132.2 B a year ago, an +8.9% improvement. For the last 20 days as of this Thursday, $130.6 B was collected vs. $132.1 B for the same period in 2011, an actual loss of -1.1%. It's possible that this is still being affected by the artifact of the July 4 holiday, but this will disappear next week.
The American Staffing Association Index remained at 92. This index was generally flat during the second quarter 93 +/-1. Having stayed at 92 for 2 weeks when in past years outside of the recession it was rising indicates some weakness.
The energy choke collar remains close to re-engaging:
Gasoline prices rose again last week, up .02 to $3.51. Oil prices per barrel rose slightly for the week, from $90.13 to $91.40. Gasoline usage, at 8820 M gallons vs. 9215 M a year ago, was off -4.3% The 4 week average at 8756 M vs. 9065 M one year ago is off -3.4%, still a significant YoY decline. From here on in declines in energy usage compared with last year have to be considered a sign of renewed weakness unless there is some new surprise level of efficiency compared with one year ago to explain the discrepancy.
Bond prices and credit spreads both decreased again:
Weekly BAA commercial bond rates fell .08% to 4.77%. These are the lowest yields in over 45 years. Yields on 10 year treasury bonds fell 0.5% to 1.47%. The credit spread between the two declined to 3.30%, which while still closer to its 52 week maximum than minimum, is still a significant improvement from one month ago.
Housing reports remained mixed:
The Mortgage Bankers' Association reported that the seasonally adjusted Purchase Index declined -2.1% from the week prior, and were also down approximately -1.5% YoY, back into the middle part of its two year range. The Refinance Index rose 0.8% to yet another 3 year high.
The Federal Reserve Bank's weekly H8 report of real estate loans this week fell -0.1% again. The YoY comparison declined to +0.9%. On a seasonally adjusted basis, these bottomed last September and are up +1.1%.
YoY weekly median asking house prices from 54 metropolitan areas at Housing Tracker were up + 2.2% from a year ago. YoY asking prices have been positive for 8 months.
Money supply remains positive despite now being compared with the inflow tsunami of one year ago:
M1 was flat last week, and was up +3.6% month over month. Its YoY growth rate fell to +16.5%, so Real M1 is up 14.8% YoY. M2 fell -0.1% for the week, and was up 0.9% month/month. Its YoY growth rate fell to 8.4%, so Real M2 grew at +6.7%. Real money supply indicators after slowing earlier this year, have increased again, and YoY comparisons are holding generally steady.
Rail traffic was mixed again, but the diffusion index improved:
The American Association of Railroads reported a +1.0% increase in total traffic YoY, or +5,400 cars. Non-intermodal rail carloads were down -1.5% YoY or -4400, due once again to coal hauling. Negative comparisons fell from 13 to 8 types of carloads. Intermodal traffic was up 9800 or 4.1% YoY.
Turning now to high frequency indicators for the global economy:
The TED spread rose .01 to 0.36, still close to its 52 week low. The one month LIBOR declined to 0.2440. It has retraced about 1/2 of its rise from its recent 4 month range, it remains well below its 2010 peak, and has still within its typical background reading of the last 3 years. Even with the recent scandal surrounding LIBOR, it is probably still useful in terms of whether it is rising or falling.
The Baltic Dry Index fell from 933 to 852. It is still 182 points above its February 52 week low of 670, although well below its October 2011 peak near 2200. The Harpex Shipping Index was steady last week after falling for eight straight weeks at 414. It is still up 39 from its February low of 375.
Finally, the JoC ECRI industrial commodities index fell from 117.10 to 116.70. This is still near its 52 week low. Its recent 10%+ downturn during the last few months remains a strong sign of all that the globe taken as a whole is slipping back into recession.
Weekly indicators were quite mixed. Initial claims, especially as measured over 4 weeks, are sending a good signal. Housing prices are firming. The long leading indicators of housing (especially refinancing), real money supply, and corporate bond yields also continue to be positive. Consumer sales were weakly positive. On the other hand, gasoline prices and sales are a negative. Railroad data was mixed, as were purchase mortgages, and real estate loans were negative. Shipping rates are slipping, and industrial commodities resumed their slide.
I believe we are going to see a very weak July real retail sales number. Going forward the issue as to whether we actually tip into contraction or rebound is probably going to hinge on energy prices and whether real wages turn positive enough to assist in consumer spending.
July employment was reported well ahead of expectations at +163,000. Private payrolls were up 172,000, government lost -9,000 jobs. Revisions were a wash, with May's jobs figure revised up10,000 and June's down 16,000.
The unemployment rate, however, increased to 8.3% and the broader U-6 rate increased for the second month in a row, up now to 15.0%.
The alternate, more volatile household survey jobs number actually decreased, -195,000, as those not in the labor force and the number of unemployed actually increased slightly. This brought the labor force participation rate down 0.1% to 63.7%, and the employment to population ratio down 0.2% to 58.4%.
Those parts of the labor report that tend to lead the economy were slightly positive or neutral. Manufacturing jobs increased by 25,000. Note that this seasonal adjustment may have been affected by the auto plant shutdown issue. Construction employment was up 4,000 (which, considering the last 5 years, is good).
The manufacturing work week, one of the 10 official leading indicators, was flat at 40.7 hours. Manufacturing overtime was also flat at 3.7 hours. The work week economy-wide was also flat at 34.5 hours. Another aspect of the report thought to be leading, temporary jobs, increased by 14,000.
The leading part of the unemployment data is those out of work less than 5 weeks. This declined by 99,000, and is now only about 150,000 above its low from last year. Usually going into a recession this has increased by at least 300,000 off its lows.
Average hourly earnings increased a pathetic but positive 0.1%. These have increased 1.7% in the last 12 months. Depending on how the July CPI is reported later this month, this might be the first YoY increase in real average hourly earnings in the last 18 months.
Compared with the negatively dramatic reports of the last few months, this one is relatively "meh," which under the circumstances, is a positive. In summary, more jobs were created than necessary to keep up with population growth, leading industries were positive, short term unemployment were positive. The ratio of unemployed to employed and to the population grew, a negative. Most of the rest of the report was flat, neither good nor bad.
P.S.: Appropos of my latest critique of ECRI's recession call the other day, the YoY% change in employment growth increased to a 4 month high. For the moment, this means that 3 of the 4 coincident indicators used to signal expansion vs. recession are not just growing, but growing at an increasing rate.
After rallying from mid-June to mid-Jule, the entire grains complex has consolidated gains. Corn (top chart) is using the 10 day EMA as support, while wheat (bottom chart) is probably leading the complex lower; it has broken support and is using the 20 day EMA as technical support. All have MACDs that have given sell signals. I would expect sideways to slightly downward trading for the next week or so (or until we get another adverse weather report). But, given the extent of the drought, I would expect to see prices at this elevated level for the foreseeable future.
The Australian dollar has caught a major safety bid; it has been in an upward sloping channel for the last two months. There are several reasons for this. First, Australia has a higher growth rate than most countries with a AAA credit rating. Second, it has higher interest rates. Third countries and traders are looking to diversify their holdings out of dollars and the euro.
The weekly gold chart is still showing gold trading in a very narrow range. However, notice the MACD has given a but signal. Also not the low volatility reading. Don't expect this reading to stay at this level long.
After breaking an uptrend earlier this year, copper has fallen through the 200 week EMA and been trading right below that level for the last two and a half months. Momentum is weak and money is flowing out of the market. The real key right now is the 42 price level; should that not hold, expect prices to target the lower Bollinger Band.