Saturday, July 8, 2023

Weekly Indicators for July 3 - 7 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.

A real-time daily update of inflation (based on millions of prices posted at internet sales sites among other things) has become available, and has been added to the array of coincident indicators.

The complete array remains consistent with very slow growth that has not tipped over into contraction. But despite the pent-up demand for vehicles and housing, which has stretched out this slowdown phase considerably, the best available leading indicators continue to point downward.

As usual, clicking over and reading will bring you up to the virtual moment, and reward me a little bit for my efforts.

Friday, July 7, 2023

June jobs report: deceleration conitinues, with weakest private jobs sector growth since 2020


 - by New Deal democrat


My focus remains on whether jobs growth continues to decelerate, and whether the leading indicators, particularly manufacturing and construction jobs, as well as the unemployment rate (which leads going into recessions) have meaningfully deteriorated.

In May the headlines on employment were decent if slightly weak, but hid much more weakness, while unemployment improved, but not for the best of reasons.

Here’s my in depth synopsis.


HEADLINES:
  • 209,000 jobs added, the weakest monthly number since December 2020.
  • Private sector jobs increased only 149,000. Even worse, Education and health hiring was 73,000 of that total (UPDATE: 65,200 in health, 7,200 in education. An earlier version erroneously indicated all education); all remaining private categories added only 76,000. Government jobs increased by 60,000. 
  • April was revised lower by -77,000 and May by -33,000, for a total of -110,000. The three month moving average decreased to 244,000.
  • The alternate, and more volatile measure in the household report rose by 273,000 jobs. The YoY% gain in this report is +1.9%, an increase from May but near its lowest rate since 2020.
  • The U3 unemployment rate declined -0.1% to 3.6% (still above the 3.4% low last year). The civilian labor force, the denominator in the figure, rose slightly (by 183,00), while the numerator, the number of unemployed, declined by -140,000.
  • U6 underemployment rate rose 0.2% to 6.9%
  • Further out on the spectrum, those who are not in the labor force but want a job now declilned -88,000 to 5.389 million, still well above its post-pandemic low..

Leading employment indicators of a slowdown or recession

These are leading sectors for the economy overall, and help us gauge how much the post-pandemic employment boom is shading towards a downturn.  These were mainly positive:
  • the average manufacturing workweek, one of the 10 components of the Index of Leading Indicators, was unchanged at 40.7, still down -0.9 hours from February peak last year of 41.6 hours.
  • Manufacturing jobs increased by 7,000.
  • Construction jobs increased by 23,000.
  • Residential construction jobs, which are even more leading, rose by 800. It nevertheless appears likely that January was the peak for this sector.
  • Goods jobs as a whole rose 29,000. These should decline before any recession occurs.
  • Temporary jobs, which have generally been declining late last year, declined sharply, by -12,600.
  • the number of people unemployed for 5 weeks or less declined -15,000 to 2,068,000.

Wages of non-managerial workers
  • Average Hourly Earnings for Production and Nonsupervisory Personnel increased $.13, or +0.3%, to $28.75, a YoY gain of 4.7%, the lowest YoY gain since June of 2021.

Aggregate hours and wages: 
  • the index of aggregate hours worked for non-managerial workers increased 0.2%.
  •  the index of aggregate payrolls for non-managerial workers rose 0.5%, and increased 6.2% YoY, the lowest rate since March 2021, but significantly above the inflation rate, meaning average working class families have more buying power.

Other significant data:
  • Leisure and hospitality jobs, which were the most hard-hit during the pandemic, rose only 21,000, -328,000, or -2.0% below their pre-pandemic peak.
  • Within the leisure and hospitality sector, food and drink establishments, declined for the first time since 2020, down -800 jobs, and remain-52,100, or -0.4% below their pre-pandemic peak. 
  • Professional and business employment rose only 21,000. This series has also been decelerating and is now up  2.1% YoY.
  • The Labor Force Participation Rate was unchanged at 62.6%, vs. 63.4% in February 2020.
  • The number of job holders who were part time for economic reasons rose a sharp 452,000.


SUMMARY

The headline for this report would be the typical “deceleration continues, but objectively strong” if it were not for the anemic private jobs growth. Only 76,000 private jobs were added, ex-education and health. Professional and business job growth declined to its lowest level in 3 years except for 2 months. Restaurant and bar employment actually declined, ending its strong comeback.

Further, while the unemployment rate declined slightly, this was in part due to a lackluster increase in the civilian labor force. And the underemployment rate increased to its highest level in almost a year, due in large part to a sharp increase in involuntary part time employment.

On the plus side, the leading sectors of manufacturing, construction, and employment in the goods producing sector as a whole all increased. I do not think there is going to be a recession until this sector definitively rolls over.

Thursday, July 6, 2023

May JOLTS report: continued decelerating trend, but still extremely positive


 - by New Deal democrat


Let me start out with the statement that has been my touchstone for the JOLTS report for the last year or more: for the last several years, the jobs market has been a game of “reverse musical chairs,” where there are always more chairs than participants. Those employers whose chairs weren’t filled had to increase their wage and/or benefits offerings, or go without. This was good for labor, but certainly put pressure on prices as well. Because the jobs market has remained so strong, it has been unlikely that a recession would start unless the situation with job openings returned to at least close to its pre-pandemic levels. Only then could there be enough layoffs to actually be consistent with a negative monthly jobs number.


This morning’s report for May was more of the same: the decelerating trend remained intact, but there was some month over month strength. And there hasn’t been enough of a return to pre-pandemic “normalcy” to make me think we are anywhere close to an actual negative monthly jobs print.

To the numbers: Job openings declined -496,000 to 9.824 million. This is less than 1/2 of the decline from the post-pandemic peak of 12.200 million vs. the pre-pandemic peak of 7.600 million. Hires rose 107,000 to 6.208 million, still significantly above their pre-pandemic record. And Quits rose 250,000 to 4.015 million, also well above their pre-pandemic level, but also well below their post-pandemic peak:


Here is the long-term pre-pandemic history of all three metrics for comparison:


Just to emphasize again: note the current numbers are all trending down from their post-pandemic peaks, but not close to their pre-pandemic averages or even peaks.

Meanwhile layoffs and discharges were virtually unchanged from April, at 1.585 million:


Here is their pre-pandemic history as well, showing that they are well below those levels (a positive):


Last month I wrote that “there are two overarching trends in this data:

(1) the absolute fundamentals for labor remain quite positive,
(2) but they continue to decelerate.”

That remained the case with this month’s report. While I am anticipating that the unemployment rate is likely in rise slightly in the next few months, I don’t think we are anywhere near having an actual negative jobs print.

Initial jobless claims: moving closer to a red flag warning


 - by New Deal democrat

Initial claims for jobless benefits rose 12,000 last week to 248,000. The 4 week average declined -3,500 to 253,250. With a one week lag, continued claims declined -13,000 to 1.20 million:


More importantly for forecasting purposes, initial claims are up 17.1% YoY. The more important 4 week average is up 18.1%, and continuing claims are up 27.0%:


This is the 4th week in a row that the 4 week moving average has been up by more than 12.5% YoY. 

Additionally, averaged monthly initial claims were up 18.5% for the month of June in its entirety:


This is the first month that claims have been higher YoY by more than 12.5%. If they remain higher than 12.5% for July, that will trigger a red flag recession warning. In the above graph I have also shown the YoY% change in the unemployment rate. This is a “percent of a percent.” The unemployment rate was 3.6% in June 2022. Since initial claims leads the unemployment rate, this suggests that it will rise 0.36% (or possibly more) above that rate in the coming months, or up to about 3.9%. This would not yet trigger the “Sahm Rule,” with retroactively tells us we are already in a recession, but it would be much closer.

Wednesday, July 5, 2023

MIdyear update: the state of the big monthly coincident indicators


 - by New Deal democrat


Let’s take a look at the important monthly coincident indicators that the NBER has indicated they weight most heavily, along with quarterly real GDP, in gauging whether the economy is expanding or contracting. Remember, a recession isn’t actually defined by 2 quarters of negative GDP, but rather by a significant decline in jobs, income, sales, and production.


Here is what all 5 monthly indicators look like, normed to 100 as of January, except for industrial production and real personal income less government transfers, which are normed to 100 as of their peaks last September:


Industrial production is still below its level of last September, and total real sales below their peak this past January. Real personal spending is only 0.1% higher than it was in January.

The only significant increases are to real personal income, up 0.3% since last September, almost all of it due to May; and nonfarm payrolls, which have continued to rise sharply.

And to some extent we should discount increases in real personal income and spending that are not significant. As the two below graphs show, both metrics continued to rise during the recessions of 1970. Real personal income also rose in 1970, and was flat in 1982. Real spending rose in 1960, 1970, and 1982, and 2001 as well:


In other words, about half the time real income and spending were flat or even increased during the recessions of the past 60 years.

Subject as always to revisions, with the exception of nonfarm payrolls, which obviously remain very positive, the economy was a lot closer to recession during the first half of this year than most observers acknowledge.

Coronavirus update: mid year 2023


 - by New Deal democrat


I haven’t done an update on the state of COVID since March or April. As we are halfway through the year, and just past the July 4 holiday get-togethers that sparked summer waves in the past, let’s take a look. Covid isn’t gone, but it is very much in a lull.


Almost all case tracking by governments is gone. But Biobot’s wastewater monitoring, which has been very reliable, continues. And it shows that COVID particles per milliliter in wastewater is down to levels only previously seen in April through mid-July 2021, and March 2022 (the data in 2020 is sparse, so I am discounting that):


There has been an uptick since June 21, but nothing significant yet.

Hospitalizations as of the last week reported, June 28, were just below 6300, or only 900 per day, an all time low:


Similarly, deaths for the week of June 3, the most recent week for which death reports have been fully updated, were just below 630, or only 90 per day, also an all time low:


Although I don’t have a graph right now, the demographics of serious illness and deaths have continued to focus on the most elderly, and the unvaccinated. At this point anyone under age 50 who is fully vaccinated has almost no risk.

The XBB variant and its progeny (including E.U.1.1. and F.E.1.1) continue to account for about 99% of all cases:


There is simply no sign of any new significantly different variant creating any kind of wave.

If we don’t see a significant rise in cases in the next 10 days, then we have successfully had our first July 4 since 2019 with no outbreak.

In summary: COVID isn’t gone, but right now it is pretty somnolent.

Tuesday, July 4, 2023

A brief essay for July 4, 2023


 - by New Deal democrat


Selections from Brutus, the anti-federalist who argued against the Constitution’s institution of the Supreme Court:


“When great and extraordinary powers are vested in any man, or body of men, which in their exercise, may operate to the oppression of the people, it is of high importance that powerful checks should be formed to prevent the abuse of it.

“[T]hose who are to be vested with [the judicial power in the US Constitution], are to be placed in a situation altogether unprecedented in a free country. They are to be rendered totally independent, both of the people and the legislature, both with respect to their offices and salaries. No errors they may commit can be corrected by any power above them …

“[Indeed,] the judges under this constitution will control the legislature, for the supreme court are authorized in the last resort, to determine what is the extent of the powers of the Congress....

“[In] their decisions they will not confine themselves to any fixed or established rules, but will determine, according to what appears to them, the reason and spirit of the constitution.

“[T]hey will be interested in using this latitude of interpretation. Every body of men invested with office are tenacious of power; ... this of itself will operate strongly upon the courts to give such a meaning to the constitution in all cases where it can possibly be done, as will enlarge the sphere of their own authority. ....

“This power in the judicial, will enable them to mould the government, into almost any shape they please.”

Mark A. Lemley, “The Imperial Supreme Court,” Harvard Law Review, 2022:

“Armed with a new, nearly bulletproof majority, conservative Justices on the Court have embarked on a radical restructuring of American law across a range of fields and disciplines. Unlike previous shifts in the Court, this one isn’t marked by debates over federal versus state power, or congressional versus judicial power, or judicial activism versus restraint. Nor is it marked by the triumph of one form of constitutional interpretation over another. On each of those axes, the Court’s recent opinions point in radically different directions. The Court has taken significant, simultaneous steps to restrict the power of Congress, the administrative state, the states, and the lower federal courts.…

“[T]he Court has begun to implement the policy preferences of its conservative majority in a new and troubling way: by simultaneously stripping power from every political entity except the Supreme Court itself. The Court of late gets its way, not by giving power to an entity whose political predilections are aligned with the Justices’ own, but by undercutting the ability of any entity to do something the Justices don’t like. We are in the era of the imperial Supreme Court.”

Selections from the Declaration of Independence:

“A[n authority] whose character is thus marked by every act which may define a Tyrant, is unfit to be the ruler of a free people.

“[A]ll men are created equal, that they are endowed by their Creator with certain unalienable Rights, that among these are Life, Liberty and the pursuit of Happiness.--That to secure these rights, Governments are instituted among Men, deriving their just powers from the consent of the governed, --That whenever any Form of Government becomes destructive of these ends, it is the Right of the People to alter or to abolish it, and to institute new Government, laying its foundation on such principles and organizing its powers in such form, as to them shall seem most likely to effect their Safety and Happiness.“

Monday, July 3, 2023

Manufacturing and construction sectors continue downward pull on economy


 - by New Deal democrat


As usual, we start the month with new manufacturing and construction data.


The ISM manufacturing index goes all the way back to the 1940s, and has been a very good short leading indicator of recession throughout that time (although nothing’s perfect!). However, since the “China shock” started 20 years ago, with so much offshoring of manufacturing, it has less weight both for the economy as a whole, and for the percentage of people employed in the sector. Thus it carries less weight now than it did before. In particular, several times in the past 10 years it has been at recessionary levels without any broad based turndown spreading beyond manufacturing.

So far, the same has been true this year. In June, the overall index declined another -0.9 to 46.0 (any score below 50 indicating contraction. The more leading new orders index improved, in the sense of getting less bad, rising from 42.6 to 45.6 - meaning continued contraction, but at a slower pace:


These continue to be plainly recessionary numbers for the manufacturing sector. 

The issue remains, how much will the weakness spread?

Some indication is given by this morning’s other report, for May: construction spending.

On a nominal basis, total spending rose 0.9% from April. The more leading residential construction spending rose 1.5% nominally for the month, but this was after steep downward revisions for earlier months:


But, the cost of construction materials rose 1.2% in May, meaning that inflation-adjusted total spending actually declined -0.3%, and real residential construction spending only rose 0.2%:


The bottom line is that both sectors continue to pull downward on the US economy, which is increasingly being buoyed by services spending, which is a coincident but not leading sector.

Sunday, July 2, 2023

Weekly Indicators for June 26 - 30 at Seeking Alpha


 - by New Deal democrat


My “Weekly Indicators” post is up at Seeking Alpha.


Movement among the indicators continues to be slow as molasses, but an important bifurcation stands out: indicators focusing on services continue to show good growth, while indicators focusing on goods are either stalled or outright contracting.


As usual, clicking over and reading will bring you up to the virtual moment as to the state of the economy, and bring me a little pocket change for lunch money.

Friday, June 30, 2023

Real income continues to set records, while real spending and real total sales falter


 - by New Deal democrat


Real personal spending faltered in May, and real total sales continued to falter in April, as of this morning’s report; while real personal income continued to be aided by the big decline in gas prices that started a year ago.


Let me start with the good news.

Real personal income less government transfer receipts is one of the important coincident metrics watched by the NBER. And it rose 0.3% in May to a new record high:


It is 2.0% higher than before the pandemic, and 1.1% higher than last year in May when gas prices were approaching $5/gallon. 

Real disposable personal income (not shown) also rose 0.3%.  And real personal income by itself (blue in the graph below) also rose 0.3%, and is 3.7% higher than it was just before the pandemic.


Now let me turn to the bad (or just ‘meh’) news. 

Real personal spending (red above) declined less than -0.1%, rounding to unchanged. Although it is 8.1% higher than just before the pandemic, it is up only 0.1% in the four months since January. On a YoY basis, it is still up 1.1%, but in the 50 years before the pandemic, such a YoY showing usually happened only as the economy was entering a recession:


Further, remember that real personal spending on services has a long history of rising many months into, and sometimes all the way through, recessions (and indeed was up another 0.2% in May to another record high). But real personal spending on goods, similar to real retail sales, tends to be a short leading indicator, and in particular a short leading indicator for employment growth.

And there, the news was not good, as real spending declined -0.4% for the month, and is down -0.9% since its recent peak in January.


Finally, the personal savings rate increased 0.3% to 4.6%, tied for an 18 month high with March. Here is the long-term historical record:


The savings rate tends to increase in the months before recessions as consumers get more cautious.

The bad news continues in the other metric updated this morning, real total sales (including manufacturing, wholesale, and retail sales) for April, which declined -0.2%, and is down -1.6% from its January peak:


So to recap: all of the real personal income metrics improved, in some cases to new all time highs. Barring revisions, this will likely be enough, along with payroll growth, to signal that the economic expansion is still continuing. This also reflects the continued tailwind from lower gas prices - a tailwind that is very likely to disappear over the course of the next six months. But total real spending, real spending on goods, the personal savings rate, and real total business sales were all unchanged or worse. Several of these are short leading or coincident indicators of recessions. 

Thursday, June 29, 2023

Initial jobless claims: still at distress levels, still not red flag recession warning


 - by New Deal democrat


Initial claims dropped -26,000 last week to 239,000, the top of their former range this spring. The more important 4 week moving average rose 1,500 to 257,500, a new 18 month high. With a one week lag, continuing claims declined -19,000 to 1.742 million:


For forecasting purposes, the more important comparison is YoY. By this metric, initial claims were up 12.2%, and the more important 4 week average up 18.8%. Continuing claims were up 30.0%:


Remember that, based on 50+ years of history before the pandemic, the dividing line for a “recession warning” is the 4 week or monthly averages being up 12.5% for 2 months in a row. One year ago the 4 week average was in the vicinity of 215,000. 12.5% above that is 243,000. So whether the recent spike is a false alarm or not depends on whether in the coming weeks initial claims are closer to the 260,000 level, or revert back to their prior range of 230,000-240,000.

Although I won’t post a graph this week, this continues to imply that the unemployment rate will rise slightly from one year ago. But it isn’t nearly enough to come close to triggering the Sham rule for recession nowcasting.

So stay tuned.

Wednesday, June 28, 2023

Pent-up demand and sales: an update


 - by New Deal democrat


There’s no big economic news today.


So while we wait to see if initial jobless claims continue to worsen tomorrow, and what happens with real personal spending and income, as well as real business sales on Friday, let me point you to an updated detailed discussion of why the Fed’s rate hikes haven’t yet caused the economy to turn down (hint: gas prices plus pent-up demand in several crucial sectors), at Seeking Alpha.

Additionally, as I discuss in that article, the evidence is simply compelling that leading manufacturing indicators do not have the importance that they used to before the “China shock,” i.e., the offshoring of much of the previous US-based manufacturing to China that began almost 25 years ago.

This means that consumption, which is about 70% of the entire economy, has assumed greater importance. Lance Roberts (whose economic analysis I usually find facile and ideologically motivated) nevertheless deserves credit for positing that an economically weighted average of the ISM manufacturing and non-manufacturing index is now more useful. And here it is:


On that same subject, I’ve been watching the weekly update of Redbook’s consumer spending measure like a hawk since at least the beginning of this year, because it has strongly suggested that consumer spending on goods peaked probably late last year. Because it is a nominal index, it doesn’t account for inflation, but nevertheless I’ve been waiting for it to cross the zero threshold. It’s been like watching paint dry, and it continues to tantalize:


The last 4 weeks have all seen YoY readings of less than 1%. The average is presently +0.6%.

We’ll get a much more complete picture, updated through May, on Friday.

Tuesday, June 27, 2023

Higher new home sales, with lower prices in May: good!


 - by New Deal democrat


Let me start with my usual caveat about new home sales: while they are the most leading of all housing metrics, they are very noisy and heavily revised.


With that out of the way, the bottom line is that they offered pretty definitive evidence that sales have bottomed, while prices are still declining, at least on a YoY basis. Which makes sense, because as I always sale, prices follow sales.

First, here are seasonally adjusted new home sales (blue, left scale) compared with the less leading, but much less noisy single family permits (red, right scale):


Both now show a significant and apparently sustained rebound from their respective lows last summer and winter. Unless the Fed jacks up rates further enough to drive mortgage rates well over 7%, the bottom certainly appears to be in.

Nevertheless, a longer term view shows that even with this rebound, new single family houses are being built and are for sale at no more than a moderate pace compared with the last 30 years:


Note that neither of these metrics include multi-family units, which as I discussed last week, are being built at an all-time record.

Turning to prices, which follow sales with a lag, there was a non-seasonally adjusted increase of 3.5% for the month (blue, right scale below), while on a YoY basis, prices declined -7.6% (red, left scale):


This was simply a very good report for the economy: lower prices and higher sales. Good!

House prices increase for third straight month, but Case Shiller index now negative YoY


 - by New Deal democrat


Seasonally adjusted house prices through April as measured by both the FHFA (red in the graph below) and Case Shiller (blue) Indexes rose, the former by 0.7% and the latter by 0.5%. This is the third straight increase in a row. Thus house prices have probably bottomed. But on a YoY basis, prices have continued to decelerate sharply, with the FHFA index only up 3.1%, and the Case Shiller index actually showing an outright decline for the first time, down -0.3%:


House prices are nevertheless presently increasing at among their lowest YoY rates in the past 25 years. Only during the Great Recession and its aftermath were they lower.

This continues to imply a further deceleration in shelter inflation in the CPI, as shown in the below graph which compares the current Case Shiller reading (/2.5 for scale) with Owners’ Equivalent Rent in the CPI:


The only question in my mind is how long OER remains at its current plateau of +8.0% YoY before it begins to decline sharply. I continue to think we will see shelter inflation in the CPI of only about 2% by the end of next winter.

I will report on new home sales separately later today.

Saturday, June 24, 2023

Weekly Indicators for June 19 - 23 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.

When nothing dramatic is happening, high frequency information can be like watching paint dry. That’s where we are at the moment. The positives - like improving sentiment in the stock market - are still positive; and the negatives - like interest rates and mortgage applications - are still negative. And the stuff on the cusp of changing from one to the other - is still on the cusp.

As usual, clicking over and reading will bring you up to the virtual moment on the data, and provide me with some lunch money.

Friday, June 23, 2023

Back to the basics: how do initial claims, total hours worked, aggregate real payrolls, and job growth relate?


 - by New Deal democrat


One of the most important reasons why big Fed rate hikes and big downturns in things like housing starts and credit provision haven’t translated into a recession this year (so far!) is the big decline in gas prices in the second half of last year. This big decline has translated into income and spending gains across the board for American households.


To give an idea of this impact, below I show gas prices for the past 8 years (blue, right scale) contrasted with real disposable personal income (red, left scale):


Gas prices went from $3.25/gallon to $5/gallon in the first half of last year due to Russia’s invasion of Ukraine. And then, as Europe successfully weaned itself from Putin’s gas, prices went right back down to $3/gallon last December. Since then they’ve gradually increased back up to about $3.50/gallon. Not coincidentally, real disposable personal income declined in the first half of last year, bottomed in June, and has increased ever since.

But this month will be the last month for those virtuous YoY comparisons, which will gradually become more challenging through this December. My suspicion is, this will put a damper on declining inflation. It may not start to accelerate again, but it may stall and is at least likely to decelerate at a more attenuated rate. Meaning consumer finances are likely to eat a little more challenging as well (not to mention the Fed’s apparent intention to hike interest rates once or twice more).

That’s why I have been focusing on the next shoe likely to drop, which is real spending on consumer goods. To recapitulate, typically early in recoveries real average hourly wages increase, leading to increased real spending. With more demand for goods, commodity, producer, and consumer prices increase. Ultimately they overtake wage growth, prompting consumers to cut back. A consumer recession ensures. 

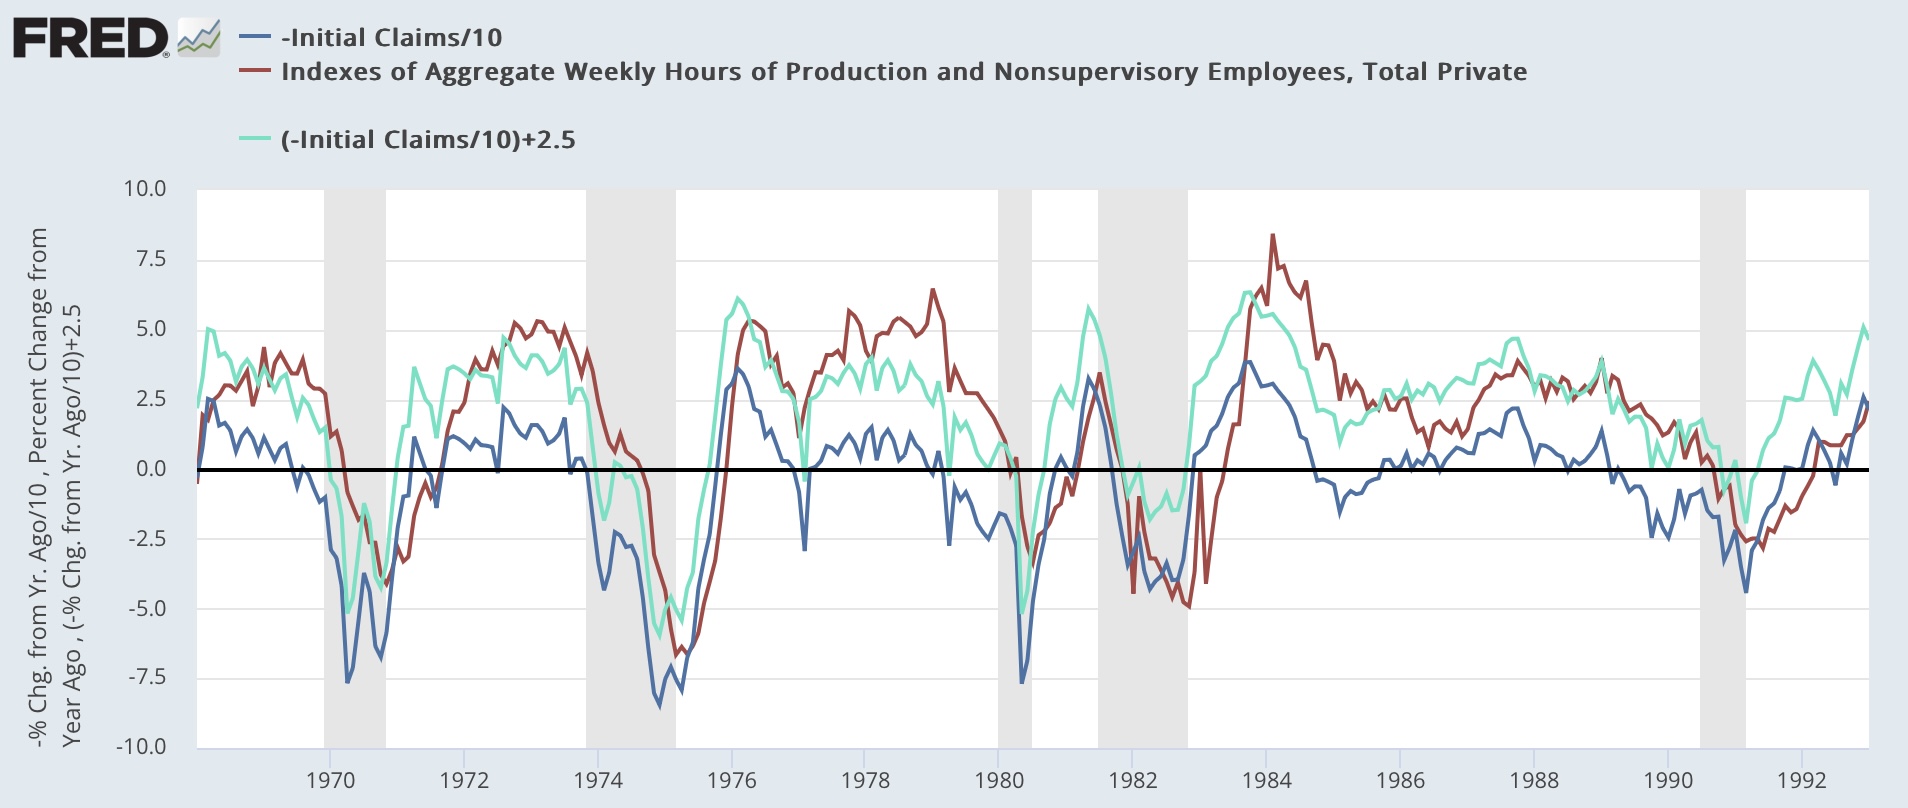
Yesterday I updated the comparison of initial claims and the unemployment rate. As I again noted, initial jobless claims are a short leading indicator, and specifically lead the unemployment rate. Meanwhile, jobs are a coincident indicator, one of the most important ones. But there are several other job-related metrics, namely total hours worked and real aggregate payrolls. Today I wanted to refresh how they relate to initial claims and to job growth.

Let’s start with how initial claims (dark and light blue, inverted and /10 for scale in the graphs below) relate to aggregate real payrolls. Real aggregate payrolls turning negative YoY have been a good coincident indicator for the onset of recessions going back 50 years. Since initial claims lead, they ought to lead real aggregate payrolls, and in the below graphs, they do, as shown by the comparison of the dark blue and red lines - the dark blue line crosses 0 to the downside first.


But by how much? That’s where the light blue line comes in. What the graphs above show is that typically initial claims have had to increase YoY by between 20% and 25%, averaging up 22.5%, to coincide with when real aggregate payrolls turn negative YoY. So let’s look at the current situation:


As I indicated yesterday, there are still two more weeks of June claims reports, so the final point in the dark and light blue lines above may change. But as it stands now, real aggregate payrolls look likely to resume their decline to 0 YoY.

Next, let’s compare real aggregate payrolls with aggregate hours worked. The below graph shows that the two have typically risen and fallen coincidentally, although sometimes (the 1970s, 1990) aggregate payrolls decline YoY first:


Here is the present situation:


Again, the two declined more or less in tandem. The jury is out on whether the recent rebound in real aggregate payrolls is noise or not. As I wrote above, I expect inflation comparisons to get more challenging after June, so my bet would be on noise.

Finally, let’s look at aggregate hours vs. jobs. As shown below, historically aggregate hours have declined YoY first, before jobs:


Here is the present situation:


As per past history, so far aggregate hours have decelerated towards 0 faster than the number of jobs. This makes sense, since we would expect employers to cut hours before they actually cut employees. And indeed, note that total hours worked rises and falls much more than actual jobs gained or lost.

So, to recapitulate: if the deceleration in YoY inflation abates, after the increase in initial claims (already at the red line, although not for long enough yet to warrant a warning), next I would expect real aggregate payrolls to to resume their deceleration, and to turn negative once claims hit about 20%-25% higher YoY. Coincident with or shortly after that, I would expect aggregate hours worked to turn negative YoY. By this time we would already be in recession. Finally, well into a recession, jobs would turn negative YoY.

Thursday, June 22, 2023

Initial claims: yellow caution flag turns more orange


 - by New Deal democrat


Initial claims, which were one of the most positive indicators of all last year, have turned darker in the last several months, and are edging closer to triggering their recession warning levels.


Claims were unchanged at a revised 264,000 last week, the highest level in over 18 months. The more important 4 week average rose 8,500 to 255,750. Continuing claims, with a one week delay, fell 13,000 to 1.759 million:


On a YoY% basis, claims are up 22.2%. The more important 4 week average is up 19.5%, and continuing claims are up 30.3%:


Here’s what the history of the 4 week average and continuing claims YoY levels look like, with the present values normed to 0 for easy comparison:


With the exception of 1989, and 4 week periods in February 1977 and May 1979 (the former likely weather, and the latter due to a strike), the 4 week average has never been this much higher YoY without a recession having begun. For continuing claims, there are no exceptions at all.

Because initial claims lead the unemployment rate, here is their historical YoY comparison with claims averaged monthly (note initial claims/20 for scale):


Here is the same comparison for the past 18 months:


It is important to note that there are still 2 more weeks left of June claims, so the last value is likely to change significantly. But if it were to continue at the present level, it would imply the Sahm Rule (a reliable early nowcast confirmation of a recession; black in the graph below) being triggered or close thereto within the next few months:


Bottom line: no red flag triggered yet, but the yellow flag caution is looking more orangey..