Saturday, June 5, 2021

Weekly Indicators for May 31 - June 4 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

On the one hand, it’s amazing just how positive the indicators are almost across the board - including long term Treasuries getting relaxed about the inflation scare.

On the other hand, the surge in commodity prices looks like it’s about to bite corporate profits in the rear quadrant.

Also, I’ve tried out a new summary spreadsheet format which should make the concluding information easier to read.

As usual, clicking over and reading will bring you up to the virtual moment on the economy and the forecast. And it will reward me with my lunch money for next week.

Friday, June 4, 2021

May jobs report: almost all positive, but not good enough


 - by New Deal democrat

HEADLINES:
  • 559,000 jobs added: 492,000 private sector plus 67,000 government. The alternate, and more volatile measure in the household report indicated a gain of 444,000 jobs, which factors into the unemployment and underemployment rates below.
  • The total number of employed is still 7,629,000, or 5.0% below its pre-pandemic peak.  At the rate jobs have grown this year, it will take another 12 months for employment to completely recover.
  • U3 unemployment rate declined -0.3% to 5.8%, compared with the January 2020 low of 3.5%.
  • U6 underemployment rate declined -0.2% to 10.2%, compared with the January 2020 low of 6.9%.
  • Those on temporary layoff declined -291,000 to 1,823,000.
  • Permanent job losers declined -295,000 to 3,234,000.
  • March was revised upward by 15,000, while April was revised upward by 12,000, for a net gain of 27,000 jobs compared with previous reports.
Leading employment indicators of a slowdown or recession

These are leading sectors for the economy overall, and will help us gauge how strong the rebound from the pandemic will be.  These were mainly positive: 
  • the average manufacturing workweek increased 0.1 hour to 40.5 hours. This is one of the 10 components of the LEI.
  • Manufacturing jobs gained 23,000. Since the beginning of the pandemic, manufacturing has still lost -509,000, or 4.0% of the total.
  • Construction jobs declined -20,000. Since the beginning of the pandemic,  -225,000 construction jobs have been lost, or 2.9% of the total.
  • Residential construction jobs, which are even more leading, rose by 4,400. Since the beginning of the pandemic,  32,400 jobs have been gained in this sector, or 3.9%.
  • temporary jobs rose by 4,400. Since the beginning of the pandemic, there have still been -294,100 jobs lost, or 10.0% of all temporary jobs.
  • the number of people unemployed for 5 weeks or less declined by -391,000 to 2,023,000, which is  -59,000 *less* than just before the pandemic hit.
  • Professional and business employment increased by 35,000, which is still -708,000, or about 3.3%, below its pre-pandemic peak.

Wages of non-managerial workers
  • Average Hourly Earnings for Production and Nonsupervisory Personnel: rose $0.14 to $25.60, which is a 2.4% YoY gain. This contrasts with the 5%+ YoY gains recently seen, and reflects the rehiring of low-wage workers in sectors like food and beverage serving. 

Aggregate hours and wages:
  • the index of aggregate hours worked for non-managerial workers rose by 0.2%, which is a  loss of 4.3% since just before the pandemic.
  •  the index of aggregate payrolls for non-managerial workers rose by 0.7%, which is a gain of 2.2% since just before the pandemic.

Other significant data:
  • Leisure and hospitality jobs, which were the most hard-hit during the pandemic, increased 292,000, but is still -2,538,000, or 15.0% below its pre-pandemic peak.
  • Within the leisure and hospitality sector, food and drink establishments gained 186,000, but is still -1,480,400, or 12.0% below its pre-pandemic peak.
  • Full time jobs increased 223,000 in the household report.
  • Part time jobs increased 178,000 in the household report.
  • The number of job holders who were part time for economic reasons rose by 28,000 to 5,271,000, which is an increase of 873,000 since before the pandemic began.

SUMMARY

This was a very positive report, but still one which shows how far we still have to go.

Negatives were almost non-existent, consisting of declines in nonresidential construction jobs and temporary jobs (but the latter may be temps transitioning to permanent employment).

The more consistent theme, though, was that while there were gains, they weren’t nearly of the order we need for a quick recovery to pre-pandemic levels. Overall jobs are still 5% below where they were in February 2020, and the hard hit leisure and hospitality sector is 15% below its pre-pandemic peak! The upward revisions in March and April were tepid, confirming my suspicion that March may have been as much as or more of an outlier than April. This month’s number was close to the combined March and April average.

Further, the YoY gains in hourly wages have been more than eaten up by inflation. As the stimulus payments wear off, I suspect we are going to see a faltering in sales, which would not be good.

The brightest spot was the new low in short-term unemployment, which was even lower than before the pandemic, and among the 10 lowest months in the past 10 years. 

In essence, this report showed that there are very few new layoffs, but not enough new hires to keep the new expansion growing robustly.

Thursday, June 3, 2021

New jobless claims continue strong decline, consistent with ongoing recovery, while continuing claims continue mixed


 - by New Deal democrat

New jobless claims continue to be the most important weekly economic datapoint, as increasing numbers of vaccinated people and outdoor activities have led to an abatement of the pandemic - deaths are at their lowest point in over a year, and new infections at their lowest points since the onset of the pandemic. 

Several weeks ago we hit my objective for claims to be under 500,000 before Memorial Day, and this week  we hit second objective, for claims to be below 400,000 by Labor Day. 

REMINDER: Because of the unprecedented number of layoffs during the April and May 2020 lockdowns, for the last year I have given heightened importance to the non-seasonally adjusted numbers. This will be the last week I include them.

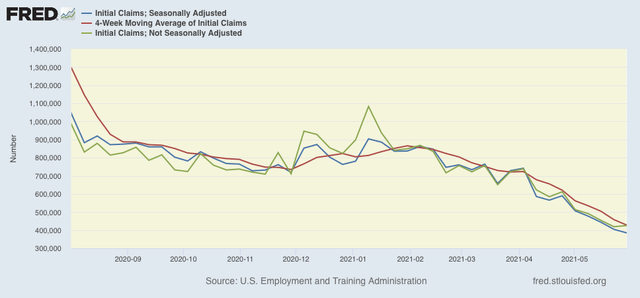
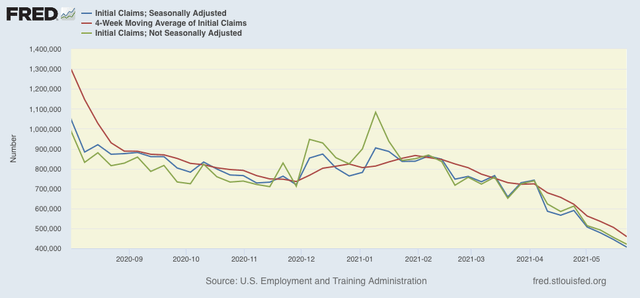
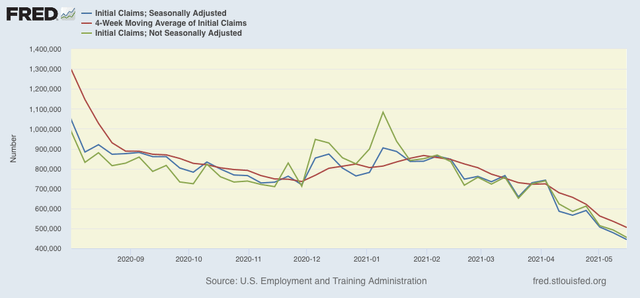
New jobless claims declined 20,000 to 385,000. On a unadjusted basis, however, new jobless claims rose 6,014 to 425,450. The 4 week average of claims declined by 30,500 to 428,000. Both seasonally adjusted numbers were new pandemic lows.


At the peak of the pandemic lockdowns, new claims were running 6 million to 7 million per week. Here is the trend since the beginning of last August:


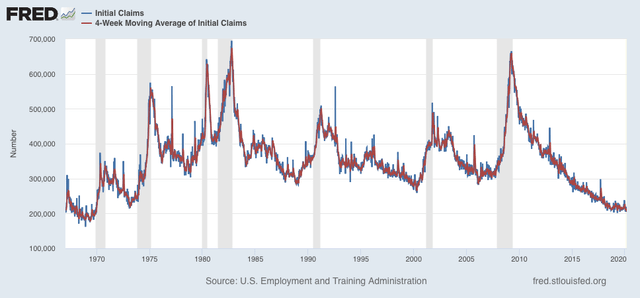
In the past 3 months, claims have trended down an average of roughly 100,000 per month. If this continues for just 3 more weeks, new claims will be at levels which in the past have been consistent with full or nearly full employment deep into expansions. At their current level, claims are consistent with early to mid-recovery levels in the past:


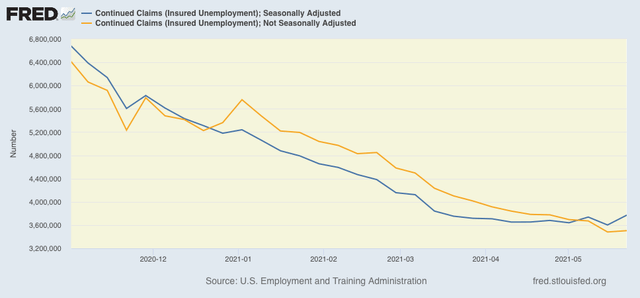
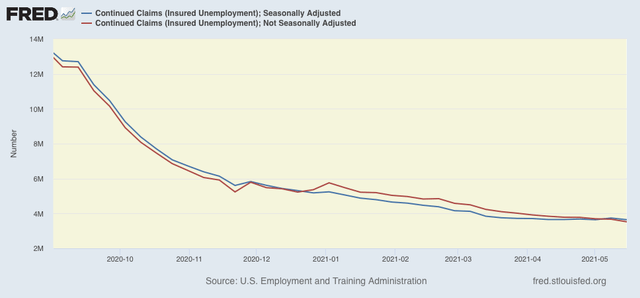
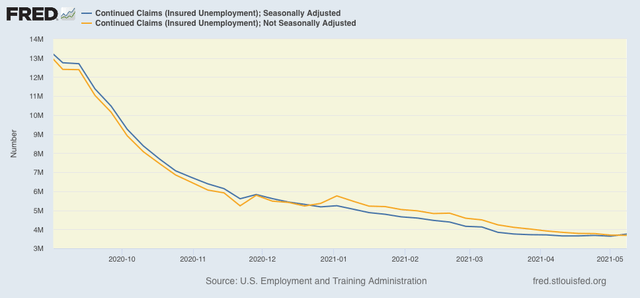
Continuing claims, which are reported with a one week lag, and lag the trend of initial claims typically by a few weeks to several months, rose 169,000 from their revised pandemic low of 3,602,000 last week to 3,771,000. On an unadjusted basis (gold), they also rose 22,860 from their revised pandemic low of 3,504,163 last week to 3,504,163:


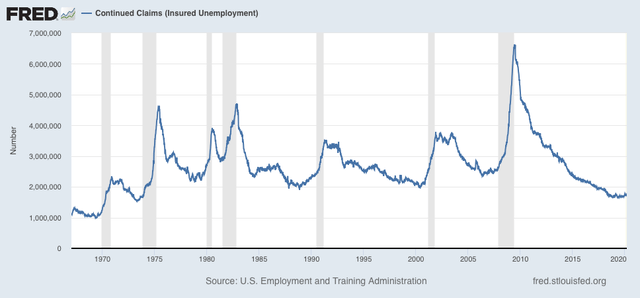
The long term perspective again shows that these are equivalent to the worst levels of most previous recessions, versus at 2,000,000 or below during strong expansions:


I am not sure if the recent strong declines in new jobless claims will continue from here, as we approach past levels of full or nearly full employment. The issue with continuing claims has become more complex, as unadjusted claims show a slowly declining trend, while after adjustments they have essentially been flat since the beginning of March. The picture has become much more clouded as half of the States have announced early terminations of supplemental pandemic benefits for ideological reasons. 

Finally, as I wrote two weeks ago, March’s employment gains may have been more of an outlier than April’s. If we simply averaged the 2 months together that would be an average jobs gain of 518,000, then the continued big decline in initial claims would give us a May jobs gain of over 500,000 when that report is issued tomorrow. There may also be big revisions to March and April’s numbers as well. We’ll see.

Wednesday, June 2, 2021

Coronavirus dashboard for June 2: most of US approaches herd immunity threshold; COVID still spreading among the remaining idiots


 - by New Deal democrat

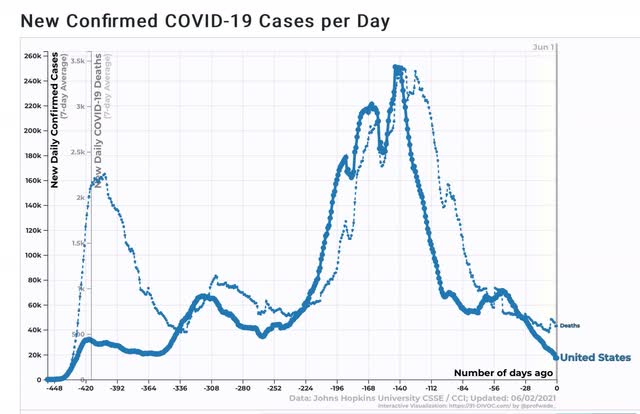
In the past week new COVID-19 cases declined almost 30%, by about 7,000 to 17,289/day; however, deaths actually increased by about 10% to an average of 589/day, mainly due to a data dump by California 5 and 6 days ago - thus I expect a new low in deaths within the next several days:


Total deaths are 595,213. Over 60% of all adults have received at least one dose, and over half are fully vaccinated. Slightly over half of the US population, including all children, has received at least one dose.

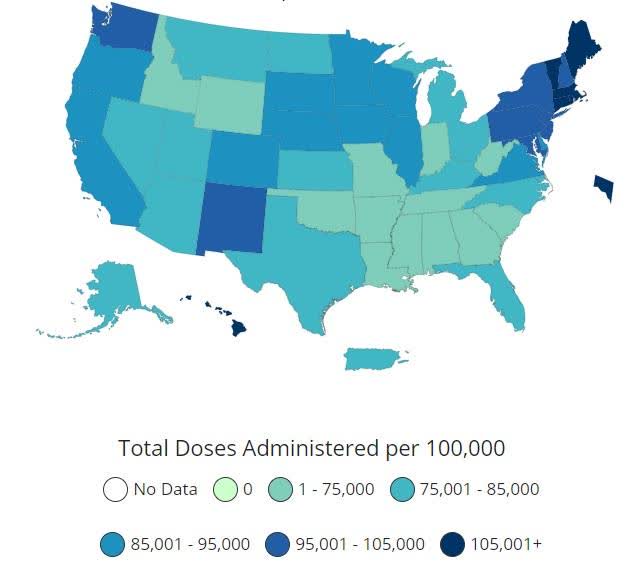
But the overall situation masks a large divergence between States where there have been the most vaccinations vs. States with the least. Here is the map of vaccination administration by State as of one week ago:


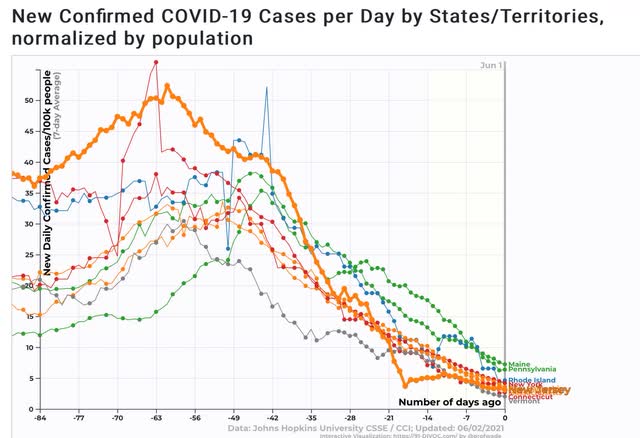
In the Northeast, only NY, at 67.9%, is slightly below 70% of all adults who have received at least one dose of vaccine. California also is over 70%.

And here are the results: cases in the Northeastern States have rapidly declined to their best levels since the beginning of the pandemic. Only Maine and Pennsylvania, while still showing sharp declines, are lagging:


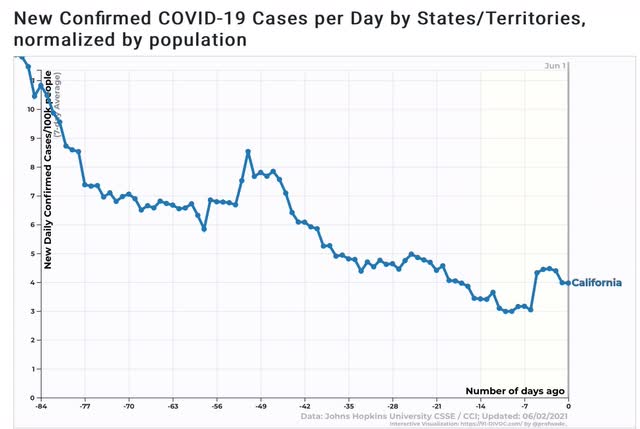
Meanwhile California has also seen over a 95% decline in cases since winter, when they averaged over 110 new cases per 100,000 population daily:


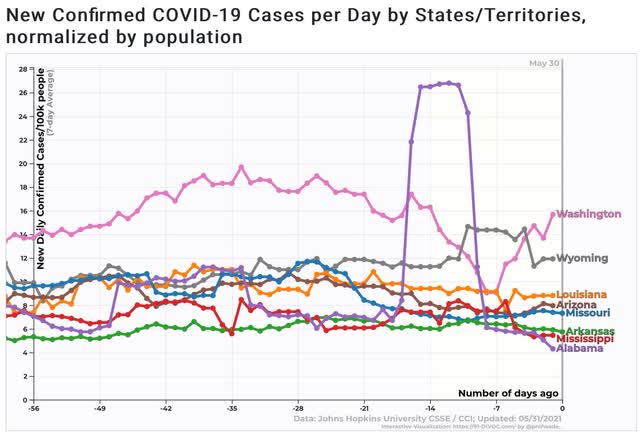
At the other end, there are 8 States which have seen *no* meaningful declines in cases over the past 8 weeks:


Four of them - WA, WY, LA, and AZ - are among the 10 worst States for new cases, which MO close behind. AR, MS, and AL are roughly in the middle of the pack. Note that with the exception of Washington State*, all of them are among those with the lowest rate of vaccinated population.

*A perusal of news sources in Washington State suggests that the recent increase in new cases is due to the admission of unvaccinated new residents to long term care facilities. When the disease is re-introduced into the facility, with close quarters and recirculated air among the most immune-compromised population, the disease spreads even among the vaccinated (although there is no indication of increased deaths among that group). 

Basically, most of the US is at least very close to achieving herd immunity, while the disease continues to spread among those with recalcitrant populations, and if the new cases are all or virtually all among those who have voluntarily decided not to get vaccinated, then the disease is spreading among them at rates similar to last spring and summer, with little decline at all.

Tuesday, June 1, 2021

May manufacturing continues white hot; April construction spending shows signs of being constrained by materials and costs


 - by New Deal democrat

It’s the first of the month, which means we get our first look at May data in the form of the ISM manufacturing index, as well as April construction spending. The questions we are looking for information to answer from these two leading sectors of the economy, manufacturing and residential construction, are: (1) is the Boom still ongoing, and is it likely to continue in the coming few months; and (2) is there evidence that inflation is creating a bottleneck on growth?

The answers for the two sectors appear to be different.

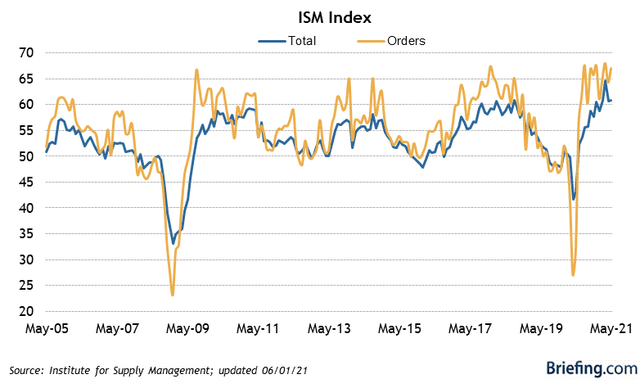
First, the May ISM manufacturing index increased slightly from 60.7 to 61.2. The new orders component of the index, which is the most leading, increased even more, up 2.7 from 64.3 to 67.0, very close to its December and March highs:

The boom in manufacturing is continuing, with no evidence of a slowdown in the near future.

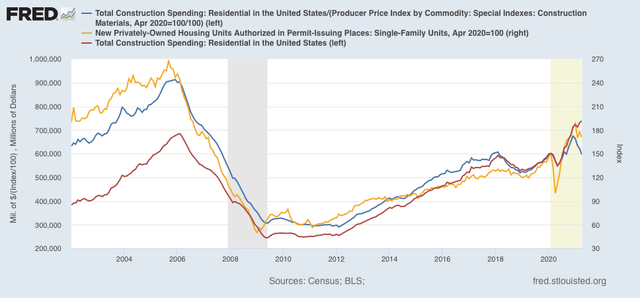
Residential construction spending is not quite as leading as new home sales or permits, but it has the virtue of having very little noise and almost all signal. But there is a quandary, because for the first time in 20 years, the direction of this indicator differs sharply depending on whether or not one factors in the prices of construction materials.

The below graph shows residential construction spending unadjusted for inflation (red), which made another all-time high in April; compared with the same but adjusted for the cost of building materials (blue), which has turned down by 11.5% since December (red); and single family permits (gold), which have turned down by 9.5% since January:


This looks like a bottleneck putting the brakes on growth. Spending is growing, but only because the price of materials has gone up sharply. That the downturn in construction permits and spending adjusted for the cost of materials occurred nearly simultaneously and by similar percentages looks like it is the cost of materials which is decisive - I.e., costs - due to shortages in materials - are driving the numbers.

Monday, May 31, 2021

Memorial Day 2021


 - by New Deal democrat

Memorial Day is that most somber of national observances, in which we remember all those, of whatever race, creed, color, or nationality, who gave their lives so that government of the People, by the People, and for the People shall not perish from the Earth.

Here are some of their resting places:


Gettysburg National Cemetery


Antietam National Cemetery


Arlington National Cemetery

Normandy, France:


May they Rest In Peace, and may our generation be worthy of their sacrifice by maintaining the Republic that they bequeathed to us.

Weekly Indicators for May 24 - 28 at Seeking Alpha


 - by New Deal democrat

There was a delay over at Seeking Alpha in posting my latest Weekly Indicators note, but it is now up.

The underlying strongly bullish fundamentals of the economy have not changed.

This week, in conjunction with Robert Dieli of the No Spin Forecast, I initiated coverage of a metric that he and the late Jeff Miller initiated called the “C-Scorre,” essentially a weekly estimate of the trade off between inflation and unemployment (the Philips curve) on the one hand, and the yield curve on the other hand. Jeff Miller passed away early in May, so I am now continuing the series.

As usual, clicking over and reading will bring you up to the virtual economic moment, and reward me with some lunch money.

Friday, May 28, 2021

Real personal income has completely made up its recession losses, now exceeds pre-recession peak


 - by New Deal democrat

The last of the 4 monthly coincident markers for whether the economy is in recession vs. expansion was reported this morning for April. Let’s take a look.


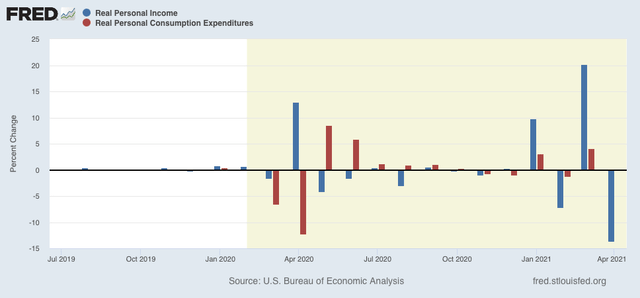
In nominal terms, personal income declined -13.1%, taking back most, not by no means all, of March’s big 20.7% gain. After taking inflation into account, in real terms it declined -13.7%. Meanwhile nominal personal spending increased 0.5%, but in real terms declined -0.1%, barely touching March’s 4.0% gain:


An issue came up at Seeking Alpha about why I believe that demand-driven inflation will be transitory. The above graph shows why. After 2020’s big stimulus package, real personal spending increased sharply and then the effect completely dissipated over a few months. It appears that the same is already happening this year. Which would only leave supply-side temporary bottlenecks in production as sources of continued inflation.

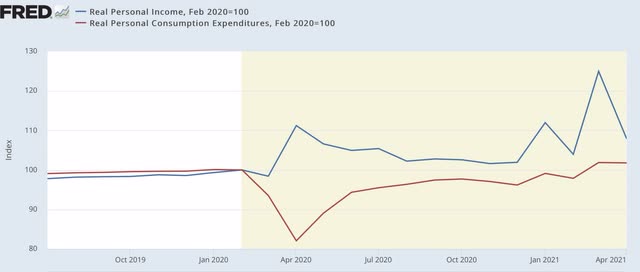
Below I’ve take then same data as above and normed both to 100 as of February 2020:


Both real income and spending are above their pre-recession levels. Simply put, in this crisis decisive action by the government to put cash in consumers’ hands has worked.

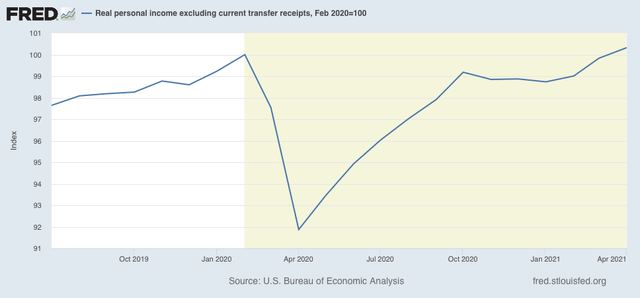
But the “official” recession vs. expansion metric is real personal income less transfer receipts (things like unemployment insurance), shown below:


This too is now above its pre-recession levels. Although I won’t post a graph, this joins real sales making up all of its lost recession ground. But the two most important metrics - industrial production and employment - still have a ways to go.

Thursday, May 27, 2021

New jobless claims continue to decline at rate of 100,000 per month, while continued claims stall at elevated level


 - by New Deal democrat

New jobless claims continue to be the most important weekly economic datapoint, as increasing numbers of vaccinated people and outdoor activities have led to an abatement of the pandemic - both new infections and deaths are near their lowest points in a year. 

We have hit my objective for new claims to be under 500,000 by Memorial Day. Even better, we are already approaching my second objective, which is for them to be below 400,000 by Labor Day. 

REMINDER: Because of the unprecedented number of layoffs during the early lockdowns, for the last year I have given heightened importance to the non-seasonally adjusted numbers. After May is over, their importance recedes and I expect to discontinue tracking them.

New jobless claims declined 38,000 to 406,000. On a unadjusted basis, new jobless claims declined 34,131 to 420,472. The 4 week average of claims also declined by 46,000 to 458,750. All of these were new pandemic lows.


At the peak of the pandemic lockdowns, new claims were running 6 million to 7 million per week. Here is the trend since the beginning of last August:


In the past 3 months, claims have trended down an average of roughly 100,000 per month. If this continues for just 1 more month, new claims will be at levels which in the past have been consistent with full or nearly full employment deep into expansions. At their current level, claims are consistent with being very early in a recovery in the past:


Continuing claims, which are reported with a one week lag, and lag the trend of initial claims typically by a few weeks to several months, declined 96,000 to 3,642,000, (blue), 2,000 above their pandemic low from two weeks ago. On an unadjusted basis (red), they declined 149,996 to 3,521,314:


The long term perspective again shows that these are equivalent to the worst levels of most previous recessions, versus at 2,000,000 or below during strong expansions:


As I wrote last week, March’s employment gains may have been more of an outlier than April’s. If we simply averaged the 2 months together that would be an average jobs gain of 518,000, then the continued big decline in initial claims would give us a May jobs gain of over 500,000 when that report is issued next Friday.

I continue to think initial jobless claims will continue their recent strong decline, while the failure of continuing claims to make meaningful new lows in the past 2 months is a genuine concern that the pace of new hiring has not been picking up.

Wednesday, May 26, 2021

Comprehensive April housing report: beware the inventory and price boomerang!


 - by New Deal democrat

Now that we have all of the April housing data, my comprehensive look at this long leading sector is up at Seeking Alpha.

It’s pretty clear that sales and new construction have peaked in the short term. So, what happens when all of those people who would have put their houses on the market in 2020, but didn’t because of the coronavirus, decide to put them on the market later in 2021 or in spring 2022?

As usual, clicking over and reading puts a penny or two in my pocket to reward me for my efforts.

Tuesday, May 25, 2021

New home sales decline in April, revised sharply lower for March; prices continue to skyrocket, while inventory increases


 - by New Deal democrat

This morning both new home sales and two price indexes for houses were released for April, completing our view of that important long leading sector.


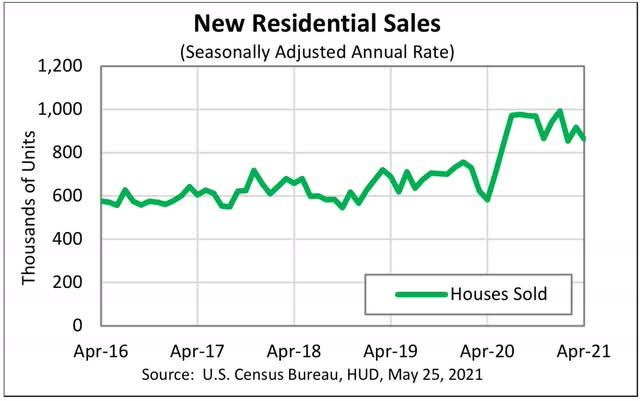
As anticipated, not only did new home sales decline for the month, but March was also hugely revised to the downside ( over 10%!):


With these revisions, the peak for new home sales becomes the December-January period, exactly as is the case for housing permits, starts, and existing home sales.

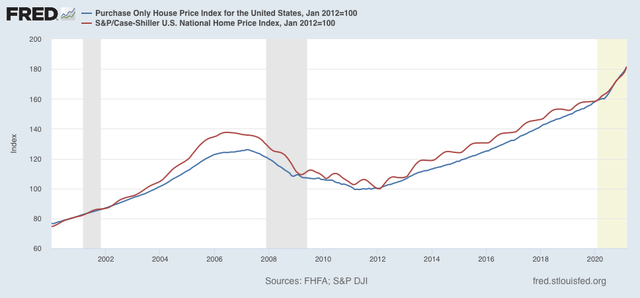
But if sales are down, prices are continuing to skyrocket:


As measured by the FHFA, prices increased 1.4% seasonally adjusted just in the past month! YoY they are up 13.9%.  For the Case Shiller national index, the monthly change was +2.0%, and the YoY change was +13.2%.

Housing inventory is increasing again, up about 3% m/m and now only down about 2% YoY, vs. a trough of being down over 12% YoY.

I’ll have more later at Seeking Alpha.

Monday, May 24, 2021

Coronavirus dashboard for May 24: 3 weeks to 0 new cases?


 - by New Deal democrat

No, that won’t happen. But, even so, that is the current trajectory. Let’s start with the overview:


Total *confirmed* cases: 33,117,737
Total deaths: 589,893

Note that there are many more cases that we don’t know about because the people were never tested. Since about half of cases appear to be only mildly or non-symptomatic, an additional 10% of the population having been infected seems like a reasonable guess. And excess deaths for 2020 ran closer to 900,000, so we may also be missing many deaths.

Before I go further, let me address an article that appeared over the weekend in the Wall Street Journal suggesting that an “intelligence source” had confirmed that it was likely that the virus escaped from a lab in Wuhan. That report seems to have convinced both Nate Silver and Matt Yglesias.

A pretty good takedown of that article appears here:

Essentially, somebody associated with an intelligence agency in the Trump Administration authored a report - but not an actual official intelligence report - in the closing weeks of that Presidency making the claim, possibly for political reasons, based on a document that is never disclosed or identified, and the document itself disclaimed that “additional corroboration” was needed. The same “information” likely was the basis of similar reports last April, one by the BBC which subsequently had to walk back its claims.

Oh.

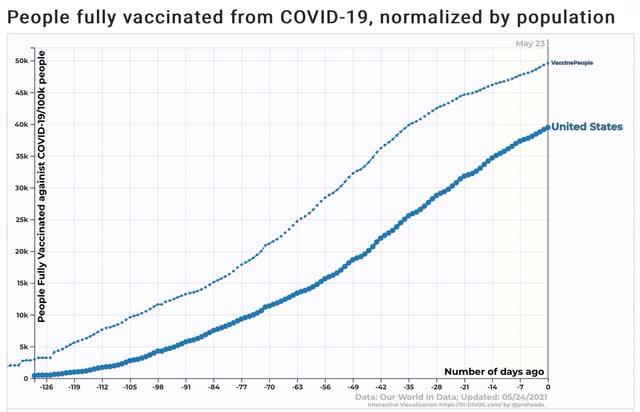
Turning to the updated data, we are within a few days of 50% of the entire US population having received one dose. with 50% of the adult population and nearly 40% of the total population being fully vaccinated:


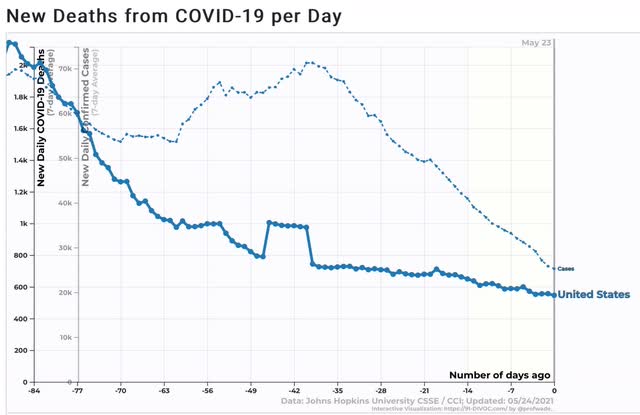
Deaths declined by about 7% in the past week to an average of 546/day, while cases declined almost 25%, by about 8,000 to 25,270/day:


If this decline of nearly 1,200/day, which has been going on for the past 7 weeks, were to continue for just 3 more weeks, we would arrive at 0 cases per day! The slow pace of the decline in deaths is of some concern as, if anything, I would expect that to accelerate and decline faster than new cases. So it will have to be watched.

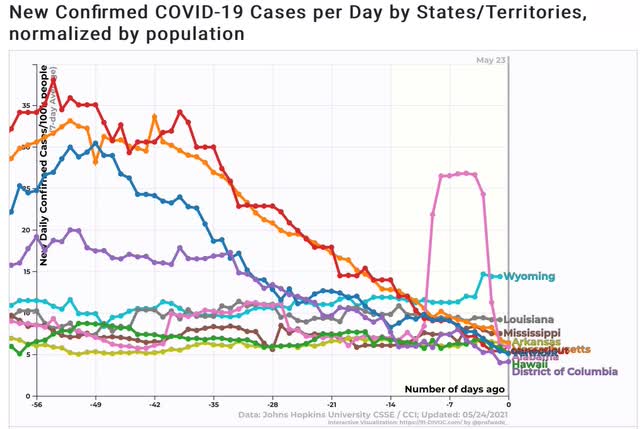
Finally, below is a comparison of new cases over the past 8 weeks for the 5 States that have administered the fewest vaccinations per capita (MS, AL, LA, AR, and WY) vs. the 5 jurisdictions that have administered the most (VT, MA, HI, CT, and DC):


The only overlap is that of Alabama. The other 4 States with few vaccination are in the top 1/2 for new cases, while the 5 jurisdictions with the most vaccinations are in the bottom 1/2. At some point soon, the federal government may have to step in directly to administer vaccinations to willing people (probably among the minority Black population) in those States in the Deep South that have been recalcitrant.

Saturday, May 22, 2021

Weekly Indicators for May 17 - 21 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

The theme of a supply-constrained economic Boom continues, with the addition this past week of the national average of gas prices going over $3 a gallon for the first time since 2014, probably in part to the Colonial Pipeline snafu.

As usual, clicking over and reading will bring you right up to date on the state of the economy, and bring me a little pocket change for gas money.

Friday, May 21, 2021

Existing vs. new home sales: sales have peaked, expect prices to soon


 - by New Deal democrat

I normally don’t pay much attention to existing home sales. Even though they constitute about 90% of the housing market, they have much less impact on the economy overall than new home sales (because all of the economic activity involved in building the house, and then landscaping the outside and furnishing the inside).


But they can be a comparison with new home sales, particularly as they are a competing product. And the procession of data is the same: interest rates lead sales, which in turn lead prices, which in turn lead inventory.

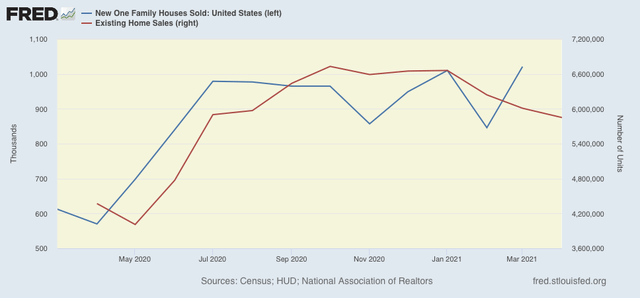
Existing home sales for April confirmed what we have already seen with new home sales: the market peaked at the turn of the year. Sales declined 2.7%, seasonally adjusted, compared with March, to 5.85 million units annualized. That is the lowest number since last July’s 5.90 million. It is about -12% below the January peak of 6.66 million. Below I show both new (blue) and existing (red) home sales for the past year:


Earlier this week we saw that housing permits and starts are both also off of their highest point of December and January.

Median prices, however, continued to climb to a new all time high of $341,600, a YoY gain of 19.1%, the highest YoY gain on record.  Inventory continued to decline, to less than 2 months’.

I fully expect prices to reverse in the coming months, and I also expect inventory to increase.

Thursday, May 20, 2021

Big decline in new jobless claims continues, while decline in continuing claims has stalled


 - by New Deal democrat

New jobless claims continue to be the most important weekly economic datapoint, as increasing numbers of vaccinated people and outdoor activities have led to an abatement of the pandemic - both new infections and deaths are near their lowest points in a year. 

We have hit my objective for new claims to be under 500,000 by Memorial Day. My second objective is for them to be below 400,000 by Labor Day. 

NOTE: Given the unprecedented scope of layoffs during the earliest phase of the pandemic, I have given heightened importance to the non-seasonally adjusted numbers. Once May is over, their importance recedes and I expect to discontinue tracking them.

New jobless claims declined 34,000 to 444,000. On a unadjusted basis, new jobless claims declined 37,395 to 454,634. The 4 week average of claims also declined by 30,500 to 504,750. All of these were new pandemic lows.


At the peak of the pandemic lockdowns, new claims were running 6 million to 7 million per week. Here is the trend since the beginning of last August:


The current level of claims are at levels consistent with either a mild recessions or early in the recovery from a recession in the prior 50 years prior:


Continuing claims, which are reported with a one week lag, and lag the trend of initial claims typically by a few weeks to several months, declined 111,000 to 3,751,000, (blue). The bad news is that they are 111,000 above their pandemic low. The good news is that the data has been revised - last week was the new pandemic low! On an unadjusted basis (gold) , they declined 10,323 to 3,68408:


The long term perspective again shows that these are equivalent to the worst levels of most previous recessions:


Finally, the average change in initial claims during the last 4 weeks - the weeks that will coincide with the May jobs report - declined -151,000 from the previous 4 weeks! That is simply unprecedented outside of the pandemic. Since, as I wrote yesterday, March’s employment gains may have been more of an outlier than April’s, and if we simply averaged the 2 months together that would be an average jobs gain of 518,000, then the continued big decline in initial claims would give us a May jobs gain of over 500,000 when that report is issued in 2 weeks.

I continue to think initial jobless claims will continue their recent strong decline, while the failure of continuing claims to make meaningful new lows in the past 6 weeks or so is genuine concern (and I’m working on a historical post on that subject).

Wednesday, May 19, 2021

Further considerations on the disappointing April jobs report. Consider the averages!


 - by New Deal democrat

I’ve been threatening for a couple of weeks to run some extended comments on the big miss in the April jobs report. As there’s no economic news of note today, here goes . . . .


1. It’s possible March was the outlier rather than April.

The original report for March was that 916,000 jobs were added. In this month’s report it was revised down to 770,000. Below is a graph of “civilian employment” from the household report (blue), “employment” from the establishment report (which is the commonly reported number (red), and the monthly change in initial jobless claims (green, inverted so that a decline shows as a positive, /100 for scale):
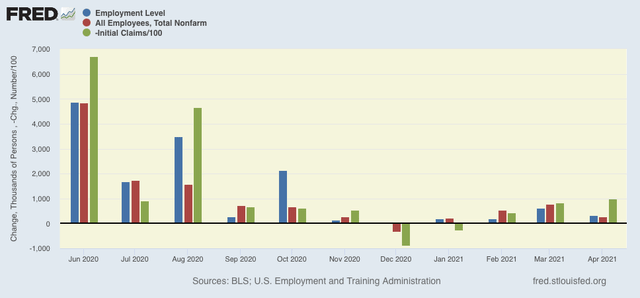

Note that in general - but not always! - the change in jobless claims correlates well with the change in both of the jobs numbers. Note also that the April change in jobless claims was the largest since early on in the pandemic. 

That being said, there have been *only* about a dozen previous times in the last 50+ years when initial claims declined as much as they did in April, but before the pandemic, the median change was about +350,000 for such changes. That’s a very small sample, so a large variance can easily be expected.

In any event, the 2 month change for March and April in the jobs report was +1,036,000 as currently revised, or 518,000/month. The comparable “civilian employment” 2 month number from the household survey was 937,000, or 468,500/month. The household report # now looks very close to the establishment survey’s number. In other words, the original establishment report of 916,000 for March may have been the outlier, and maybe we should have expected #s closer to the 350,000 median that was correlated with similar improvement in the jobless claims numbers.

2. But the likelihood of big job gains isn’t over - and may be missed by the establishment survey

There are still a ton of closed businesses and laid off employees out there. Fortunately, I’ve been saved the intensive work of sorting out those losses by jobs categories, because it’s already been done by the American Institute of Economic Research, which produced the below two graphs, first of the raw numbers of current pandemic job losses in each sector:
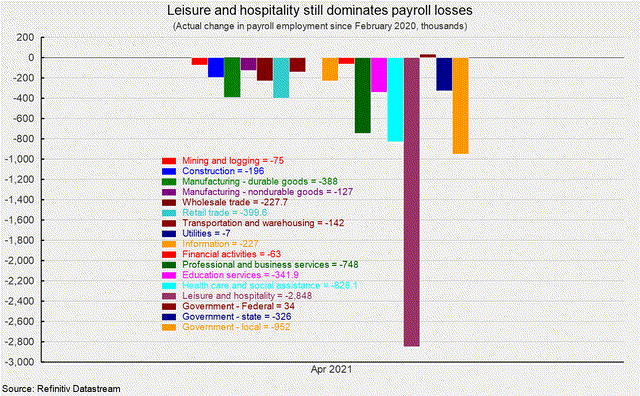

And the same expressed as a percentage of pre-pandemic jobs:
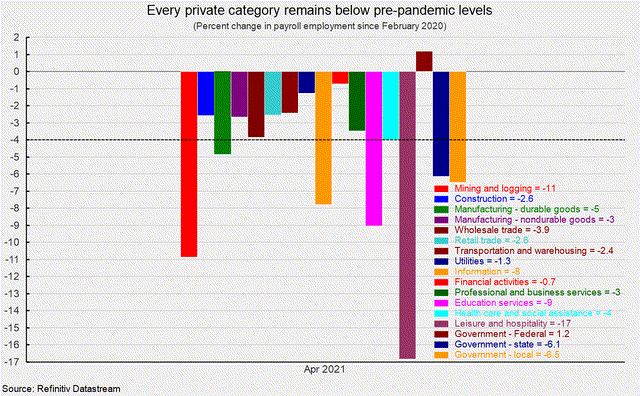

In leisure and hospitality in particular, there remain almost 3,000,000 lost jobs, or nearly 20% of the pre-pandemic total in that sector. There are also large losses in local government, professional and business services, and social assistance.

Once the US reaches herd immunity, which I believe will be sometime this summer, I would expect most of those positions to open back up. Which means more big employment gains.

Also, anecdotally, I was in a neighboring metro with some friends last weekend, and we came across the site of one of our favorite restaurants that had “permanently” closed last spring as the pandemic lockdowns hit. And - surprise! - it had just opened back up in the same location. I wonder how many other landlords and former tenants are making similar arrangements? If this is happening a lot, the only way it would show up in the establishment jobs report is via the “birth/death adjustment” which estimates how many new businesses have just opened, and haven’t been around long enough to be picked up by the survey. If this adjustment is off in these nearly unprecedented times, then the only place we might see these jobs being picked up is in the household report, where people report whether or not they have jobs.

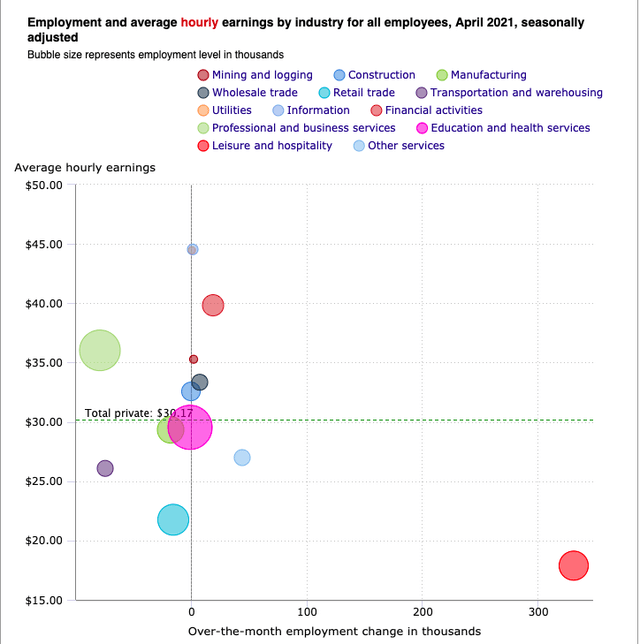
3. The best evidence is that enhanced unemployment benefits have not been a big drag on hiring.

Two separate sources took a look at where the big job gains were (and weren’t) in the April report, separated out by where those jobs typically fit on the wage scale.

If enhanced unemployment benefits were the big driver of the disappointing report, then we would expect the impact to show up most in low-paying jobs.

It didn’t. Here is a dot-plot:

And here is an easier-to-interpret line graph, with labels:
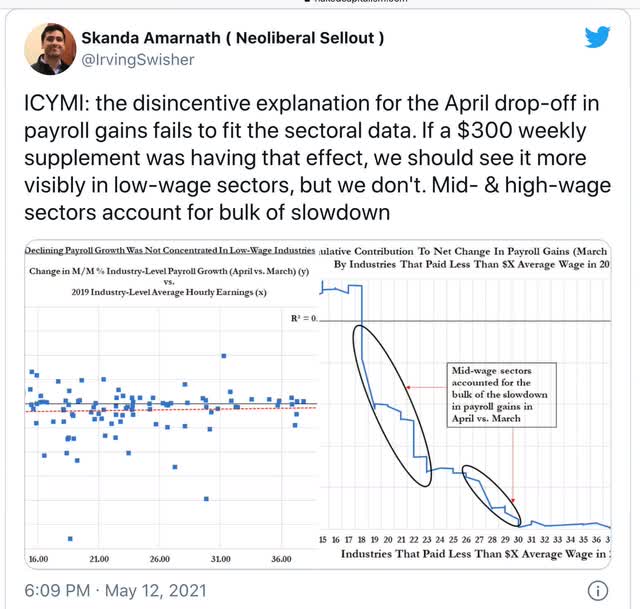

The conclusion in both is that mid-level wage jobs were the source of the big slowdown. That’s not due to $300 added jobless benefits!

So, my considered best guess is, discount the blockbuster March report more than the relatively tepid April report, average the gains in the two months out, don’t fret about enhanced unemployment benefits, and don’t assume that the time of big job gains is over.

Tuesday, May 18, 2021

April housing permits and starts: a pullback from peak, but no recessionary signal UPDATED


 - by New Deal democrat

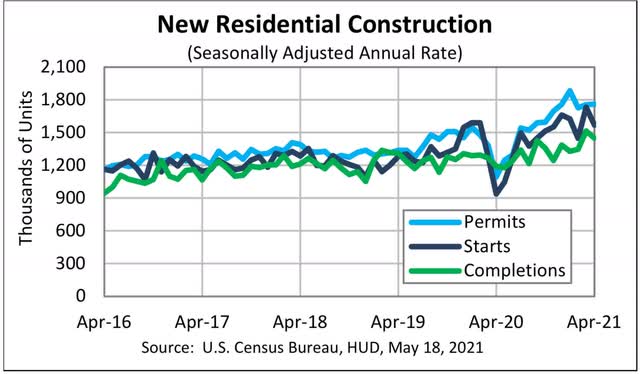
The monthly statistics on housing permits and starts, reported this morning, were mixed, as permits increased slightly and starts declined:


The less volatile single family permits also declined slightly.

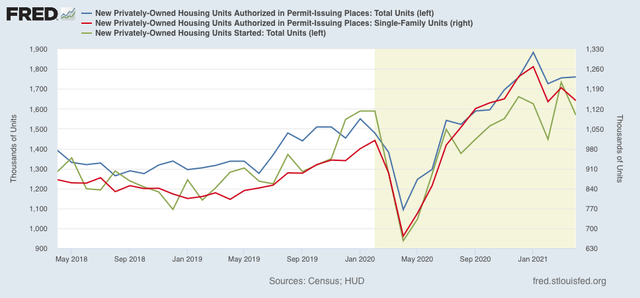
On the one hand, a high level of construction activity is continuing. But the three month moving average of both single family and total permits, as well as starts, all declined from their highs in the December-January period. To be recessionary, I would need to see at least a 10% decline in total permits; the actual decline from peak is about 6%, so well within the range of a little pullback during an expansion.

I’ll have more to say once the data is posted at FRED, probably later today.

UPDATE: Here is the comparison of single family permits (red, right scale) - the least volatile of the measures - with total permits (blue) and starts (green) - which are about twice as volatile as permits and typically lag by a month or so:


The December 2020 - January 2021 peak is evident.

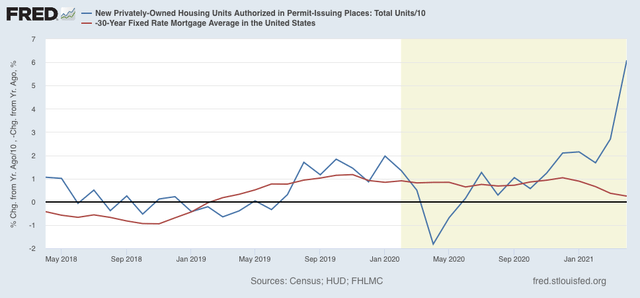
And here is the YoY change in mortgage rates (red), inverted so that up = economic positive, and down = economic negative, compared with total permits (blue)/10 for scale:


As I have said many times before, mortgage rates lead permits and starts. The artifact of comparisons with the pandemic lockdown months will end in June, at which time I expect permits to be only about 5% ahead of summer 2020 (= .5% on the graph).

Monday, May 17, 2021

Coronavirus dashboard: entering the home stretch?


 - by New Deal democrat

G*d willing, I will only feel the need to update this information for another month or two. The US is simply making great progress on all fronts, and there are no new outbreaks in any of the States.


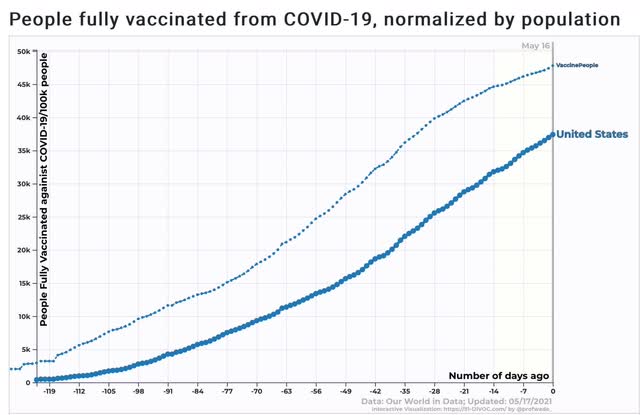
Close to 40% of the entire US population is totally vaccinated, and almost 50% has received at least one dose:


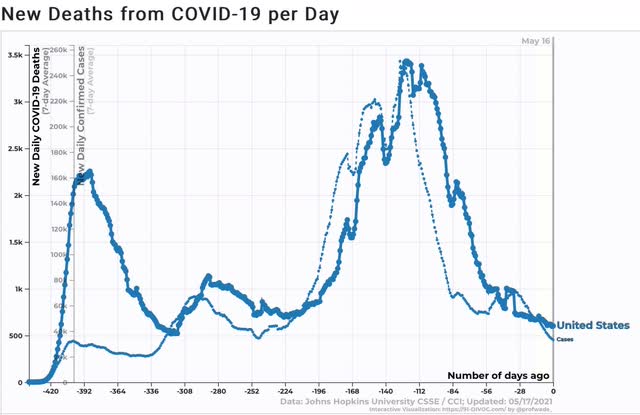
As a result, both cases and deaths are lower than their troughs last summer, and are at 10 to 11 month lows. Deaths are down about 85% from peak, and cases down 88%:


At their current trajectory, there will be fewer cases than at any time since March 2020 in about 2 weeks. Deaths, which are declining at a much slower trajectory, may be there in 4 to 6 weeks.

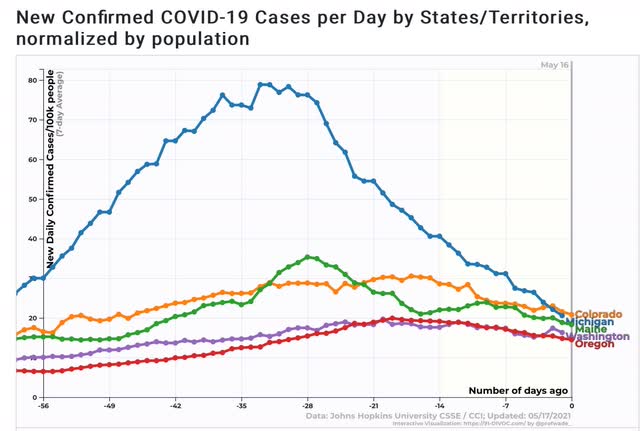
And there are no States with rising caseloads. The 4 I showed last week - Colorado, Maine, Oregon, and Washington State - all are now in decline. And Michigan, which had a severe outbreak about 3 months ago, has seen a decline of 80% since then:


With some luck, I will be able to put up my last Coronavirus post, celebrating independence from the virus, on the 4th of July!

Saturday, May 15, 2021

Weekly Indicators for May 10 - 14 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.

The big news in this past week, even though it has been expected for several months, was on the inflation front. That doesn’t affect the nowcast, and hasn’t affected the short term forecast yet. The long term forecast continues to be buffetted by increased interest rates.

In my commentary this week, I make reference to supply constraints. I bring this up here because I read a tweet today by someone whose political analysis I respect, showing a graph of the spike in lumber prices, and stating that lumber was “in a bubble.”

No it’s not. The defining feature of a bubble is speculation on the continuing increase in prices. Fifteen+ years ago it was “everyone knows real estate only goes up!” In 1999 it was “everyone knows these internet companies are going to completely take over commerce!” In 1929 it was “stock prices have reached a permanently high level!” In the 1700s it was “the price of land in the Mississippi Valley is going to explode!” - which was sort of correct, but it took 200 years to happen. As they say, “being early” is a synonym for “being wrong.”

What is happening with lumber, and computer chips, is similar to what happened during the Oil Embargo of the 1970s. This is a supply constraint. Product cannot (in the 1970s, would not) be supplied fast enough to meet the demand. So the way the product gets rationed is to raise prices until enough buyers stop buying.Whether it is a significant problem or not depends upon how quickly the pace of supply can be increased, a question that I do not pretend to know the answer to.

In any event, as usual, clicking over and reading will bring you up to the virtual moment, and bring me my lunch money.

Friday, May 14, 2021

April Industrial Production slightly disappoints - but only due to supply chain bottlenecks


 - by New Deal democrat

Industrial production is the King of Coincident Indicators, and is the one whose peaks and troughs most frequently mark the beginning and end of recessions. It had been bouncing back strongly, but in the last several months, has hit something of a snag.

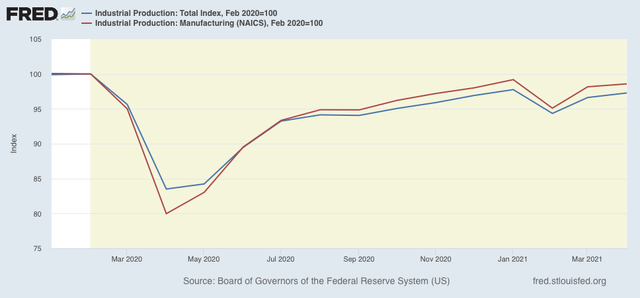
In April, total production increased 0.7%, while manufacturing production increased 0.4%:

Both of these, however, remain slightly below January’s levels, and -2.7% and -1.4% respectively below their February 2020 peak just before the pandemic hit.

The good news in April was that the declines from February’s Big Texas Freeze have been largely resolved. The bad news is that shortages in some supplies continue to create bottlenecks holding back production.

The Fed’s news release notes the important following issues:


 [T]he index for manufacturing rose 0.4 percent despite a drop in motor vehicle assemblies that principally resulted from shortages of semiconductors. An important contributor to the gain in factory output was the return to operation of plants that were damaged by February's severe weather in the south central region of the country and had remained offline in March.


Most market groups posted gains in April, with the principal exceptions being those related to motor vehicles and parts. Automotive products, transit equipment, and consumer parts all recorded losses, as shortages of semiconductors held back motor vehicle assemblies. Among the other market groups, chemical materials and consumer energy products posted strong gains of 6.7 percent and 3.8 percent, respectively.  

The index for motor vehicles and parts fell 4.3 percent; excluding the motor vehicle sector, factory output advanced 0.7 percent, primarily reflecting a further recovery in chemicals as additional factories that had sustained weather-related damage during February reopened. Elsewhere, industry results were mixed, with supply chain difficulties possibly hindering production.... 

The output of utilities moved up 2.6 percent in April after dropping substantially in March, when unseasonably warm weather reduced demand for heating....


The good news for the near future is that these supply chain difficulties are going to be resolved, and as they are resolved, production can be expected to pick up swiftly, given the surge in demand. The important issue will be that the issues get resolved quickly enough so that there is not an episode of “stagnation” caused by resource constraints (a la the gas-fueled stagflation of the 1970s).