Wednesday, March 30, 2011

Tuesday, March 29, 2011

Gold Still Hitting Resistance

From Bloomberg:

“The more positive signs from the U.S. economy mean that the expectations of rate rises are starting to come back to people’s attention,” Darren Heathcote, head of trading at Investec Bank (Australia) Ltd. in Sydney, said today by phone. Higher rates “will inevitably take some of the shine off gold, decreasing its attractiveness to investors,” he said.

Four Important Positive Changes in the U.S. Economy

There are three underlying trends occurring in the U.S. Economy that are flying below the radar.

1.) The increased savings rate: for the last 10-15 years, the cry of "we don't save enough" has been been heard throughout the economic world. It was argued (and I believe correctly so) that the lack of savings was a sign the U.S. consumer was borrowing too much (see number 2 below) and spending too much, essentially living beyond his means (which he was). However, that has clearly changed, as the U.S savings rate has now increased during the first part of the latest recovery:


This is an important fundamental change. It will help us to finance the trade deficit and keep interest rates lower by increasing the supply of loanable funds.

2.) The decrease in household leverage. This is tied in with point number one. US households are still heavily indebted. Before the recession started, the household debt/disposable personal income ratio was over 130%. That number has now dropped to 114%. As a result, the financial obligations ration has been dropping sharply:


3.) The rebirth of US manufacturing: According to the national manufacturing readings, US manufacturing is literally on fire. Consider this chart of the ISM manufacturing index:


The ISM number is printing some of the strongest readings in over 20 years. Kash over at the Streetlight Blog has written some great articles on this (see links at the bottom of the page on this link).

4.) The rise of US exports: the US is no longer the primary driving force of the the world economy; developing economies (especially the BRIC) players are exerting a strong influence over international economics. The US is selling exported goods into this strength, which is clealry helped by a cheaper dollar. This has led to the rise of U.S. exports as an important part of the economic recovery:

With housing and construction in the dumps and consumer spending pinched by thrift and tight credit, exports have powered nearly half of U.S. economic expansion since the recession ended in mid-2009

(The article goes on to note the U.S economy is now more vulnerable to international economic swings because of this development.)
There are still plenty of problems for us to deal with: a lackluster housing market and a high unemployment rate being at the top of the list. However, not all is bad; there have been some important fundamental changes for the better underneath the headlines.

And an oldie but a goodie -- I dug up this you tube video of me about two years ago talking about savings (I even mention Mish positively -- this was before he went off the reservation and into the great beyond):

New Congresspeople Now Members of the Washington Lobotomy Factory

From the Washingtonpost:

A breakdown late last week in closed-door negotiations between congressional leaders and the White House on funding the federal government makes it increasingly possible that Congress will not agree on a long-term funding resolution or another temporary measure by an April 8 deadline, aides from both parties said.

That means that the threat of a government shutdown — which had receded in recent weeks because of congressional approval of several stopgap funding measures — appears to be back on the table.

Problems with the negotiations became public late Friday, as revealed in comments from Sen. Charles E. Schumer (D-N.Y.) and the top three House Republican leaders. The apparent breakdown followed a Tuesday meeting among staff members for House Speaker John A. Boehner (R-Ohio) and Senate Majority Leader Harry M. Reid (D-Nev.) and representatives of the White House budget office on a possible deal for funding the government through the end of the fiscal year in September.

Democratic aides said talks had been underway for nearly two weeks between Boehner’s staff and the White House budget office, with steady progress leading to an agreement that the two sides would meet halfway between the $61 billion in cuts approved by the House and Democrats’ preference for maintaining current spending levels.

Just when you thought the idiots in Washington couldn't get any dumber, they rise to the occasion, as if to say, "we can actually do something that much dumber than what we have previously accomplished. No -- really. We can. Just watch us."

This is just idiotic. Government spending accounts for about 20% of US GDP. In addition, it is a facilitator of many important transactions. Shutting it down would be a huge shock to the economy --- at a time when we can ill afford it (as if there is a time when we can afford this lunacy). Here's something that people in Washington seem to forget on a regular basis: C+I+X+G = GDP. It's called the GDP equation. The "G" stands for government. Since the equation uses addition, taking out one of the primary variables will probably lower the total (unless one of the other variables increases sufficiently to make-up for the loss).

Let's look at some of the primary areas effected by such blatant stupidity:

The best guide for what consumers of government services can expect came in the last shutdown—the longest in U.S. history. After President Bill Clinton and a Republican Congress couldn't agree on spending, the government twice ran out of funding: from Nov. 14-19, 1995, and from Dec. 16, 1995 to Jan. 6, 1996.

About 285,000 federal employees were sent home without pay and a further 476,000 were forced to work without pay. Clinton said on Jan. 20, 1996, that the shutdowns had cost the federal government a total of $1.5 billion, or $2.1 billion in today's dollars—a number that does not include indirect costs. (The total nonmilitary federal workforce has fallen from 2.92 million at the end of 1995 to 2.84 million at the end of 2009, according to the U.S. Office of Personnel Management.) When the shutdowns ended, all employees had back salaries paid.

.....

• A shortage of federal funds eventually led 11 states and the District of Columbia to stop providing unemployment benefits when they couldn't or wouldn't fill the gap with their own funds. Other benefits were slowed or stopped entirely: Veterans stopped receiving some payments, including insurance death claims and checks for education provided by the GI Bill. Delays hit recipients of federal welfare programs and adoption-assistance services, along with children in foster care and in the Head Start early childhood program. The Bureau of Indian Affairs closed, cutting off assistance payments to 53,000 people, while about 25,000 American Indians also stopped receiving checks for oil and gas royalties.

.....

About 200,000 Americans were left waiting for new passports after the State Dept. stopped processing applications. Visa applications by foreigners were left unprocessed, stacking up at a rate of 20,000 to 30,000 per day.

• Government economic reports that investors watch closely were stopped. Reports that might be blacked out this time include the January trade balance on Mar. 10 and data on February housing starts and building permits, due out on Mar. 16.

• Work on 3,500 bankruptcy cases was suspended. About half the employees of the Small Business Administration were placed on furlough, leading to 260 small businesses not receiving loans each day, according to a White House summary written in January 1996.

• National parks, national forests, and other federal monuments and museums were shut. In January 1996, Bloomberg News reported that kayakers and rafters were cut off from the Colorado River because they couldn't get permits.

• While federally funded health care such as Medicare continued, the National Institutes of Health stopped accepting new patients in clinical research programs. The Centers for Disease Control halted surveillance of diseases such as HIV/AIDS and influenza.

• The government temporarily closed the Federal Parent Locator Service, which helps find parents who are delinquent in making child support payments.

And there's much more in this detailed report.

At a time when the phrase "self-sustaining recovery" is gaining traction and credence, the yahoos in Washington want to completely derail the recovery. Great.

Yesterday's Market


Monday, March 28, 2011

Are Durable Goods Orders Showing an Upcoming Slowdown?


This chart is bothering me. Notice that a large number of data points in the last year are concentrated in the 192,000-196,000 area. There have been some strong moves above that area, but only three times. Now let's look at a longer time series.


On the longer scale, notice that durable goods orders are still far below their peaks from the end of the last expansion. In addition, note their rate of ascent appears to have stalled, which is revealed in more detail on the following chart:


Above is a chart of durable goods orders on a scale of 100. Notice that orders have stalled in the 75-80 range for the last 10 months -- which is below previous levels.

Durable goods orders are a very volatile series. However, their current lack of movement is beginning to concern me regarding the big picture.

The Week Ahead

Stocks: The rally over the last week or so has been very weak. Volume has been down and half of the upward moves occurred at the open with no intra-day follow through. The SPYs are still contained by a downward sloping trend line. However, the IWMs (which have led the market higher) have broken through their trend line but also have a declining MACD. While the underlying technical are still OK (for example, the MACD is about to give a buy signal on the SPY) the underlying economic situation (weakening durable goods orders, high gasoline prices, increasing agricultural prices) are concerning.

Bonds: The IEFs are in a clear downward trend for the last eight days. Prices are currently right at the 200 day EMA. The 10 and 20 day EMA are both moving lower, but the EMAs are in a tight bunch right around the 200 day EMA. Prices are right below a short-term trend line. Additionally, before the latest rally, prices were moving lower in a move that looked like a flight from safety to risk, which is a standard move at this point in the market cycle. The real question is has the negative fundamental news which rallied the bond market over the last few weeks ameliorated to the point where bond traders are comfortable selling bonds into the risk markets again?

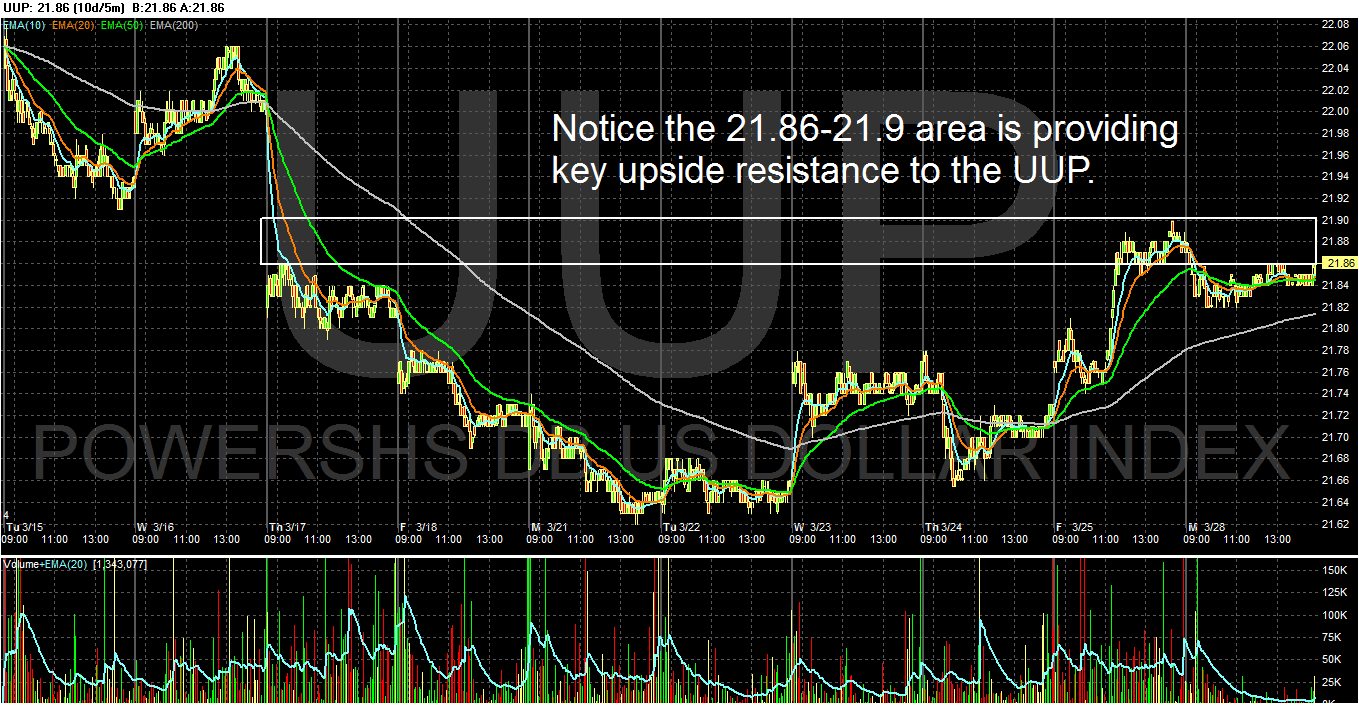
The dollar: the UUP ETF is still in a confirmed downtrend and has been since the beginning of the year. All the "rallies" have been upward sloping pennant patterns that hit resistance at an EMA and then moved lower. The ETF has moved through the 22 price area, which was an area of major technical support and is now moving higher, probably to retest the 22 price area. In addition, the market widely expects the EU to raise interest rates before the Fed, making the Euro a more attractive bullish play.

Oil: Oil is consolidating in a triangle pattern. Right now, the primary question is which direction will prices break in.

Yesterday's Market


Friday, March 25, 2011

Weekly Indicators: Accumulating signs of a slowdown Edition

- by New Deal democrat

In the rear-view mirror department, 4th Quarter 2010 GDP was revised back up to 3.1%. Monthly data reported this week, however, was depressing. New home sales were recorded at an all-time low, although balanced against December's big uptick, the last three months are still better than the three months previous to them. More ominous, however, was the big decline in consumer confidence, and in particular expectations about the future. These are the worst in 2 years, and are a leading indicator. Durable goods also came in very weak. While this is a volatile indicator, over the last 6 months it has trended sideways. Did I mention that this is also a leading indicator? In short, Oil's choke collar is biting into the economy.

Turning now to the high-frequency weekly indicators:

The BLS reported that Initial jobless claims last week were 382,000. The 4 week average is 385,000. This is the fifth week in a row that this number has been initially reported below 400,000. This bodes well for the next payrolls report.

On the other hand, Oil was trading at about $105.65 a barrel Friday midday, the third full week it has been above $100. It remains at a level above 4% of GDP. There WILL be a significant economic damage and I believe we are now observing the start of that damage. Gas at the pump declined $0.01 last week to $3.56 a gallon. Gasoline usage again was slightly lower than last year. I expect this comparison to deteriorate so long as the oil price spike continues.

Railfax was up 5.7% YoY. Baseline traffic is now no higher than last year's levels, and cyclical traffic is only slightly higher. Waste materials are now below last year's levels. Shipments of motor vehicles, however, continued to improve YoY. Intermodal freight's rate of advance over last year declined last week. With the exception of motor vehicles, rail freight is now also signalling a significant slowdown.

The Mortgage Bankers' Association reported an increase of 2.7% in seasonally adjusted mortgage applications last week. This series has meandered generally in a flat range since last June. On the plus side, this is the longest time since 2006 that this series has gone without a major decline. Refinancing also increased another 2.7%, but despite that remains near its lows since last July.

The American Staffing Association Index remained at 91. This series has stalled at the 90-91 level for 6 weeks. It is signalling stagnation, not growth, and is stalled relative to its pre-recession peak.

The ICSC reported that same store sales for the week of March 19 rose 3.0% YoY, and decreased -0.1% week over week. Shoppertrak reported a 4.0% YoY gain for the week ending March 19, and a WoW gain of 3.9%. Unlike almost every other series, these two series' YoY comparisons have been improving over the last month.

Weekly BAA commercial bond rates declined -.10% to 5.98%. This compares with a -0.15% deline in the yields of 10 year treasuries to 3.29%. Both series are down from recent highs. This was the second week in which the relative move in corporate bonds signalled weakness.

M1 was unchanged w/w, up 0.5% M/M, but up a strong 9.0% YoY, so Real M1 is up 7.8%. M2 was down -0.3% w/w, up 0.3% M/M and up 4.6% YoY, so Real M2 is up 2.4%. M2 is back into the "yellow zone" below 2.5%, but M1 is still strongly in the "green zone" as it has been for several years.

Adjusting +1.07% due to the recent tax compromise, the Daily Treasury Statement showed that for the first 17 days of March, $135.5 B was collected vs. $134.6 B a year ago, for a gain of +0.6% YoY. For the last 20 days, $162.1 B was collected vs. $150.9 B a year ago, for a gain of $11.2 B, of over 7.4%. I suggest using this series with extra caution, because the adjustment for the withholding tax compromise is only a best guess, and may be significantly incorrect.

For the first time since mid-2010, the LEI may have a negative month in March. Consumer confidence, durable goods, and (Feb.) hosuing permits are all down strongly. The stock market and money supply look like they will record essentially neutral readings. Only the bond spread yield and initiall unemployment claims look like strong positives. It is worth noting, on the plus side, that ECRI's growth indicator continues to be positive, and they are not revising their forecast of continued growth. Neverthelss, as I said at the outset, it appears that the Oil choke collar is indeed beginning to constrict the economy.

Finally, the Census Bureau reported today that the Latino population has increased to 50.5 million people, or about 16% of the total US population. All of which make Los Estados Unidos the third most populous Latin American country after Brazil and Mexico (surpassing Argentina and Columbia). And on that note: Buen fin de semana!

4Q GDP Up 3.1%

From the BEA:

Real gross domestic product -- the output of goods and services produced by labor and property located in the United States -- increased at an annual rate of 3.1 percent in the fourth quarter of 2010, (that is, from the third quarter to the fourth quarter), according to the "third" estimate released by the Bureau of Economic Analysis. In the third quarter, real GDP increased 2.6 percent.

The GDP estimate released today is based on more complete source data than were available for the "second" estimate issued last month. In the second estimate, the increase in real GDP was 2.8 percent (see "Revisions" on page 3).

The increase in real GDP in the fourth quarter primarily reflected positive contributions from personal consumption expenditures (PCE), exports, and nonresidential fixed investment that were partly offset by negative contributions from private inventory investment and state and local government spending. Imports, which are a subtraction in the calculation of GDP, decreased.

The fourth-quarter acceleration in real GDP primarily reflected a sharp downturn in imports, an acceleration in PCE, an upturn in residential fixed investment, and an acceleration in exports that were partly offset by downturns in private inventory investment, in federal government spending, and in state and local government spending, and a deceleration in nonresidential fixed investment.

In general, this is a good report. The reasons for the increase were broad based -- investment, exports and PCEs added to growth. Imports dropped -- which is something we shouldn't count on this quarter. Also, several news stories noted that with high gasoline prices negatively impacting consumer sentiment, the 1Q number will probably be lower.

Is It Time For Another Home Buyer Tax Credit?

Recent news from the housing market has been extremely concerning. Existing home sales appear to have stabilized somewhat, but at a low level and new home sales hit a record low. Credit conditions for new homes are also tightening, further hampering the process. There is an overhang of foreclosed properties depressing prices. And finally, homeowners equity is low, indicating that getting people out of homes they can't afford will be much harder. Simply put, there are myriad number of reasons to consider helping the housing market in some form or another.

As such, we need to revamp the home buying tax credit. Will this "distort the market?" Yes. However, the market is already distorted to the low end, so consider this an equilibrium move. While some will argue we shouldn't use the tax code for this, I'll respond as a tax lawyer -- the code is littered with special interest tax giveaways. One that helps an ailing economic sector makes just as much sense. However, I would condition the credits phase out to something tied to the overall inventory of homes or months of available inventory number -- and, phase it out gradually; don't make it a "here today, gone tomorrow" affair.

Just my thoughts on the topic.

Yesterday's Market


Thursday, March 24, 2011

Declining Initial Jobless Claims suggest improving March jobs report

- by New Deal democrat

For the past few months, I have been running a scatter graph of initial jobless claims (left) and monthly jobs gained/lost (bottom) since jobless claims hit their peak in March 2009. Blue is all private jobs, red includes government jobs as well (except I have excluded the March through August 2010 period which was distorted by census hiring and firing):


As I have previously pointed out, there is a nearly linear relationship. So long as initial claims continue under 400,000, we should expect robust monthly jobs reports (with a very big +/-125,000 variance, however).

So, why an update on this issue now? The BLS conducts its survery during the week just before mid-month. The 4 week average of initial jobless claims now is about 15,000 less than it was 4 weeks ago, when over 200,000 private jobs were added to the economy. In short, subject to the huge variance desribed above, and keeping in mind that it will (probably) be described as "disappointing" at first, only to be revised higher in the ensuing two months, we can expect a pretty good March jobs report a week from tomorrow.

Texas Drought To Increase Wheat and Cattle Prices


The worst Texas drought in 44 years is damaging the state’s wheat crop and forcing ranchers to reduce cattle herds, as rising demand for U.S. food sends grain and meat prices higher.

Texas, the biggest U.S. cattle producer and second-largest winter-wheat grower, got just 4.7 inches (12 centimeters) of rain on average in the five months through February, the least for the period since 1967, State Climatologist John Nielsen- Gammon said. More than half the wheat fields and pastures were rated in poor or very poor condition on March 20.

Dry conditions extending to Oklahoma, Kansas and Colorado may cut crop yields in the U.S., the world’s largest exporter, as too much moisture threatens fields in North Dakota and in Canada. Wheat futures in Chicago are up 50 percent in the past year, after drought in Russia and floods in Australia hurt output and sent global food prices surging. Wholesale beef reached a record this week, and the U.S. cattle herd in January was the smallest since 1958.

.....

Parts of Texas, Oklahoma, Kansas and Colorado had less than 25 percent of normal precipitation in the past 30 days, National Weather Service data show. The region may get some help from storms beginning March 26, which may drop about a half an inch of rain, said Joel Widenor, a meteorologist at the Commodity Weather Group LLC in Bethesda, Maryland.

“In a lot of places, there’s very little moisture in the ground,” said Nielsen-Gammon, the state climatologist who also is a professor of atmospheric sciences at Texas A&M University in College Station. Low subsoil moisture “will make us very susceptible to drought this summer if we have extended patches of dry weather,” he said.


Someone Finally Notices the Declining Labor Force

From MarketBeat:

The Congressional Budget Office released a report today, projecting labor force participation through 2021. Labor force participation peaked in the late 1990s at around 67% as Baby Boomers reached peak working age and the entrance of women into the work force plateaued. It have been dropping since, with the decline exacerbated substantially by the recession as people dropped out of the labor force. The participation rate stood at 64.2% in February, down from 66% in December 2007 when the recession began. The CBO expects it to decline to 63% by 2021


This is something I noted last month in this post where I commented:

The participation rate increased from a little after 1960 until 2000 and then started to decrease. The question for this decrease is "why?"

There are two fundamental reasons. The first is that women as a percentage of the labor force increased and stagnated over the same time period. As women entered the workforce starting in the early 1960s the labor force participation rate (the percentage of the population either employed or unemployed) increased in sympathy. However, women as a percentage of the labor force plateaued in 2000 and dipped slightly thereafter, leading the labor force and therefore the participation ratio to decline.

Secondly, there is the issue of the baby boomers or "someone born during the demographic birth boom between 1946 and 1964.[9]" Someone born in 1946 would turn 60 in 2006 and be 65 in 2011. As these people have retired, they have left the labor force (they are neither employed or unemployed). Hence, we have the second reason for the decrease in the labor force participation rate -- retiring baby boomers.


This is an incredibly important development -- and one that I don't think people have fully accepted yet.

Here is a link to the CBOs report

Yesterday's Market


Wednesday, March 23, 2011

Thoughts on Keynes

Regarding NDDs' piece below a general debate that has occurred in the Economic Blogsphere over the last week or so (see this post from DeLong and this from Krugman) that centers around Keynes and the success of the New Deal during the Great Depression. Personally, I find these debates stupid and tiresome for several reasons.

First, they are usually derived from a persons political beliefs rather than economic data. There is a group of people on the far right who are against any government action regardless of, well, anything (be it fact, theory or whatever). Data and facts are meaningless. They debate entirely from a political perspective and their ideas are derived from a set of beliefs regarding the proper role of government in society. This is a great debate to have -- but it's not an economic debate.

Second, here's the basic fact about the New Deal: it worked. The country experienced tremendous growth rates in terms of both GDP growth and job creation. As NDD has demonstrated below, GDP growth was some of the strongest on record and the unemployment rate dropped sharply. NDD and I wrote a series of articles on the topic which are located at the following links (Part I, Part II, Part III, Part IV). In other words, Keynes' basic theories -- which formed the basis of the policy response in the Great Depression -- were validated by objectively observable facts.

Third, they assume an all or nothing approach to economics that I find, well, really stupid. By all or nothing, I mean there is an inherent belief that Keynes is 100% right or wrong or Friedman (who is usually heralded as the leader of the anti-Keynes movement) is 100% right or wrong, etc... What these arguments completely miss is the idea that maybe both are right and both are wrong in their own way all at the same time. Both and IS/LM model and AS/AD concepts make sense at certain times and in certain ways. Neither has a 100% hold of reality. To assume that one school of thought is so certain that it completely overshadows other work is pure hubris.

Here's the basic facts: Keynes was right about some very important things. For example, the fact that prices are sticky provides a big problem for classical economic theory. Government intervention (leaning against the wind) works when done properly (often lost in this debate is that governments are suppose to decrease their spending during expansions). Demand is a very important element of the national economy; without it, well, there isn't a whole lot of purpose in producing anything. I could go on, but you get the idea.

My .02 cents (inflation adjusted).

You don't get to make up your own facts: FDR vs. W edition

- by New Deal democrat

On Friday I prefaced my usual Weekly Indicators column with an observation that we were continuing to use virtually the same set of policies that had previously brought us the weakest GDP and jobs expansion in 80 years, and yet hoping that they would give us what we really need to bring down the horribly high rate of long term unemployment - for which we would need an expansion equivalent to the top two or three expansions in that time.

Well, over on the right side of this page you can see the "Seeking Alpha contributor" link, and over the weekend Seeking Alpha decided to pick up this particular column. The comments (a dozen of them) show why economic policymaking in this country is so haplessly warped. FDR's New Deal morphed into a disaster, while W's economy was lauded. I have a memo for those commenters: everybody is entitled to their own opinions, but you don't get to make up your own facts.

Here is a bar graph of the percentage of annual GDP growth for the last 81 years:


The simple fact is, in GDP terms the New Deal recovery was the strongest economic expansion of the last 80 years, ex-World War 2. W's was the weakest.

Here is a graph of annual employment growth since 1939:


Once again, W's economy was the weakest period of employment growth in that entire period. As for the New Deal, while it predates that Fed graph, we know from the US Census Bureau records that it produced the following employment growth (in thousands)

1932 38,630
1933 40,247 (+125,000/mo)
1934 41,284 (+87,000/mo)
1935 44,760 (+290.000/mo)
1936 47.733 (+250,000/mo)

Considering that the working age population was only about 1/4 of its current size, that means in today's terms the New Deal created on average +9 million jobs annually, or +752,000 jobs a month!

Again, the simple fact is, in employment terms the New Deal recovery was the strongest expansion of the last 80 years, ex-World War 2. W's was the weakest.

Now let's look at the unemployment rate. Here is a graph of annual change in the unemployment rate since 1949:


Once again, W's economy was the weakest period for the decline in the unemployment rate in that entire period. As for the New Deal, while it predates that Fed graph, we know from the US Census Bureau records that it produced the following declines in the unemployment rate:

1932 22.89%
1933 20 90%
1934 16.20%
1935 14.39%
1936 9.97%

That's an average decline in the unemployment rate of 3.5% a year. For the third time, the simple fact is, in terms of the decline in the unemployment rate the New Deal recovery was the strongest expansion of the last 80 years, ex-World War 2. W's was the weakest.

[Source for Payroll and Unemployment data in the 1930's: Weir, David R. “A Century of U.S. Unemployment, 1890-1990: Revised Estimates and Evidence for Stabilization.” Research in Economic History 14 (1992): 301-346; chart on pp. 2-82 - 2-83.]

Those who argue that the New Deal was a failure base those arguments on counter-factuals: imaginary worlds where there was a do-over using laissez-faire capitalism, based on the work of UCLA Profs. Ohanian and Cole. Bonddad and I already debunked this argument, the assumptions of which explicitly include that the Great Depression would have spontaneously cured itself starting in April 1933 anyway!

Everyone is entitled to their opinions. And there is nothing inherently wrong with basing those opinions on imaginary counter-factuals. But you don't get to make up your own facts. The facts are, to substantially bring down the number of the long-term unemployed, we need a recovery that produces the kind of numbers in terms of GDP growth, employment growth, and unemployment rate declines that are close to those of the New Deal. But we are trying to accomplish this with fiscal policies that are close to those that brought us the poorest rate of GDP growth, employment growth, and unemployment rate declines since then.

Yesterday's Market


Tuesday, March 22, 2011

And now, for something completely different ...

- by New Deal democrat

Have earthquakes, tsunamis, nuclear accidents, undeclared wars, general rightwingnuttery, or just snowstorms in spring got you down? Do you need to work out a little frustration?

Allow me to introduce you to FPS Russia:


I feel better already!

Commodity Prices Are Spiking Because of Demand


According to some, the evil Wall Street speculators are behind the recent run-up in world commodity prices. However, as this chart shows, commodity prices and industrial production are nearly perfectly correlated. In addition, the middle class is growing, which means we're seeing an increase in demand for nearly everything such as

1.) Oil -- more people are driving cars
2.) Cattle -- more people want different food, such as beef
3.) Cotton -- more people want different clothes to wear
4.) Corn -- is increasing because of biofuels, the increased demand for beef (corn is fed to beef) and the increases in other grains, which typically trade in high correlation.
5.) Wheat is increasing because of constrained supply, which led to output quotas and then mass purchases to ensure adequate domestic supply.
6.) Copper is rising with industrial production


Hat Tip Mark Thoma

The Mind of A Contrarian


From Bloomberg:

Warren Buffett, whose Berkshire Hathaway Inc. (BRK/A) has a bullish derivative bet on Japan’s benchmark stock index, said the country’s record earthquake created a buying opportunity for equity investors.

“If I owned Japanese stocks, I would certainly not be selling them because of the events of the past 10 days or so,” said Buffett, speaking to reporters in the South Korean city of Daegu. “Something out of the blue like this, an extraordinary event, really creates a buying opportunity.”

The March 11 quake and tsunami, which caused the worst nuclear disaster in 25 years, may result in losses of $200 billion to $300 billion, with most of the costs uninsured, according to Risk Management Solutions Inc. Japan’s Nikkei 225 Stock Average has declined 12 percent since March 10. Markets in the nation are closed today for a public holiday. The iShares MSCI Japan Index Fund (EWJ), an exchange-traded fund that tracks the country’s stocks, gained 2.6 percent at 1:24 p.m. in New York.

Buffet isn't the only one who's noticed this is a good time to buy Japanese stocks.
Marketbeat notes that Capital Economists David Madani agrees, along with a recent cover story on Barron's.

I realize these statements seem cold and calculating, but they bring up a good point about when and how to invest. Ideally, the best time to buy is when everyone is selling and sell when everyone else is buying.

Here's a chart of the EWJ ETF which has already bounced back nearly 14% since the earthquake bottom:


Yesterday's Market


Monday, March 21, 2011

DeLong Smackdown

Over at his blog, Professor DeLong completely destroys a fellow economists who made the following argument:

Keynesianism has conquered the hearts and minds of politicians and ordinary people alike because it provides a theoretical justification for irresponsible behaviour. Medical science has established that one or two glasses of wine per day are good for your long-term health, but no doctor would recommend a recovering alcoholic to follow this prescription. Unfortunately, Keynesian economists do exactly this. They tell politicians, who are addicted to spending our money, that government expenditures are good. And they tell consumers, who are affected by severe spending problems, that consuming is good, while saving is bad. In medicine, such behaviour would get you expelled from the medical profession; in economics, it gives you a job in Washington...


As DeLong notes:

Zingales's claim--that because the current crisis is a trust crisis that has left the economy short of safe high-quality liquid assets we cannot restore employment by having the government build roads and finance road construction by issuing trusted safe high-quality liquid assets--that claim is so incoherent as to reveal nothing more than a failure on Zingales's part to think any of the issues through for more than a weekend. Zingales is a smart guy. But he is also pig-ignorant about what economists have thought and said in the past. And because he is pig-ignorant, he has mentally disarmed himself.


DeLong next quotes a number of modern day economist who argued against the stimulus plan, saying such thought was backward thinking, out-of-date etc... This is a perfect example of really stupid smart people. First, consider that government spending is part of the GDP equation (C+I+(net exports)+G (GOVERNMENT SPENDING), indicating that a positive contribution from government spending would increase GDP and a negative contribution from government spending would decrease GDP. That's called simple math. Also consider that every government that has implemented austerity measures has seen slower growth. I've documented the data several times (see here and here). That's data -- as in what happens in the real world when certain things are tried. Hell, even Mish noted that austerity measures were slowing down economic growth after calling for those same measures. In short, these professors are so blinded by ideology that they can't see what actually happens in the real world when they do certain things.

Certain kinds of government expenditures are good and at certain times. For example, infrastructure spending is good as it creates the physical goods on which the economy grows. Ever wonder why the U.S economy grew strongly in the 1960s? Take a look back to the 1950s when the national highway system was proposed and started. The ability to move more goods and services from point a to point b increases the supply and demand of those goods for all parties involved. Again, this is not that complicated. However, it does involve reality, which seems to be lacking in a variety of economic departments across the country.

Initial Unemployment Claims Looking Better


The above picture shows the 4-week moving average of initial unemployment claims continues to move in a positive direction. Let's take a look at the relationship between initial claims and the unemployment rate:


Notice that in the late 70s and early 80s there was a tight relationship between initial unemployment claims and the unemployment rate. However, this relationship started to become more elongated starting with the recovery of the early 1990s and has continued to this day. This means there is now a looser relationship between these two numbers.

The Week Ahead

The SPYs topped out in near 134.5 and have fallen to 125.5 -- a drop of about 6.7%. The IWMs -- which led the market higher -- have fallen from 83.5 to 78 for a drop of 6.6% and the QQQQs have fallen from about 59 to 54, or a drop of about 8.5%. All three averages are below their respective 10, 20 and 50 day EMAs. The volume reading on all the averages have been elevated. Right now, this is a standard correction that cleans out some of the shaky money. In fact, as the blog Traders Narrative notes, current sentiment readings are pretty bullish from a contrarian point of view. The real question is how far will it continue. For the SPYs, there's strong support in the 127 and 124 area, making them key support levels for the week. On the upside, the primary question is will the averages close above or below the EMAs?

The IEFs are now above the 200 day EMA and are forming a short, downward sloping, pennant formation. The close above the 200 day EMA is technically significant as it indicates a possible shift from a bear to a bull market. I still think this rally is short-lived and more a reaction to world events than a rethinking of the economic background. However, the key point moving forward for this part of the market is what happens when prices -- which are currently moving downward -- hit the EMAs as the pennant moves lower?

Oil has fallen from its sharp highs caused by the Libyan situation, but is still consolidating gains above the $100 handle. The key technical areas with this market are the 106 level -- where prices reached their latest peak -- and 98 -- where there is a lot of technical support and is also right about the current 50 day EMA. Movements within this boundary are pure day to day noise. As always with this market, be cautious as there are plenty of wild cards in the mix.

The UUP closed below the 22 area which is a very important long-term technical support area that was first established in 2008. This ETF does not correspond directly to the U.S. dollar index, but is handy because it allows trading for retail investors in the currency market. The close below a major technical level is always a bearish development, and this time is no different. Expect a retesting of the 22 level at some time in the next few weeks.

Basically, we're in the middle of a pure market correction that looks an awful lot like profit taking. We've had a good run in the equity markets for some time, so a selling period is welcome and warranted - as is the sell--off in some of the commodity markets. Current world events have put a safety bid in safer assets like the Treasury market. So long as the activity is disciplined we're fine. What we want to be on the look-out for is the random, wild card event that adds to volatility.