- by New Deal democrat
Monday, April 17, 2023
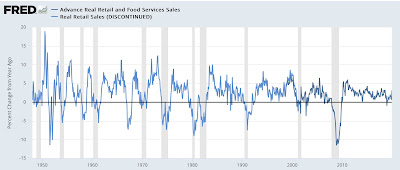
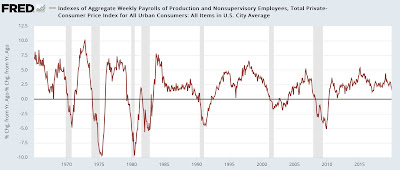
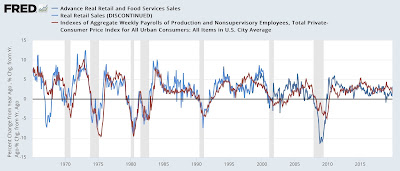
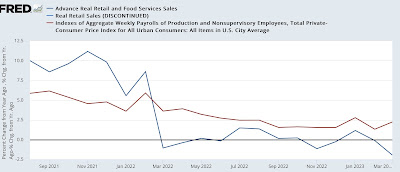
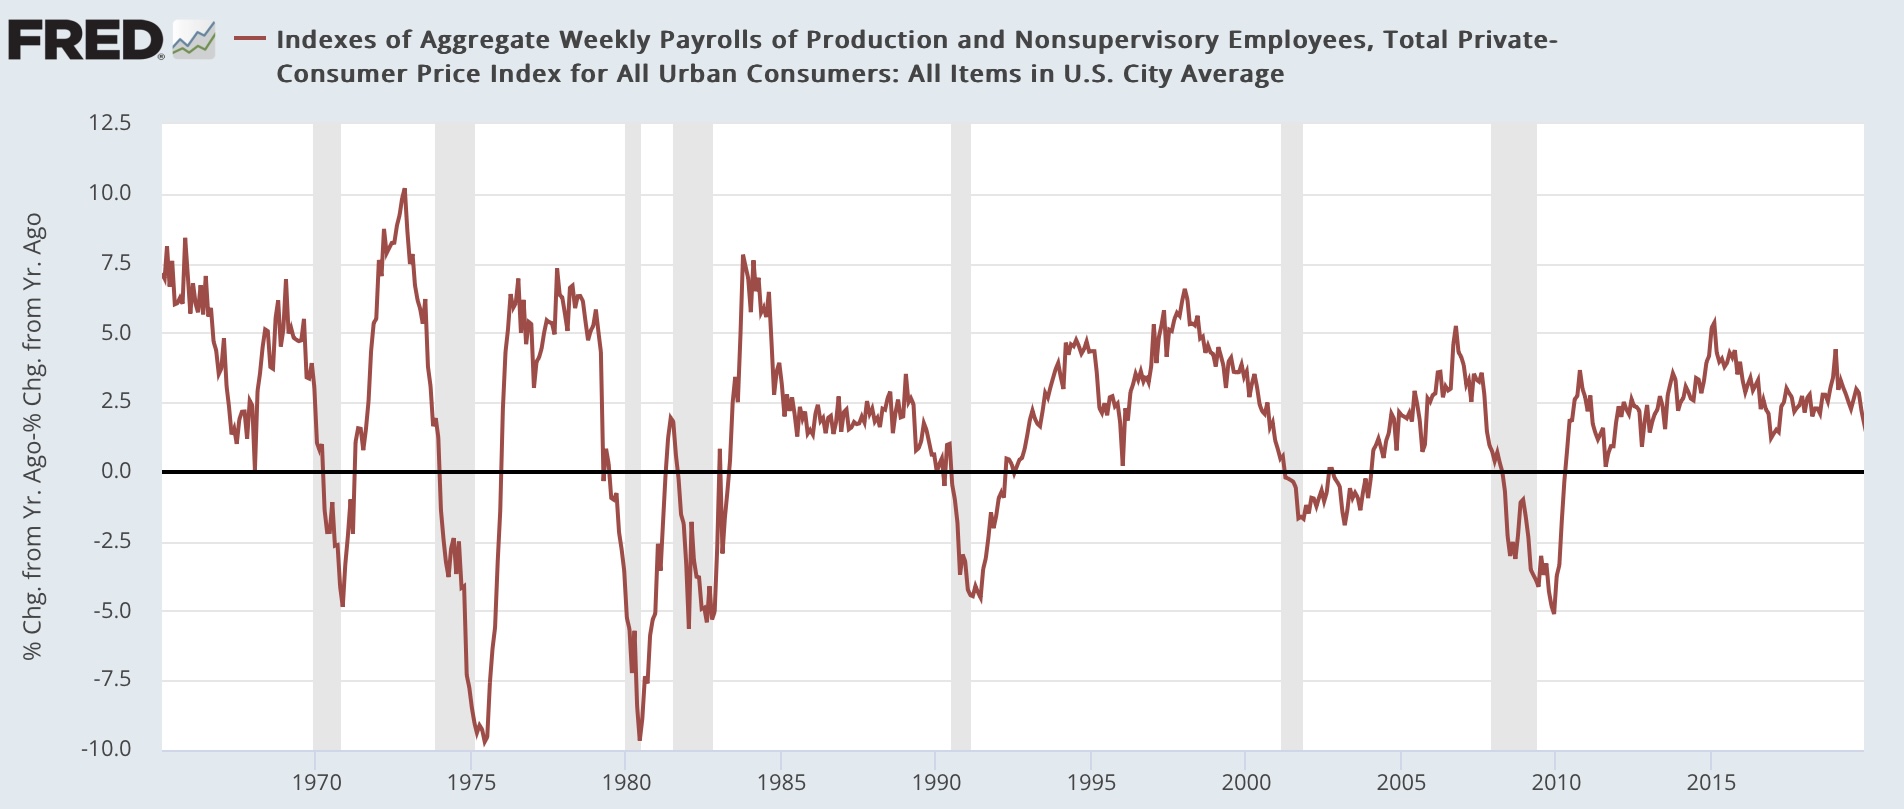
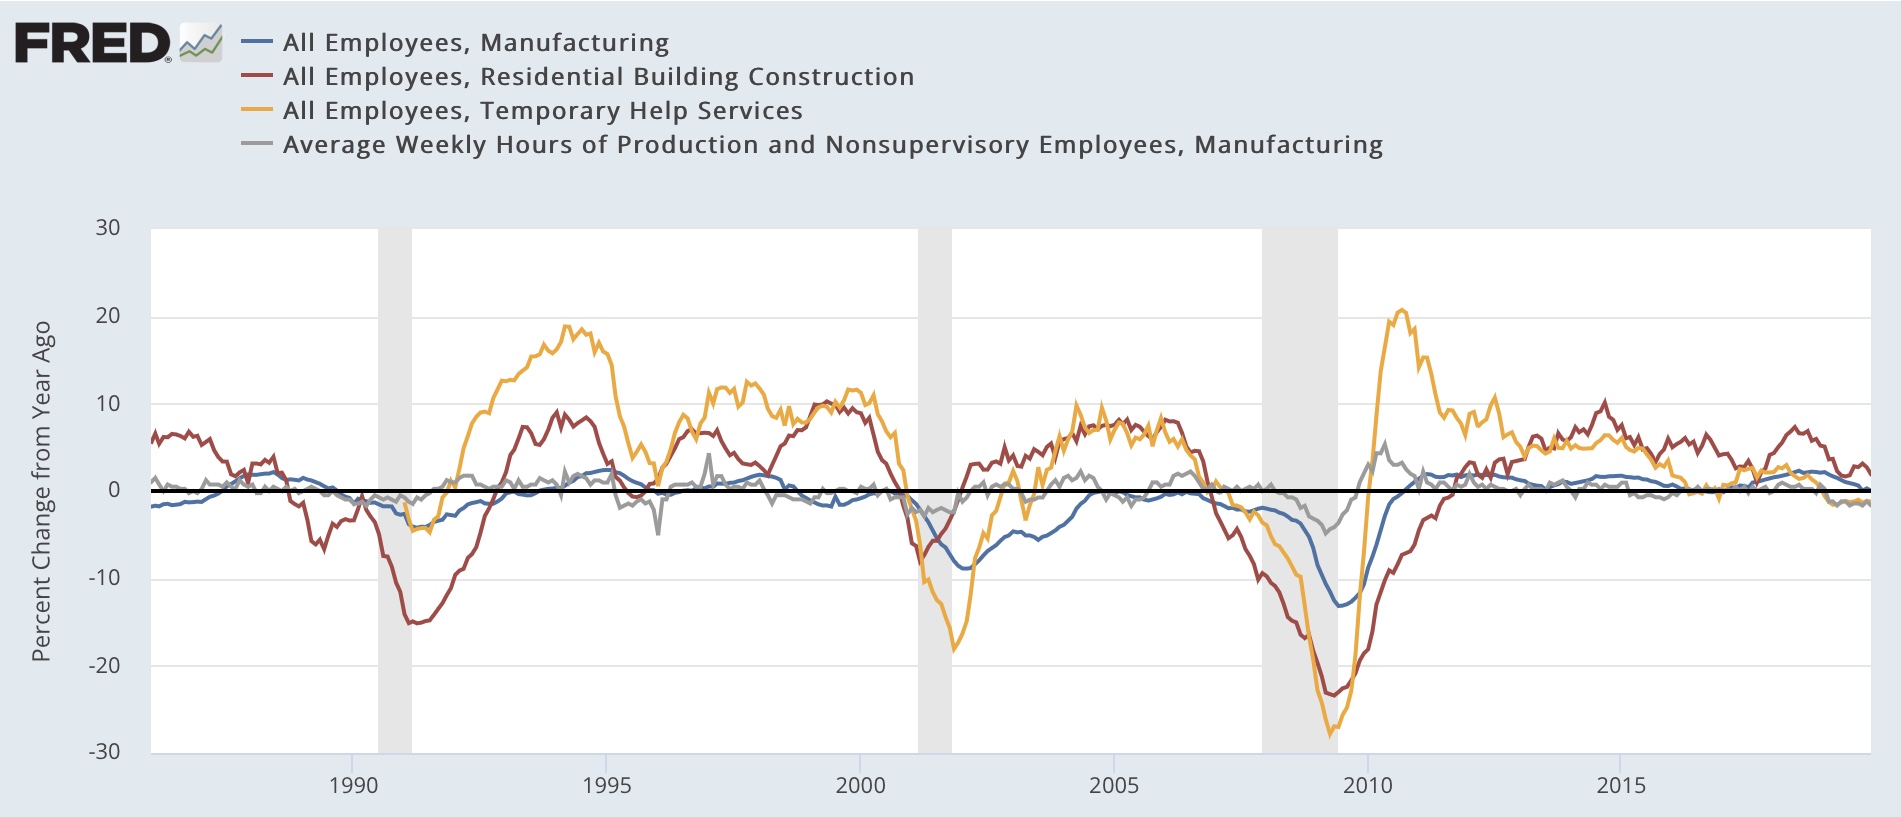
Two “fundamental” indicators for the American middle/working class and the economy
Saturday, April 15, 2023
Weekly Indicators for April 10 -14 at Seeking Alpha
- by New Deal democrat
My ‘Weekly Indicators’ post is up at Seeking Alpha.
The slow drip-drip-drip of deceleration generally continues. Perhaps most significantly, YoY consumer spending as measured by Redbook sank to a new post-pandemic lockdown low of only +1.5%. But other coincident indicators in particular, like tax withholding, appear resilient.
As usual, clicking over and reading will bring you up to the virtual moment as to the economy, and reward me a little bit for my efforts.
Friday, April 14, 2023
Real manufacturing and trade sales probably rose to a new record high in February; may have declined in March
- by New Deal democrat
Real manufacturing and trade sales is one of the 4 monthly coincident indicators most monitored by the NBER to determine whether the economy is in expansion or recession. Because the reporting of this series lags badly (by 2 months), I have developed several placeholders to estimate it on a more timely basis.
Positive revisions make for a good March industrial production report
- by New Deal democrat
With these revisions and additions, industrial production is still -0.5% below its September peak (a big improvement from last month’s original -1.8%), while manufacturing production (red) is -1.2% below its peak from last October, also an improvement from the original -2.0% last month.
March real retail sales lay an egg, suggest downturn in nonfarm payrolls by the end of summer
- by New Deal democrat
After a quiet early part of the week, today we get a deluge of data: retail sales and industrial production for March, and total business sales for February. Because real total business sales are one of the 4 big coincident indicators tracked by the NBER, and because retail sales are about 1/3rd of the total, and industrial production helps us estimate the rest, after the data comes out I can give estimates of the *real,* not just nominal, values for both February and March.
Thursday, April 13, 2023
Initial claims continue to warrant yellow caution flag
- by New Deal democrat
Initial jobless claims last week rose 11,000 to 239,000. The more important 4 week average rose 2,250 to 240,000. Continuing claims, with a one week delay, decreased 13,000 to 1,823,000:
Wednesday, April 12, 2023
Properly measured, consumer inflation is only about 3.0% YoY, and the economy has experience DEflation since last June
- by New Deal democrat
Tuesday, April 11, 2023
Scenes from the March employment report 2: unemployment recession indicators
- by New Deal democrat
A reminder: I may be offline for the next couple of days. In the meantime, yesterday I looked at the 5 leading indicators contained in the employment report, and summarized how they either signal recession now or within the next 3 to 6 months.
Monday, April 10, 2023
Scenes from the March employment report 1: leading sector indicators
- by New Deal democrat
There’s no significant economic news this week until Wednesday’s CPI report, and as a side note, I might be offline for a day or two later this week. In the meantime, today and tomorrow let’s take a look at some of the important information from last Friday’s employment report.
Saturday, April 8, 2023
Weekly Indicators for April 3 - 7 at Seeking Alpha
- by New Deal democrat
My Weekly Indicators post is up at Seeking Alpha.
Probably unsurprisingly, the big news this week was the effect of the revisions to the initial jobless claims data, and also the turning down of several sectors in the monthly jobs report.
Anyway, as usual clicking over and reading will bring you up to the virtual moment as to the data, and reward me a little bit for my efforts in putting it all together.
Friday, April 7, 2023
March jobs report: leading sectors turn down in a pre-recessionary, but still quite positive, report
- by New Deal democrat
Here’s my in depth synopsis.
- 236,000 jobs added, the lowest number since December 2020. Private sector jobs increased 189,000, also the lowest since December 2020. Government jobs increased by 47,000. The three month moving average of growth declined 1,000 to 345,000.
- The alternate, and more volatile measure in the household report rose by 577,000 jobs. The above household number factors into the unemployment and underemployment rates below.
- U3 unemployment rate declined -0.1% to 3.5%.
- U6 underemployment rate also declined -0.1% to 6.7%.
- January was revised downward by -32,000, and February was revised upward by 15,000, for a net decrease of -17,000 jobs compared with previous reports.
- the average manufacturing workweek, one of the 10 components of the Index of Leading Indicators, declined was unchanged at 40.7, down -0.9 hours from February peak last year of 41.6 hours.
- Manufacturing jobs declined by -1,000.
- Construction jobs declined for the first time since January 2022, by -9,000.
- Residential construction jobs, which are even more leading, increased by only 800, but last month’s gain of 1,200 was revised to a loss of -2,400, suggesting January may have been the peak for this sector.
- Temporary jobs, which have generally been declining late last year, resumed that decline, by -10,700.
- the number of people unemployed for 5 weeks or less declined -17,000 to 2,272,000.
- Average Hourly Earnings for Production and Nonsupervisory Personnel increased $.09, or +0.3%, to $28.50, a YoY gain of 5.1%, the lowest YoY gain since July of 2021.
- the index of aggregate hours worked for non-managerial workers rose 0.2%.
- the index of aggregate payrolls for non-managerial workers rose 0.4%, but continued its deceleration to 7.2% YoY, the lowest since March 2021, although still more than 1% higher YoY than inflation as of the last reading.
- Leisure and hospitality jobs, which were the most hard-hit during the pandemic, rose 72,000, only -368,000, or -2.2% below their pre-pandemic peak.
- Within the leisure and hospitality sector, food and drink establishments added 50,300 jobs, and are now only -75,000, or -0.6% below their pre-pandemic peak.
- Professional and business employment rose 39,000. This series has also been decelerating consistently, and is now up 2.3% YoY, the lowest increase since March 2021.
- The Labor Force Participation Rate increased 0.1% to 62.6%, vs. 63.4% in February 2020.
- The number of job holders who were part time for economic reasons rose 35,000.
- Those not in the labor force at all, but who want a job now, declined -178,000 to 4.925 million, its lowest level since December 2019.
Thursday, April 6, 2023
Revisions cause initial claims, the last positive leading indicator, to capitulate
- by New Deal democrat
Beginning … [this week], the methodology used to seasonally adjust the national initial claims and continued claims reflects a change in the estimation of the models.Seasonal adjustment factors can be either multiplicative or additive. A multiplicative seasonal effect is assumed to be proportional to the level of the series. A large increase in the level of the series will be accompanied by a proportionally large seasonal effect. In contrast, an additive seasonal effect is assumed to be unaffected by the level of the series….Prior to the pandemic, the unemployment insurance claims series used multiplicative models to seasonally adjust the claims. Starting with March 2020, Bureau of Labor Statistics (BLS) staff, who provide the seasonal adjustment factors, specified both of the UI claims series as additive. After the large effects of the pandemic on the UI series lessened, the seasonal adjustment models were once again specified as multiplicative models. Statistical tests show that the UI series should, in normal times, be estimated using multiplicative adjustments.
Including those revisions, this week initial claims rose 18,000 to 246,000. The 4 week average declined 4,250 to 242,000. Continuing claims with a one week delay rose 6,000 to 1,823,000.
Here is what those revisions to weekly initial claims look like:
Here are the revisions to the 4 week average:
Because the revisions go back more than a year, the YoY% change in the numbers did not change very much compared with last week. Including the revisions, initial claims are now up 6.5% YoY (vs. 15.8% as reported last week), and continuing claims are up 11.6% (vs. 12.2%). The more important 4 week average is up 10.8% (vs. 11.0%).
Last week I wrote that the 4 week average of initial claims had crossed the 10% threshold for a yellow flag caution. I require two months in a row, and would need to see an increase to 12.5% YoY or above to warrant the actual red flag recession warning.
But even if initial claims improve somewhat from here, with these revisions the last positive leading indicator has capitulated.
Wednesday, April 5, 2023
One of the last of the positive short leading indicators rolls over
Tuesday, April 4, 2023
February JOLTS report shows further *relative* weakening in the jobs market
- by New Deal democrat
The February JOLTS report showed a weakening in almost all important trends.
Monday, April 3, 2023
Both manufacturing and construction continue to contract
- by New Deal democrat
As usual, we start the month with data on last month’s manufacturing activity, and the previous month’s construction activity. This month, both were negative.
Sunday, April 2, 2023
Weekly Indicators for March 27 - 31 at Seeking Alpha
- by New Deal democrat
I keep forgetting to put up this link on Saturdays, but you know where to find it: my Weekly Indicators post is up at Seeking Alpha.
The good thing about high frequency indicators is you can see what is happening with trends much more quickly than with monthly releases. The bad thing is that the drip-drip-drip can take forever!
Anyway, the fallout from SVB continues in the credit sector; and corporate profits look like they might take a major hit in the Q1 reporting season, which starts in a couple of weeks.
If you haven’t already done so, clicking over and reading will bring you up to date, and reward me a little bit for organizing the data for you.