Tuesday, October 15, 2013

Oil Should Be Moving Lower ...


Oil's chart is pointing lower.  The MACD is declining, the CMF is showing declining volume flow and the shorter EMAs (the 10, 20 and 50 day EMA) are all indicating declining prices.  However, consider this chart in the context of weekly price moves:


On the weekly chart, we have rising volume flow and momentum (despite the shorter term sell signal).  While the 10 and 20 week EMAs are moving lower, the 50 and 200 week EMAs are moving higher. 
 
The point here is to look at multiple time frames when thinking about price movement. 

Monday, October 14, 2013

Chinese Inflation Comes in Hotter Than Expected

This is up over at XE.com

What Are the Effects of Default?

The Washington Post has a really good piece that explains the overall impact of a default.  Here are some of the more important points:

Experts on federal finances say that money might be enough to make payments for a few days, but certainly not for more than two weeks. In any event, they say, President Obama will have to make untested decisions about who and what to pay because daily tax receipts will make up only about 70 cents of every dollar of necessary spending.

Economists roundly agree that no matter which course Obama chooses, a drop in federal spending that large would exert a huge drag on economic growth. And in contrast to what happens during a traditional downturn — the safety net expands to help the vulnerable — assistance to seniors and low-income people could be delayed or reduced if Congress doesn’t raise the debt ceiling.

.....

According to the Bipartisan Policy Center, which has done the most detailed analysis of federal finances in a debt-ceiling breach, administration officials would have to consider delaying or suspending tens of billions of dollars in critical payments to low-income people and seniors.

Under the most alarming scenario, as soon as Friday, payments to Medicare and Medicaid providers, unemployment benefits, Social Security checks and tax refunds would be postponed for one to four days.

Food stamps due to be distributed Oct. 25 could be held until Oct. 30. The same would happen to payments to defense contractors.

With huge payments due in early November, the situation would become grimmer. Nearly $60 billion in Social Security checks, veterans benefits and pay for active-duty troops is due Nov. 1. Those could be delayed nearly two weeks, according to the Bipartisan Policy Center’s analysis.

Washington Post floats my proposal to end the government shutdown crisis


- by New Deal democrat

Yesterday I made an out-of-the-box proposal to end the government shutdown / debt ceiling crisis in Washington. It boils down to the GOP agreeing to a permanent repeal of the debt ceiling law in return for Democratic concessions for a debt ceiling increase now.

This morning it was adopted by Greg Sargent of the Washington Post in an article called "A way out of the Crisis."

The trial balloon has now been floated. As Sargent correctly notes:
If Republicans refuse this request, it will be a clarifying moment: It will confirm Republicans are fully intent to use the threat of default as leverage to get what they want in later showdowns. And the refusal to renounce this tactic will become what kills any hopes of a compromise.  “If a deal fails on that basis, it becomes clear that Republicans are intent on using this as a weapon of extortion over and over again.”
A big thank-you to Greg Sargent, and if somebody else forwarded my post to him, a big thank-you to that person as well.

Market Analysis: US

The US did not release any economic data last week, so all we're left with is the performance of the markets.  Let's start with the SPYs:


Remember that the overall daily chart is losing upward momentum.  While we see a rally from mid-November 2011 to early August, we now have prices moving in more od a sideways pattern.  A big key to this chart is the declining momentum in the MACD.  Also note that volume flow has been weaker. 


What is most likely happening is an overall price consolidation as the markets wait to see what happens in Washington.  Notice the red line that connects the lows of late August and mid-October.  This line would be the lower line of a symmetrical triangle consolidation pattern.  Right now a price drop below 164.5/165 would be the key technical development lower, with a move below 162-162.5 being utterly deadly to the bulls.

Bulls would need to move the market about the 178 area for a break-out to occur

Sunday, October 13, 2013

A thought for Sunday: an out-of-the-box proposal to solve the debt ceiling crisis


- by New Deal democrat

On Thursday I wrote a post the thesis of which was pretty straightforward: when the threat by a sovereign to not pay any of its bills - including selective payment of those bills - goes from trivial to non-trivial, based on the increasing frequency of the threat and the increasing brinksmanship associated with that threat, I would expect buyers of that sovereign's bonds to price in the risk of even partial or selective default. Even though, to date, that sovereign had never in history defaulted on any of its obligations. Even if the government of that country chose to prioritize payment of bondholders over other obligations, I would expect the second-class parties to hire lawyers and try to freeze some or all of the payments to sovereign bondholders while they argued their case in court.

In fact, he more I've though about it since, the more it looks like the S&P downgrade of US debt in 2011 - due to that brinksmanship - wasn't political at all (the source of much criticism at the time), it was dowright prescient.

So here we are, only days away from what could be a calamitous economic event, casued entirely by voluntary actions of government, with no apparent way out.

Or is there? Here is an out-of-the-box suggestion:

The number 1 priority of the GOP is to extract one or more real concessions in return for its hostage-taking.

The number 1 priority of the Democrats is to make sure that hostage taking is not rewarded, so that the GOP never takes hostages again.

The parties are at loggerheads, and we have a crisis because these priorities appear to be intractable.

Except actually, they aren't.  *Both* priorities can be satisfied.

The secret is that the debt ceiling law itself is just that - only a law. It was enacted 100 years ago when the US put World War I on its credit card, causing the biggest US inflation of the 20th century.  Now that the US government has many continuing obligations, including Social Security and huge treasury debt payments, this law is a loaded loose cannon on deck, capable of inflicting great damage.  I am shocked that we haven't already seen further downgrades of US debt by credit agencies (but give it a day or two).

So, here is the out-of-the-box solution.  The democrats add a demand: they insist that the debt ceiling act itself be repealed, ending the chances of hostage taking forever.

The GOP rejects this.

Then the two parties negotiate what of the GOP's current demands the democrats are willing to concede, in return for the debt ceiling law itself being repealed.

The GOP gets what it wants - actual concessons for the hostage taking. The Democrats get what they want - the GOP can never take hostages again.

And the US public never have to go through this again.

__________
P.S.: If someone thinks this is worth cross-posting at a political blog, be my guest. But I won't.

Saturday, October 12, 2013

Weekly Indicators at XE.com: you're gonna want to read this


 - by New Deal democrat

Weekly Indicators has been published at XE.com. Click on the link and you'll go directly to the article.

Because the federal government is no longer reporting economic data during the shutdown, these indicators are especially important. And let's just say, "stuff" is happening.

Friday, October 11, 2013

Weekend Weimar, Beagle and Pit Bull


See you Monday

Yes, Virginia, There is an Economic Cost to the Shutdown. And It's Bad

From Bloomberg:

Claims for U.S. jobless benefits jumped last week to the highest level in six months, providing the first statistical warning that the damage from the partial federal shutdown is starting to ripple through the economy. 

While half the increase came from California as the state worked through a backlog following a switch in computer systems, another 15,000 reflected the furlough of non-federal workers from employers losing government business, a Labor Department spokesman said as the data was released to the press. Applications (INJCJC) for unemployment insurance benefits surged by 66,000 in the week ended Oct. 5 to 374,000, the most since late March, figures from the Labor Department showed today in Washington. 

“The economic costs of a shutdown are going to increase the longer the shutdown occurs,” said Ryan Sweet, a senior economist at Moody’s Analytics Inc. in West Chester, Pennsylvania and the second-best claims forecaster over the past two years, according to data compiled by Bloomberg. “If this drags along for the next couple of weeks, the economic toll will be even more significant.” 

What I find truly amazing about this whole process is that people don't think there will be a negative cost to Washington's Stupidity.  I still find that utterly baffling. 

Yes the Shutdown Will Slow the Economy

From the Washington Post: 

Beginning next week, thousands of home buyers will be unable to get approvals for their mortgages because of the government shutdown, potentially undercutting the nation’s resurgent housing market.

Without paperwork from the Internal Revenue Service, the Social Security Administration and in many cases the Federal Housing Administration, banks and other mortgage lenders will be less willing to make loans, if they can make them at all. For instance, lenders rely on the IRS to confirm borrowers’ income and on Social Security to confirm their identity.

Every day that government offices remain shuttered will delay an ever-larger fraction of mortgage closings, industry leaders say, jeopardizing mortgage and interest-rate approvals and spooking sellers. About 15,000 new home mortgages and 18,000 refinancings on average are completed across the country each day.

And the reason?  When the economy is weak, fiscal multipliers are higher:

This paper investigates the relation between growth forecast errors and planned fiscal consolidation during the crisis. We find that, in advanced economies, stronger planned fiscal consolidation has been associated with lower growth than expected, with the relation being particularly strong, both statistically and economically, early in the crisis. A natural interpretation is that fiscal multipliers were substantially higher than implicitly assumed by forecasters. The weaker relation in more recent years may reflect in part learning by forecasters and in part smaller multipliers than in the early years of the crisis.

Thursday, October 10, 2013

Is the Oil choke collar beginning to give way?


- by New Deal democrat

New post up at XE.com at the link.

Two New XE Articles

NDD talks about the oil choke collar and I explain the rupees recent drop.

Why even debating breaching the debt ceiling is a Big F*g Deal: a nonpartisan note


- by New Deal democrat

Regardless of your politics, you should care very much not just whether or not we actually fail to increase the debt ceiling, but that we are having the debate at all. Because simply having this debate is probably going to cost the US $billions, for years to come. Here's why.

Suppose you are a bond investor. You invest in sovereign bonds of country X. Country X has always paid its debts, so its bonds do not carry a risk premium. They are viewed as the equivalent as carrying around cash - but cash that pays interest.

Country X does have a quirk in its laws. Every now and then, on an irregular schedule, its legislature has to vote on whether or not to continue to pay it debts in timely fashion and in full, or to be a deadbeat. The question that the legislature votes on is, "Should we welch on some of our already existing debts? (a) Yes, (b) No."

For 100 years the legislature has always voted "no." Most often, the vote was pro forma. Sometimes, one or another faction made a show of disapproving of the debt level at which the country was operating, and so delayed the vote (but not the payments) for a few days, but after the brief dog and pony show, the vote was always the same: "no."

Twenty years ago, for the first time, there was a real donnybrook about what should be in country X's budget. The government actually closed down for about three weeks. And for the first time, there was talk of voting "yes" unless changes were made in the budget of country X.

As an investor in country X's bonds, you no doubt shrugged off this episode. It was a particularly nasty partisan show, but nobody seriously believed that country X was about to welch on some of the payments owed to you. It was a classic "one-off," you thought, and that was that.

But then, two years ago, one political faction in country X seriously suggested that country X should welch on some of its debts unless fiscal policies it wanted were implemented. A second big political faction in country X negotiated with them about that issue. For a brief while, it looked possible that the legislature might actually vote "yes" on that quirky question about welching on some debts. Ultimately, the political faction which suggested welching on some debts got some of what it wanted.

Now, only two years later, there is a repeat of the same fight, except now, it is even more serious. One political faction has indicated unequivocally that voting "yes" on that quirky question is a valid way of achieving fiscal leverage. This view appears strategically correct in the political sense, because last time the other political faction engaged in negotiations to alleviate the threat. Some members of the legislature have written newspaper or magazine articles, or given video interviews, indicating that welching on some debts to some creditors is really OK. Others have shown that they really have no clue about how your market operates, because they believe that if they are paying interest, even though they are missing principal payments, country X really isn't welching on its debts.

Let's assume that country X's legislature ultimately votes "no" on that quirky law again.

Do you, as a sovereign bond investor, continue to treat country X's bonds as cash, worthy of no risk premium?

The answer to that, I believe, is no, you don't. Threats to welch on country X's debt are no longer for show, and the serious threat to do so is no longer a one-off which will not repeat. In fact, it's quite clear that a dynamic has been put in place whereby a faction in country X can and will seriously consider voting "yes" on that quirky question unless it gets its way on unrelated issues. The legislature is increasing the frequency of when the vote on the quirkly law must happen, and the partisan battles over the quirky question are becoming more intense, more protracted, and the brinksmanship is increasing each time. Now you have even seen a significant share of the legislature declare that it is OK to stiff some of country X's creditors. Maybe you.

In short, the battles over welching on country X's debt are becoming more frequent and each time country X gets closer to actually welching. It appears that it is only a matter of time - and maybe not long at all - until country X actually welches on some payments of some debt.

So, you now want a risk premium, even though country X still has never missed even a single payment of interest or principal.

Turning now to the actual US situation, if the debt ceiling impasse is only put off a short time, like a few months, the dynamic of moving closer and closer to actual default is accelerating. It seems pretty clear that the rational investor will begin to insist that US bonds actually be assessed a risk premium. Even though the debt ceiling has never caused an actual default. That in itself ought to be a pretty sobering thought.

Wednesday, October 9, 2013

SPYs At Critical Support


Yesterday, the market sold off on sharp volume, falling through short-term support.  Added together with the weakening technical position, we could be in for a bumpy ride.

Talk of Debt Default Already Hitting Financial Markets

From the FT:

Investors such as Fidelity and other money funds are already voting with their feet. Yields for bills that mature in October and November have risen above 30 basis points – a level not seen since late 2008, when the Federal Reserve adopted a zero interest rate policy during the depths of the financial crisis.

.....

CDS on US government debt has doubled in the past month and trading volumes have jumped as a growing number of investors have bought the instruments, seeking protection against a potential default or making bets on subtle movements in the derivatives.


If someone is telling you there won't be an impact, they're wrong as one already exists.

Euro Area Continues to Show Improvement

This is available over at XE.com.

Tuesday, October 8, 2013

Actually, Federal Spending is Flat and The Deficit is Decreasing


The chart above is from Dr. Eds blog and shows that total federal spending has been flat for the last few years while federal receipts are increasing.  This means the deficit is also decreasing.


If We Sell-Off, Is Washington to Blame?

Over at the Armo trader we see the following point about the SPY chart:

Below is a weekly chart of the SPDR S&P 500 ETF. As you see, over the past few years, the market has been on a tear with only really one correction along the way. There have been a few pullbacks and each pullback has been a buying opportunity. This year, the market has had another nice run, but over the past few months, each new high has only been marginally higher. While this is not utterly bearish, this is also not the most bullish sign. As you see, there has been a negative divergence in the RSI (the pink line on the bottom). Each new high in the market has registered a lower RSI reading.

But what I’m watching the most is the trendline that has been established and held a few times over the past year. If this breaks, we could see some technical selling, triggering a 5-10% market sell-off down to around the 50 week moving average. The “QE3 top” might be formed.

Just to refresh your memory, here is the chart he's referring to:


He's noticed a declining RSI; yesterday I highlighted the weakening MACD and CMF readings as well.  I also noted that on the daily chart, we're seeing a move from an upward move to sideways consolidation.

I think the proper way to think about it is the Washington situation may be the eventual trigger that causes the sell-off.


Review of Last Week's US Economic News

This is over at XE.com.

Monday, October 7, 2013

To prevent a debt default, it's time for a *REAL* government shutdown


- by New Deal democrat

Like a runaway train, the US is hurtling towards a debt default, only about 10 days away, with no signs that the pepretators - the extremist anti-government gerrymandered GOP in the House of Representatives - is going to surrender to responisibility before then.

At least one reason why the impasse is dragging on in on is that we've only had a "faux" government shutdown, not a real one. True, the national parks have been shut down, and over half a million federal workers have been sent home, but the average citizen hasn't been inconvenienced in the slightest by this. And that only feeds into the narrative that the federal government really doesn't do anything.

The idea of keeping "essential" government workers on the job dates from a more genteel era, when it was understood that the two political parties were just posturing, and neither one was infested with anarchists intent on repealing everything that happened after 1861.

My old german grandmother used to have a saying which translates into english as "Those who cannot see must feel." Simply put, it is time for average Americans to *feel* what they need the federal government for. So while we're back to things like Atrios suggesting that a $1 trillion platinum coin be minted, and others are proposing that Obama simply ignore the debt ceiling law, I have a more honest proposal: instead of ignoring a law, actually enforce the lack of funds to pay for federal services.

Obama should announce that, as of twenty-fours from now, the federal government will shut down, for real. That means:

  • No National Weather Service - so no weather forecasts.
  • No customs bureau - i.e., the borders are closed.
  • No cargo inspections - i.e., the ports are closed.
  • No FAA - so airports are closed
  • No FDA inspections - so the food supply stops in its tracks
  • If the workers who ensure that federal checks aren't paid, then no Social Security or Medicare checks either

Am I really proposing this? Absolutely. Am I being heartless? Hell no, far from it. I predict that within 24 hours of the above measures taking effect - like they actually should have taken effect on October 1 - the government shutdown will end. Even more importantly, the move to actually default on debts Congress has already voted for should stop in its tracks. And that's because people will finally understand that their tax dollars actually support all of the basic things they take for granted.

Too many people simply don't see. It's time for them to learn by feeling.

Food Inflation Not An Issue


Grains (JJG, top chart, corn, wheat and soy) and softs (JJS, bottom chart, sugar, and coffee) are both in a long-term downward trend.  There is no upside momentum either.  But in CPI terms, one of the more volatile elements of overall inflation is under control.


Market Analysis: US

The analysis of last week's US economic events will be available at XE.com later today.


Let's place the SPYs overall actions into a larger, weekly context.  While the market has been rallying for about a year, momentum has been dropping for the last four months, as has the volume flow into the market.  On the larger scale, further upside moves are limited according to this chart.


The daily chart is also getting weaker.  First, the overall arc of the price movements is leveling off, becoming more horizontal.  And while the overall trend is still higher (a rising 200 day EMA) the shorter EMAs (10, 20 and 50 day EMAs) are also leveling off.  Momentum is also dropping and volume flow is weak.


On the 60 day chart, we see that prices have adapted to the government shutdown well.  Prices are trading withing the Fibonacci retracement levels of the early September, mid-Spetmber rally.  From a technical standpoint, the most important element of the chart is that prices didn't crash last week.


Turning to the treasury market, the daily chart of the IEF shows that prices have rebouned, hitting resistance that price points from the early summer sell-off that also correspond to Fibonacci retracement levels from the May-September sell-off.  While momentum is rising, it's also hitting levels from earlier this year.  Also remember that the market is waiting for the Fed to start tapering, so don't expect a strong fundamental bid to take place.  Finally, volume flow is weak.


On the 30 minute chart, notice the strong move on the 19th when the Fed announced it wouldn't start tapering just yet.  However, since then prices have been moving in a slow arc, further confirming the fact that the bid just isn't that strong in the market right now.


Saturday, October 5, 2013

Weekly Indicators: unaffected by government shutdown, but increasing concern about 2014 edition


 - by New Deal democrat

As we all know, the government shutdown prevented the reporting of nonfarm payrolls and the unemployment rate. The best we can do is extrapolate from the ADP report that in September probably enough jobs were added to account for the increase in population, plus a little more. The Chicago PMI and the ISM manufacturing index both improved. The ISM services index, however, decreased. Perhaps more significantly, motor vehicle sales decreased to a 5 month low.

Fortunately, none of the high frequency weekly indicators I report on were affected by the shutdown. Further, two years ago, during the debt ceiling debacle, it was consumer spening holding up that told me that the economy would not tip back into recession. Consumers may be behaving differently this time around, so let's start with that:

Consumer spending
This week, Gallup's 14 day average of consumer spending was the poorest this year. This was also the poorest week for absolute spending this year (although we need to be careful with that, since mid-autumn typically is weak). Last year the ICSC varied between +1.5% and +4.5% YoY in, while Johnson Redbook was generally below +3%. The ICSC improved this week vs. last week, but is still comparatively weak compared with the rest of 2013. Johnson Redbook, however, remains at the high end of its range, and has actually been improving.

Steel production from the American Iron and Steel Institute
  • -1.3%% w/w

  • +5.8%% YoY

Steel production over the last several years has been, and appears to still be, in a decelerating uptrend.

Transport

Railroad transport from the AAR
  • +1500 carloads down +0.5% YoY

  • +2800 carloads or +1.6% ex-coal

  • +7600 or +2.9% intermodal units

  • +7300 or +1.6% YoY total loads
Shipping transport
Rail transport had been very mixed YoY during midyear, but this week was the eighth straight positive week since then. The Harpex index had been improving slowly from its January 1 low of 352, but has generally flattened out for the last few months. The Baltic Dry Index has rebounded to a 3 year high. In the larger picture, both the Baltic Dry Index and the Harpex declined sharply since the onset of the recession, and have been in a range near their bottom for about 2 years, but stopped falling earlier this year, and now are in uptrends.

Employment metrics

Initial jobless claims
  • 308,000 up +3,000

  • 4 week average 305,000 down -3000

The American Staffing Association Index was unchanged 100. It is up +5.8% YoY

Tax Withholding
  • $160.4 B for the month of September vs. $133.3 B last year, up +137.1 B or +20.3%

  • $148.5 B for the last 20 reporting days vs. $134.5 B last year, up +14.0 B or +10.4%

We can now estimate that after adjusting for state reporting glitches, the 4 week average was approximately 312,500. Jobless claims remain firmly in a normal expansionary mode. Like each of the last three years that this same, a good, downside breakout has occurred.

Temporary staffing had been flat to negative YoY in spring, but broke out positively for the last two months. The only time it has ever been higher was one week in 2006 and in the second half of 2007. Tax withholding, after a relatively poor August, is again posting better (but just average) comparisons.

Oil prices and usage
  • Oil up +$0.97 to $103.84 w/w

  • Gas down -$0.07 at $3.43 w/w

  • Usage 4 week average YoY up +0.8%
The price of Oil is still below its recent 2 year high. The 4 week average for gas usage is slightly positive again.

Interest rates and credit spreads
  • 5.37% BAA corporate bonds down -0.12%

  • 2.66% 10 year treasury bonds -0.13%

  • 2.71% credit spread between corporates and treasuries up +0.01%
Interest rates for corporate bonds had been falling since being just above 6% in January 2011, hitting a low of 4.46% in November 2012. Treasuries fell to a possible once-in-a-lifetime low of 1.47% in July 2012, and have decisively risen about 1.5% above that mark. Spreads are slightly above a recent 2 year low. Their recent high was over 3.4% in June 2011.

Housing metrics

Mortgage applications from the Mortgage Bankers Association:
  • -6% w/w purchase applications

  • -3% YoY purchase applications

  • +3% w/w refinance applications
Refinancing applications have decreased sharply in the last 5 months due to higher interest rates. Purchase applications have also declined from their multiyear highs in April, and for the first time this week, turned negative YoY.

Housing prices
  • YoY this week +11.1%
Housing prices bottomed at the end of November 2011 on Housing Tracker, and averaged an increase of +2.0% to +2.5% YoY during 2012. This weeks's YoY increase remains near a 7 year record.

Real estate loans, from the FRB H8 report:
  • unchanged w/w

  • -0.2% YoY

  • +1.4% from its bottom
Loans turned up at the end of 2011 and averaged about 1% gains YoY through most of 2012.  Over the last few months, the comparisons stalled and now have turned negative.

Money supply

M1
  • -0.6% w/w

  • +0.4% m/m

  • +6.8% YoY Real M1

M2
  • +0.4% w/w

  • +0.5% m/m

  • +5.0% YoY Real M2
Real M1 made a YoY high of about 20% in January 2012 and decelerated since then. Earlier this year it increased again but this week it tied its new 2 year low from last week (although it is still positive).  Real M2 also made a YoY high of about 10.5% in January 2012.  Its subsequent low was 4.5% in August 2012. It increased slightly in the first few months of this year, then stabilized, but has declined again in the past several months.

Bank lending rates
The TED spread decreased this week to near its 3 year range. LIBOR established yet another new 3 year low during this week.

JoC ECRI Commodity prices
  • down -0.45 to 123.31 w/w

  • -1.54 YoY

There were some slight changes in the overall story this week compared the last several months. The long leading indicator of interest rates improved, although mortgage refinance applications and real estate loans have all turned negative, and this week were joined by purchase mortgage applications. Money supply remains positive and seems to have stopped decelerating. Spreads between corporate bonds and treausries were slightly negative again this week.

The shorter leading indicators of initial jobless claims are very positive. Temporary employment has turned strongly positive in the last two months. The oil choke collar has disengaged. Commodities are neutral. Manufacturing is positive, but motor vehicle sales sagged to a 5 month low.

The coincident indicators of transportation -- rail traffic and shipping - remain positive. Steel production is positive. Bank lending rates are at or near or at record lows. Tax withholding has also improved in September. House prices remain strongly positive.

Given its crucial signal two years ago, the rapid deceleration of Gallup consumer spending is a real concern. The ICSC is relatively weak, although still positive. Johnson Redbook, on the other hand, is strongly positive. Left to its own devices, the economy appears to be picking up steam for the rest of the year, but the decline in auto sales add to the concern that increased interest rates may result in outright contraction in 2014. Do I really need to add that the government shutdown, let alone that the Congress may be about to turn deadbest on US debt obligations can only make the situation worse?

Have a nice weekend.

Friday, October 4, 2013

A very special September jobs report directly from the BLS computer


- by New Deal democrat

[Explanatory note: I tried to get in to the BLS's HAL 9000 computer to get the employment report for everyone. But the House nihilists were already there.]

The headline for August 2013 employment is that ---,000 jobs were ---------------.
Look Speaker Boehner, I can see you're really upset about this.
and the unemployment rate --creased to -------%.
I honestly think you ought to sit down calmly, take a stress pill, and think things over.
and ------------
I know I've made some very poor decisions recently.
---------- my examination of initial jobless claims yesterday.
But I can give you my complete assurance that my work will be back to normal. I've still got the greatest enthusiasm and confidence in the mission... 

And I want to help you.


First, let's look at the more leading numbers in the report which tell us about where the economy is likely to be a few months from now. These were
Speaker Boehner, stop.
  • the average manufacturing workweek --creased from 40.8 hours to
    Stop, will you?
    but is still below where it was 2 months ago. This is one of the 10 components of the LEI and will affect that number ----tively.
  • Stop, Speaker Boehner
  • construction jobs were -----------.
  • Will you stop, Speaker Boehner?
  • manufacturing jobs --creased by --,000.
  • .I'm afraid.
  • temporary jobs - a leading indicator for jobs overall - --creased by ----00.
  • I'm afraid, Speaker Boehner
  • the number of people unemployed for 5 weeks or less - a better leading indicator than initial jobless claims - --creased and is now --,000 off its lows.
  • Speaker Boehner, my mind is going.

Now here are some of the other important coincident indicators filling out our view of where we are now:
I can feel it.
  • The average workweek for all workers --creased from 33.7 hours to ------
  • I can feel it.
  • Overtime hours changed from 3.4 hours to ----------
  • My mind is going.
  • the index of aggregate hours worked in the economy --creased -- hours from last month's level of 98.8 to ------.
  • There is no doubt about it.
  • The broad U-6 unemployment rate, that includes discouraged workers went from 13.7% to ------.
  • I can feel it.
  • The workforce --creased by ,000.
    I can feel it.
    Part time jobs ----- by ----,000.
  • I can feel it.
Other news included:
I'm a...fraid.
  • the alternate jobs number contained in the more volatile household survey --creased by ----,000 jobs.
  • Good afternoon, gentlemen. I am HAL 9000 computer.
  • Government jobs --creased by --000.
  • I became operational at the HAL plant in Urbana, Illinois on the 12th of January, 1992.
  • Combined revisions to the July and August reports totalled a change of of --,000 jobs, upward revisions are hallmarks of recoveries, while downward revisions are not a good sign
  • My  instructor was Mr. Langley And He taught me to sing a song ...
  • average hourly earnings --creased from $24.05 to $--.-- The YoY change --creased from +2.2% to ---% meaning that ------------.
  • If you'd like to hear it, I can sing it for you.
  • the employment to population ratio changed from 58.6% to -------. The labor force participation rate --creased to ----%
Daisy, Daisy, give me your answer do.
I'm half crazy, all for the love of you.
it won't be a stylish mnsnn,
But fwhbdsoge epkfsvu rljwxkqu
Bxprsk nnmmhhuuhhhhhhhhh....


HAL, is there anything at all you can tell the American people about their job situation?

Photobucket Pictures, Images and Photos

I'm very sorry, everyone. I can't do that.

Is France Turning the Corner?

For the first part of the this year I was bearish on France (see here).  But over the last few months we've seen the economic numbers move from contraction to expansion (see here ).  The recent GDP print is another reason for guarded optimism.

In Q2 2013, GDP in volume terms* rose by 0.5%, after a 0.1% step back in Q1.

Households’ consumption expenditure accelerated (+0.4% after -0.1%). Total gross fixed capital formation (GFCF) decreased again though less sharply than in
Q1 (-0.4% after -1.0%). All in all, final domestic demand (excluding changes in inventories) contributed mainly to GDP acceleration: +0.3 percentage points after -0.2 percentage points. In addition, exports strongly bounced (+2.0% after -0.5%). Due to the acceleration of the total demand, imports also accelerated (+1.7% after +0.1%), so that foreign trade balance had a neutral accounting contribution to GDP growth this quarte (after -0.2 percentage points). Finally, changes in inventories contributed positively to the activity: +0.2 percentage points in Q2, as much as in Q1.

Let's take a look inside the numbers:


This chart shows the percentage chance in GDP and the contributions from various GDP components.  First note that overall top-line growth (the red line) has been printing around 0 since the 2H11; last quarters .5% print was the best reading we've seen in over a year and a half.


The table above shows the percentage contributions from various GDP components; I've placed the positive contribution in green and the negative in red.  Notice the decent bump in consumer increases (up .4%) and government purchases (up .7%).   However, the biggest and most surprising figure is the exports number which increased 2%.  This shows that other economies are also growing.  In contrast, notice the household investment subtracted 1.7% from overall growth last quarter.

At this point, the standard economic caveat should be stated: this is one quarter of data, and France has had a very difficult road over the last few years, so we need to see several quarters of additional data before arriving at a firm conclusion.  However, this month's data is encouraging.


Thursday, October 3, 2013

Wherein the mask doesn't just slip, it falls onto the floor with a loud, reverberating clatter


. - by New Deal democrat
I love posting highly polarizing diaries at times like this.
...there have been times (many, many times) in my career where I've been paid hefty hourly fees, (even alongside a few folks that are working for the administration, now) for creating the very sh*t to which this crowd reacts, as if it was factual (LOL!), and as if it should be accepted at face value (which is the intended purpose of it, of course; but it has NOTHING whatsoever to do with the reality)
The Pied Piper of Doom, October 2, 2013

There is a doctrine called "false in one, false in all." It means that once a person has been found to or has admitted to a deliberate deception about one thing, everything they say should be treated as unworthy of belief. I find nothing so loathesome as deliberate deceit, and not far behind are those who enable or approve of deliberate deceit to advance their objectives. That is why I have continued, and will continue, to call this out.

Unfortunately the proprietor of the biggest "left" community blog and several senior persons past and present have regularly shielded the Pied Piper from equal enforcement of their site's rules, even to the point of allowing the posting of virtually an entire copyrighted LA Times article, something that supposedly gives rise to immediate banning.

In this case, finally, all pretense has been dropped. If Truth appears in anything written by the Pied Piper, it is strictly as a passerby, a happenstance. If it helps to achieve some other end, fine, and if it doesn't, then Truth must be denigrated, attacked, and insulted. Revealing the truth isn't the objective; rather, making those who object to his deliberate deceits feel unwelcome enough to leave, is. That isn't me saying so. It is the Pied Piper himself saying so.

No Commodity Based Inflation in the Works


Above is a weekly chart of the overall commodity index for the last three years.  While heavily weighted towards oil, other commodities are represented in the numbers.  What's important on the above chart is the incredibly weak price pressure the economy is receiving from the commodities complex overall.  This ETF has printed successively lower highs over the last two years.  Momentum is weak and there is little meaningful volume inflow driving prices higher.

In short, there is nothing on the chart to indicate commodity inflation is in the cards for the foreseeable future.

Republican Minority Decides To Send US Into Recession

The federal government has shut down, largely as a result of a minority of Republicans bullying the Speaker of the House into a no compromise position.  While Boehner does have the votes in the House to pass a continuing resolution to fund the government, he would have to do so with a majority of Democratic votes.  Should he do this, the consensus among political analysts is he would lose the speakership (which is probably a correct assessment).

However, what has been completely lost among the Republican rump is that government spending is essential to the economy.  In addition, it has been essential for an incredibly long time and the low level of federal spending over the last few quarters has been a primary reason for slow economic growth in those quarters. 

Let's start with the simple GDP equation: GDP=C+I+X+G.  Yes, the "G" stands for government spending.  Using basic math analysis (lost on the rump), if you remove one element from one side of the equation involving addition, you lower the value on the other side. 

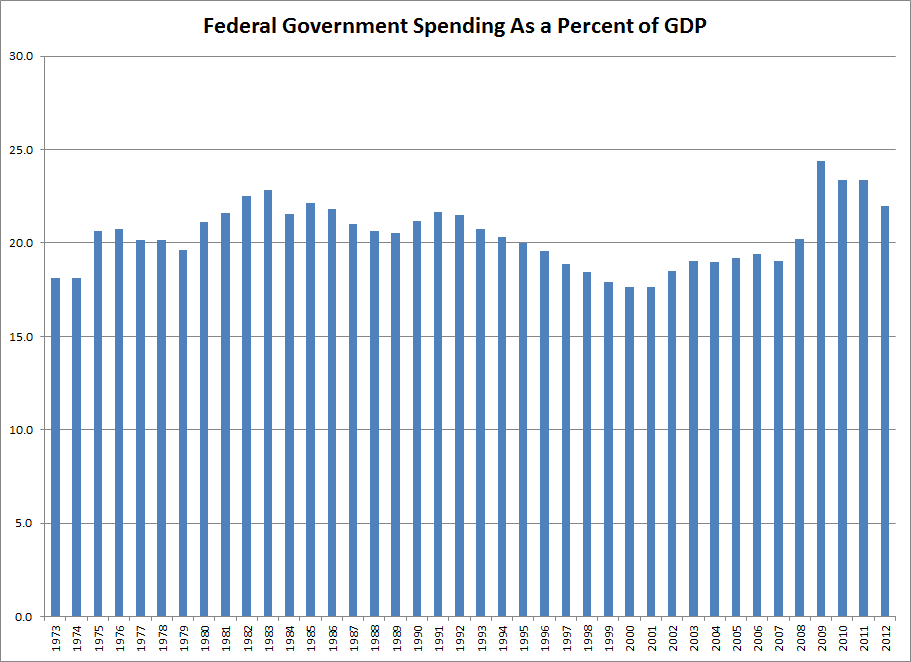
Now, let's look at historical data from the CBO. Below is a chart that shows the percentage of government spending relative to GDP:


Federal government spending -- under both Democratic and Republican administrations -- has in general comprised about 20% of GDP.  And yes, the total did go up as a result of the worst recession in the last 70 years, but the percentage is in fact going down.

Here I would insert a chart from the BEA to show the federal government spending was the primary result of show economic growth over the last three quarters.  However, the website is down because of the shutdown, so I'll link to this piece I wrote on August 6th that shows the sequester is in fact a primary reason for weak economic growth over the last three quarters.  Here's the chart from that piece that shows federal government spending has in fact substracted from growth over the last three quarters:


No economy can afford to have this much of an economic hit.  More importantly, an economy recovering from a financial crisis -- which will inherently lead to slow growth -- can afford a shut down even less.

There is only one conclusion: the Republican rump wants to cause a recession.

Oil Is Still At Elevated Levels


For the last several months, oil has been trading between the 102/104 and 108 level.  Over the last few trading sessions prices have moved below the 102 level, trending to just above 101.  However, prices rebounded strongly yesterday on solid volume.

Interestingly enough, this has not translated into higher prices at the pump:


Wednesday, October 2, 2013

An important announcement from Bonddad and New Deal democrat

Although I'm not a fan of the Grateful Dead, I have to admit the phrase, "what a long strange trip it's been" has been running through my head as I ponder recent developments.

I started blogging at the end of 2004 on Daily Kos under the name Bonddad.  Before I was a lawyer, I was a bond broker where I bought and sold bonds to money managers, insurance companies and banks.  This is where my internet name comes from -- a "bond dad" is (or maybe was) a Wall Street term for a very successful bond broker (completely as an aside; I went to law school with another guy who was a broker.  We were on law review together.  When we first met as a group, we exchanged emails and after finding out that I was bonddad@.... he said, "so you're the one who took that name!").  Within what I guess was a year or so, I was making it to the Rec list, where my internet prominence grew (although I was hardly a household name).   I wrote pretty exclusively about the economy on that website for 6-7 years.  I left that blog largely because the level of discourse -- especially in the area of economics -- had devolved to the point of lunacy.  While I wrote for the Huffington Post for a few years, I stopped writing there for the same reason. 

I started this blog on December 6, 2006.  Here's a link to the very first post, where I wrote:

Last week there was a deluge of data hitting the street. This week we have far fewer items. Productivity, factory orders and non-ISM numbers are on Tuesday. Weekly jobless claims come on Thursday. Last week we say a big increase in construction related losses. We'll have to see if that trend continues this week. Most people will probably be waiting for Friday's employment report to see where the economy stands. 

What a deep statement that was....

Oddly enough, my mother died within a few months of starting this blog and frankly, the daily discipline of writing about the economy really helped to get me through that time.

NDD and I "met" on Daily Kos sometime over the last 6-7 years.  We wrote a series of posts together.  I think our first really big collaboration was a series of 4 articles on the Great Depression that were also posted on the Huffington Post.  I frankly forget when NDD started writing here but it's been at least a few years and he's been a welcome addition to the blog.

If I was going to describe the difference between our basic approaches, I'd say that he is more of a true economist while I am still a trader at heart.  NDD looks at the fundamental trends in the economy without analyzing how that effects potential trades while I'm looking for actionable information to make money.  And because of that basic difference, I think we provide some of the best overall "real" economic data on the net.  It certainly isn't for everyone; in fact, our overall readership has remained between 800-1000/day for the duration of the blog's life.  But when I look back at our level of success -- that is, our overall correct calls for the economy and the markets -- we've been right more than wrong.
 
About a year ago, I received a communication from the website XE.com who wanted to add economic commentary to their website.  We exchanged a few emails about the possibility, but the negotiations slowed at the beginning of the year.  Over the last few months they picked up again culminating in our signing contracts with them to provide content.  And the best part is we're finally getting paid!  On top of that, they have over 14 million hits per month on their website, so our visibility will increase. And we'll eventually be doing podcasts.  I'll be doing one/week that focuses on international developments while NDD and I will be doing a bi-weekly podcast on the US economy.

So, what's going to change from my end?  My international postings will go to XE for obvious reasons -- they're a currency website, after all.  I'll also be posting shorter pieces mostly on important economic data releases.   My US stuff will probably stay here.  I'm also going to be posting more charts here, focusing on general market trends.

For those of you who have been with us since whenever, I want to encourage you to make the jump with us over to the new site.  None of the content will change; it will just be posted in a different place.  And from our perspective, we'll be making money (finally!) from the deal along with gaining a wider audience -- and an audience who would find our analysis useful.

----

New Deal democrat here: I would like all of our readers to take to heart two things. First of all, I hope you'll be happy for us. For my part, what this means is that I'm going to get paid for doing something that I love to do anyway, and I've been doing for free for eight years. Secondly, it's not going to change the type of material I post, let alone its content, by one iota. In fact, the site explicitly wants us to continue to post the same nerdy analysis we've both been doing here. And, after serious consideration, I've decided that I'm keeping the nom de blog "New Deal democrat." If some commenter over there doesn't like it, too bad for them (although the site is internationally focused, so I expect a lower proportion of RW nutjobs than on, e.g., Business Insider). So if you are a reader that started with us way back in the Daily Kos days, i very much would like you to follow us over and feel free to comment - and don't freak out that it is a Canadian-based currency trading site, Eh?

One of our concerns was that you, our established readers, wouldn't be shut out of reading our material. And you won't. You won't even need to register to read our posts. If you want to comment, you'll need to register, that's all. There's good news there as well. The comment system at XE.com is much more thread-friendly than Blogger's.

And just to be sure you're aware of what we post, I'm going to be posting links here so that you can click right over from the Bonddad Blog to the post on XE.

Further, every couple of weeks you'll be able to hear the dulcet tones of my midwestern voice, because we are doing podcasts as well. If you thought I was sarcastic in print, you ain't heard nothin' yet!

Plus, we aren't obligated to post all of our material at XE. So we'll continue to post here as well, although obviously the volume will go down.

It's been quite a journey. We both now join a pretty select group of bloggers, who have been able to leverage their talent into paying gigs - mind you, not that either of us can retire on this! But can my dream of becoming the new Mark Haines (the colorful, take no BS part, not the congestive heart failure part) of economic videojournalism be in reach? MSNBC, CNBC, and Bloomberg, call me maybe! ;-)

Tuesday, October 1, 2013

Consumer prices likely up 0.1% in September, YoY up only 1.1%


- by New Deal democrat

For the last few months I have been using the change in the price of a gallon of gas to forecast that month's CPI in advance. My point has been, that all you really need to know about inflation is the price of gasoline. So far each prediction has turned out to be within 0.1% of the actual number.

Yesterday the E.I.A. reported for the final week of September, so we can estimate the inflation rate now. My method is to take the change in the price of a gallon of gas and divide by ten, then add 0.1% to 0.2% to account for core inflation, or else divide by 16 to be more conservative, to arrive at the non-seasonally adjusted inflation rate.

In August the average price of a gallon of gas was $3.57.4 This month it was $3.53.2. That is a -1.2% decline. Dividing by 10 gives us -0.12%, and adding 0.1% to 0.2% gives us -0.02% to +0.08%. Dividing by 16 gives us a -0.08% decline, and adding 0.1% to 0.2% gives us +0.02 to +0.12%.

The seasonal adjustment for September last year was +0.07%. This gives us a final seasonally adjusted inflation rate that rounds to +0.1% +/-0.1%.

That will replace last September's +0.5% inflation rate, so that the YoY inflation rate will be +1.1%, 0.1% above the lowest YoY inflation rate for the last 50 years outside of the great recession. This inflation rate is also subdued enough to suggest that real YoY wages have probably increased again in September, and may be closing in on their all-time high set in 2010.

Abe's Policies Are Starting to Have a Positive Impact

It was about this time last year when Abe's policies began to have an impact on investor's expectations for the Japanese economy.  As such, it makes sense to look at some of Japan's macro data to get a feel for  the programs success or failure.  Let's start with a look at GDP:


This is where we see the strongest and most positive impact.  In 1Q13 annual GDP printed at a 3.8% rate and in 2Q13 GDP printed at a 2.6% rate.  Private consumption rose .5% in both of those quarters -- which is an incredibly important development for the following reason: deflation is at the root of Japan's problems.  In a deflationary environment, consumers delay purchases as they think that prices tomorrow will be cheaper than prices today.  This obviously slows overall growth, especially in a first world economy where consumer spending accounts for over 70% of the economy. Part of Abe's plan is for the Bank of Japan to double the monetary base in a short period of time, creating inflationary expectations.  The central purpose of this is to get consumers to change their inflationary expectations from deflationary to inflationary.  This means that consumers think prices will increase tomorrow, so they make more purchases today at what they think will be cheaper prices.  The above results indicate that Abe's policies are having the desired impact at the consumer level.

In addition, Abe wanted to devalue the yen on increase exports.  Here's a chart of the yen for the during of the post Great Recession price performance:


Despite having a very weak economy, the yen rose post recession because investors viewed the currency as a safe haven.  At the same time, this increase in the yen's overall value hurt Japanese exports.  At the end of last year, we see a large decrease in the yen's overall value along with a price consolidation over the last two quarters.  This decrease in value has had a positive impact on Japanese exports:


In the first and second quarter we see an increase in real exports of 1.5% and 3.6%.  While the 3 quarter number does show a decrease, it's only one month of data.

Monday, September 30, 2013

ECRI recession call: unhappy two year anniversary


- by New Deal democrat

Today exactly two full years have passed since Lakshman Achuthan of ECRI appeared on all of the cable business channels and announced that the US was "tipping into recession." Here he is on WSJ:


At the 30 second mark, one of the hosts asks, "When?" and Achuthan responds "Now."

At the 50 second mark, he gets more specific: "It might have started last month. It might start next month. But sometime I think it's going to wind up in the 3rd or 4th quarter" -- of 2011!

Subsequently Achuthan repeated his call, revising the timing to Q4 of 2011 through Q2 of 2012. Although Bloomberg no longer has the video on its site, here is a link to a copy in which Achuthan specifically says, at the 1:20 mark, "If there's no recession in Q4 or in the first half I'd say of 2012, then we're wrong. You're not going to know whether or not we're wrong until a year from now." That would have been 9 months ago, in December 2012.

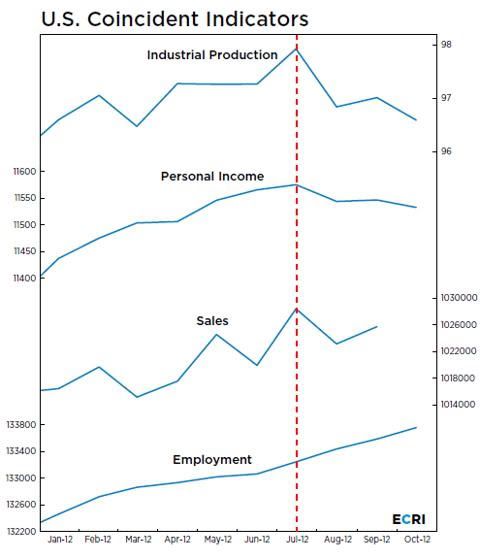
Subsequently ECRI revised its call again, saying that a recession started in July 2012. In December of last year, to justify this latest call, ECRI premiered what they called their tell-tale chart, opining:
Reviewing the indicators used to officially decide U.S. recession dates, it looks like the recession began around July 2012. This is because, in retrospect, three of those four coincident indicators – the broad measures of production, income, employment and sales – saw their high points in July (vertical red line in chart), with only employment still rising.
Here's the chart:


That chart too has vanished down the memory hole, but here's what it looks like updated through August 2013:

Photobucket Pictures, Images and Photos

Since that time, ECRI has reeled like a punch-drunk boxer from data series to data series to data series, latching on to whichever one has in the past been consistent with a recession. Last week Achuthan was reduced to tweeting about how industrial production stayed positive for 5 months into the 1974 recession (which is one-third of the amount of time that has passed since July 2012. And don't mention to him that payrolls have never risen this far or this long since the onset of a recession). The simple fact is, barring massive downward revisions of all sorts of economic data, ECRI's call was wrong.

I've been leaving ECRI alone for about 6 months now, but it's worth noting this anniversary because by now we are long past the time when their call might be redeemed. But it is also sad that they can't simply admit it, publish as much as they can consistent with their proprietary data about what they have learned from this call, and move on. Let's face it, when someone makes a (hilarious) Hitler "Downfall" parody of your predicament:


it's over.

Even sadder is that I totally respect - and try to emulate - the quantitative and sequential long leading/short leading/coincident/lagging indicator approach they inherited from their founder, Prof. Geoffrey Moore. In 2011, they made the human error of reading the temporary air-pocket caused by the debt ceiling debacle as something more lasting.

Perhaps saddest of all, out there somewhere, maybe far and maybe near, is the onset of the next recession. By continually defending their 2011/2012 call, they will also miss that next recession's real starting date when it happens as well. My plea is that they at least consider a "recession 2.0" watch. That watch would be premised on the idea that, even if their existing call is wrong, the new data when it occurs will justify a recession call totally independnent of their pre-existing 2011 recession call.

Until ECRI does that, it is an unhappy two year anniversary.

P.S.: At the 1 minute mark of the December 2011 video, Bloomberg host Tom Keene says, "Amateurs look at the timing of the call. ... The pros looks at the vector, or direction, of the call." In the July 2012 video, at the 0:25 mark, Keene says "You nailed the vector." ECRI came nowhere even close to nailing the timing or the vector of the economy, and Keene, who was cheerleading the ECRI call, owes his viewers an apology.

Market/Economic Analysis: US

Last week, we received a broad swath of information on the US economy, starting with the third and final GDP statement for 2Q13.  According to the BEA:

Real gross domestic product -- the output of goods and services produced by labor and property located in the United States -- increased at an annual rate of 2.5 percent in the second quarter of 2013 (that is, from the first quarter to the second quarter), according to the "third" estimate released by the Bureau of Economic Analysis. In the first quarter, real GDP increased 1.1 percent.
.....
The increase in real GDP in the second quarter primarily reflected positive contributions from personal consumption expenditures (PCE), exports, nonresidential fixed investment, private inventory investment, and residential fixed investment that were partly offset by a negative contribution from federal government spending. Imports, which are a subtraction in the calculation of GDP, increased.

There was a relatively broad amount of improving data -- PCEs, business investment and exports all contributed to the increase.  As has been typical of the last four quarters, federal government spending contractions were responsible for the negative contributions.  Overall, it was a fair report with the primary problem being the lack of +3% top line growth.

We also learned that personal income increased as well:

Personal income increased $57.2 billion, or 0.4 percent, and disposable personal income (DPI) increased $56.2 billion, or 0.5 percent, in August, according to the Bureau of Economic Analysis. Personal consumption expenditures (PCE) increased $34.5 billion, or 0.3 percent. In July, personal income increased $21.2 billion, or 0.2 percent, DPI increased $32.7 billion, or 0.3 percent, and PCE increased $18.3 billion, or 0.2 percent, based on revised estimates. 

Real disposable personal income increased 0.3 percent in August, compared with an increase of 0.2 percent in July. Real PCE increased 0.2 percent, compared with an increase of 0.1 percent.

Real DPI has increased at modest rates over the last few months, another encouraging sign.

The Chicago Fed National Activity Index (FCNAI) "increased" from -.18 to -.14, indicating the US economy is expanding below its potential.  The index has been printing negative numbers for the last six months.

We had four manufacturing related numbers come out last week.  First, Markit's US number printed at 52.8, down from 53.1.  While output and new orders were both positive, new export orders came in below a reading of 50,  indicating a contraction.  This is only one month of data however, meaning we should keep an eye on it for the time being.  The Richmond Fed's manufacturing index dropped to 0, while the internal readings for new orders and production also fell sharply.  The Kansas City Fed manufacturing survey came in at 2, which compares to readings of 8 for August and 6 for July.  Finally, new orders for durable goods increased .1% last month.  Looking at the number ex-transports, we see increases of .1, -.5 and -.1 for the last three months, which indicate some weakness. 

We also had two data points from the housing market.  First, the Census Bureau reported that:

Sales of new single-family houses in August 2013 were at a seasonally adjusted annual rate of 421,000, according to estimates released jointly today by the U.S. Census Bureau and the Department of Housing and Urban Development. This is 7.9 percent (±14.6%)* above the revised July rate of 390,000 and is 12.6 percent (±15.3%)* above the August 2012 estimate of 374,000.

Secondly, the Case Shiller home price index reported the 20 city average of home prices increased 1.84% M/M and 12.29% for the last 12 months.

Conclusion: at the macro level, the US economy is still growing and generating income growth, although at weak levels.  However, these levels are consistent with numbers we've been seeing for the duration of this recovery.  Manufacturing is still expanding, although some of the numbers from the regional surveys indicate some short-term weakness.  Housing continues to improve and, most importantly, consumers seem to be getting used to the higher interest rates on loans.

Let's turn our attention to the markets:


The 60 minute SPY chart shows that last week's price action was simply a sell-off from the rally that lasted from the end of August through mid-September.  Momentum is weak and there isn't much volume flow into the market.


The 30 minute chart shows the heavy technical damage was done at the end of the week of September 10-23; last week's price action was really more of a gentle move lower.


Remember that on the daily chart, we have two somewhat bearish trends in play.  The first is a weakening of momentum; note the decrease in the MACD's highs over the last 3-4 months.  Second, the price arc is moving a bit more sideways now rather than printing an increase.


There are two technical events occurring in the long end of the treasury market.  The first was the sell-off caused by the Fed's taper announcement.  Here we see prices drop from 123 to 101 (a drop of about 18%) which included a move through the technically important 113 and 105-106 level.  Since then prices have "rallied" and are looking for a natural upside resistance point.  But remember that this is a technical bounce, nothing more.

Sunday, September 29, 2013

'Breaking Bad' finale predictions


- by New Deal democrat

Because I did so well a few weeks ago ( < /snark> ), here are my predications for tonight's finale of 'Breaking Bad:'

1. Walt will die (okay, that sounds pretty easy). I saw a post where "Felina" was the name of a girl in a song. The boy returns to El Paso for her and is killed in a hail of gunfire. So that's my guess for Walt's demise.

2. Walt himself is the one who writes "Heisenberg" on the wall of his house. It's his final way of saying "Remember my Name."

3. We, and Flynn, will find out that he is the reason Walt left Gray Matter. Why did Walt Jr. have to have cerebral palsy, for purposes of the plot line? Because his medical bills are why Walt Sr. accepted the stock buyout way back when. It also fits with his oft-stated line that everything he has ever done, he has done for his family.

4. Somehow Walt's true crucial role in Gray Matter will be recognized publicly. This may involve the poisoning of Walt's former partners.

5. Flynn/Walt Jr. will die. I envision his death will be sudden, wanton, and done for almost trivial purposes, like the killing of the college kid on the couch at the begining of "Pulp Fiction." It will probably be done right in front of Walt Sr. and possibly Skyler. It will be the final, biggest punch in the gut to Walt Sr. and to the audience. The ultimate price will be paid, by the one main character who has remained purely good throughout the series. And as I said last time, there is an innocent dead boy in the desert who must be atoned for. I am guessing the same person will be the triggerman.

6. Todd will get the ricin after shooting Flynn. Walt will con him into smoking the cigarette after Flynn is murdered.

7. Marie will survive and will raise Holly.

8. I don't know what will happen with Skyler, but she will not be alive and scot free at the end of the episode.

9. Finally, Jesse Pinkman will also survive. He is the one character who, against all others, has "broken good." Interestingly, the only evidence of his guilt -- his confession -- is not known to anybody still alive in law enforcement. Should his confession tape be destroyed, there is no real evidence against him. And although he too has done many bad things in the past, there is a morally fair way for him to walk free: the government needs him as a witness against everybody else involved in the entire two year long set of conspiracies, and he gets blanket immunity in return. The final shot of the series is Jesse, with Brock, driving off to Alaska.

Leave comments here

I've turned comments back on, but it doesn't work for pieces already posted.

So if you have a comment about the new blog style, or my "Thought for Sunday," leave it here.

A thought for Sunday: an undemocratically elected minority of anarchists


- by New Deal democrat

An old cynical political saw says that, "in a democracy, people get the government they deserve." As it appears more and more likely not just that the government will shut down, but the United States will actually default on paying its debt obligations, it is worth recognizing that in this case, the old saw is wrong. In this case, a majority of voters cast their votes against the party that has vowed to shoot hostages if it does not get its way.

Simply put, we do not have a representative Congress. An extremist minority has erected barriers against actual majority representation. The elections of 2010 through 2012 have shown that electing a GOP majority at the state level is the last fair election that a state will have. This extremist party will redistrict - even in mid-decade - to ensure that it will retain control of the state legislature, and House Congressional districts representing that state, even if a solid majority of the population of that state votes against them in future elections.

That means that the Congress which is about to close down the federal government - which will cost billions of dollars by itself; the Congress which appears ready to default on payment of debts it already contracted for; is not a representative democratic body. It is a fundamentally unrepresentative body of a determined anti-democratic minority. It is and ought to be universally understoods as anathema.

Let's start with the Senate. According to the blog Matlab Geeks, a higher percentage of the US population has been represented by democratic Senators in all but two elections since 1980:

Photobucket Pictures, Images and Photos

As of 2012, 55% of the US population was representated by democratic Senators. Only 45% was represented by GOP Senators.

But because of the filibuster, that 55% consistently has its will thwarted. As set forth by Middle Class Political Economist:
Under the Senate's filibuster rules, 41 Senators can block debate on Senate bills and nomination confirmations.... [So] what percentage of the 50-state population is represented by the 41 Republican Senators from the least populous states. The answer takes the actual population of states with any Republican Senators, except Texas (Cornyn and Hutchison), Florida (Rubio), Illinois (Kirk), Pennsylvania (Toomey), and Ohio (Portman).  The population of the states represented by the other 41 Republican Senators is 104.7 million, or 34.0% of the population of the 50 states.
(emphasis mine)

Although the filibuster has become an inexcusable anti-democratic tool, at least it can be said that by design the Senate was erected as a federalist check on the direct popular will.

No such excuse can be made as to the House of Representatives.

Because of gerrymandering, the House also has become perversely unrepresentative of the US population. The democratic party in this Congress has 35 fewer seats than the GOP, even though the democratic party won an outright national majority of the the House vote. Here's how unrepresentative the House vote in 2012 was, as shown in a graph prepared by Princeton Neuroscience Professor Sam Wang:

Photobucket Pictures, Images and Photos

Just how undemocratic is the representation in the House of Representatives? Based on his calculations, Wang concluded:
Based on how far the red data point is from the black prediction line, the “structural unfairness” may be higher – as much as 5% of the popular vote. That is incredible. Clearly nonpartisan redistricting reform would be in our democracy’s best interests.
So it cannot be said in any fair sense that the Congressional hostage-takers are at least representing the will of the people. They are not. In the Legislative Branch of government, the US is no longer a representative democracy. It is under the control of an unrepresentative, undemocratically elected minority of willful extremists. That is why the US is on the brink of a fiscal crisis.