Thursday, July 7, 2011

Don't Expect a Second Half Rebound

The general thought process of most analysts argues for a stronger second half of the year. I am not so optimistic for the following reasons:

1.) Gas prices will not stay low. As I mentioned in today's oil market analysis, there is little hope for a continued period of low oil prices; the fundamentals of the market are simply far too bullish. Barron's article on the oil market last week summed up the basic situation:

Despite the recent 20% decline from April highs, new highs on crude, heating oil, diesel fuel, jet fuel and gasoline seem likely over the next 12 months. Following some further easing over the summer, the second leg of the long-term bull market in petroleum–the first occurred in 2007-08–probably will begin this fall.

As oil producers' spare capacity gradually declines to worrisome levels, the average monthly price could reach a record $150 per barrel by next spring, with spikes to $165 or $170. With this, $4.50-a-gallon gasoline will become the norm. That will put a huge dent in consumer wallets, while ramping up the desirability of fuel-efficient cars.

The continued short-term easing of oil prices should benefit the economy over the summer, only to exact a much larger payback later. The projected oil shock of spring 2012 will hurt the economic expansion, but not kill it, pruning about 1.5 percentage points from quarterly growth in real gross domestic product.

As such, I believe the choke hold of high oil prices will continue to exact growth concessions from the economy.

2.) The EU situation is continuing to lower overall confidence. Earlier this week, Portugal's debt was cut to junk status and there is already talk of problems with the Greek bail-out package. At this point, there is little reason to see this situation getting noticeably better -- that is, better to the point where it is no longer hurting overall confidence. Add to that the ECB is now hawkish on interest rates, and you have an added economic braking mechanism to contend with.

3.) The jobs market in the US continues to fluctuate around 9% unemployment, and initial new claims remain above 400,000. Washington is acting like its 1938 all over again, which will do nothing but hurt economic growth in the short-run as well as negatively impact confidence in the economy. Simply put, Washington is doing literally everything wrong right now, and the net result will be diminished growth.

4.) As I pointed out yesterday, Brazil now has an inverted yield curve, India's is flattening and China is raising rates and reserve requirements to lower overall inflation. In short, the central banks of the economies that drove world wide growth are raising rates to slow their respective economies. This will add to lower growth in the US, which has relied on exports to drive the last two years of expansion. We've already seen a wave of PMI slowdowns across Europe as a result.

5.) With the end of QEII, the largest buyer of treasury securities has left the market. The end result has been rising interest rates.

I seriously hope my analysis is wrong on this -- and if you see bright spots, please let me know. I just don't see any right now. At best, I see a muddling growth fluctuating around 2%.


Thursday Oil Market Analysis

Last week, I wrote the following about the oil market:
My long-term prediction for oil is for prices to again move higher and stay there because of the macro level supply/demand situation (see the link above for the charts). However, right now the chart has to move through a fair amount of technical resistance. Prices have to advance through the EMAs and several resistance levels. I would give prices through July or mid-August to accomplish that feat before moving into higher territory.
At the heart of my analysis is this basic situation:
The oil market is caught between two different issues. In the short-term, there is concern about the pace of expansion. Lower growth = lower oil demand = lower prices. However, as I pointed out above, there has been a strong, fundamental, long-term shift in the world's oil demand as countries like India and China have grown with their demand supplementing US/EU demand, providing a long-term floor under prices. But currently, these countries are also tying to slow growth due to increased inflationary pressures within their respective countries. In other words, there is currently a great deal of negative sentiment weighing down oil prices.


With 2 billion more people now demanding oil -- and supplies incredibly tight -- there is little hope for continued downward pressure on oil prices.

Simply put, there is tremendous amount of pressure on oil prices to move higher, with little to no reason for them to move lower. As such, arguing for higher oil prices is a no brainer.

Let's take a look at the chart:


Prices have sold-off for several reasons. First, the IEA coordinated a massive release of oil to offset lost production due to the Libya situation. In addition, for the last month there has been concern about the pace of economic recovery, leading traders to sell net long positions. However, we are now right in the middle of the summer driving season which will add upward pressure to prices. Additionally, nothing has changed in the supply and demand situation to warrant a change in the overall outlook.

On the chart, prices are now moving through several layers of technical resistance after their sell-off. However, they have already moved through the 10 and 20 day EMA as the MACD has printed a buy signal. The 10 day EMA is moving higher and the 20 day EMA is moving sideways. The next layers of resistance are the 50 day EMA and the 97.5/98 price level.

As I wrote last week, moving through this many layers of technical resistance takes time. I gave it about a month, which I still think seems like an adequate amount of time make this move. As such, I still see prices moving higher for the summer and for prices to be back over $100 within a month.

Wednesday, July 6, 2011

Brazil's Yield Curve is Inverted

From Bloomberg:


This is not what you want to see in an economy that is driving world growth.

China Raises Rates Again

From Bloomberg:

China raised benchmark interest rates for the third time this year after inflation accelerated to the fastest pace since July 2008.

The one-year deposit rate rises to 3.5 percent from 3.25 percent, effective tomorrow, the People’s Bank of China said on its website today. The one-year lending rate will increase to 6.56 percent from 6.31 percent.

Today’s move may fuel concern that monetary tightening will trigger a slowdown in the world’s second-biggest economy. A manufacturing index fell in June to the lowest level in 28 months on weaker growth in orders and output.

Inflation “is the Chinese authorities’ top policy priority for the near future,” Peng Wensheng, a Hong Kong-based economist with China International Capital Corp., said before the announcement.

I highlighted the increase in BRIC countries' interest rates yesterday. This is obviously more of the same. These economies are driving world growth. As they raise their rates, their economies will slow, hurting US growth.

The yield curve and pre-WW2 recessions

- by New Deal democrat

This continues my look at leading indicators as they may apply to pre-WW2 deflationary recessions. I have already looked at BAA bonds, housing starts, commodity prices, and the stock market. Today I will look at the yield curve.

Since 1960, the yield curve, in conjunction with "real M1," accurately foretold 8 of 8 recessions with no false positives. This is the "Kasriel Recession Warning Indicator" (named for Paul Kasriel of the Northern Trust Company). This indicator has also worked in reverse. If both the yield curve and real M1 were positive, the economy was expanding.

Two and a half years ago, I wrote a 5 part series, Economic Indicators during the Roaring Twenties and Great Depression, to see how well the Kasriel indicator worked before 1960. This series was sparked in large part by the most unnerving economic graph I've ever seen, from Ned Davis Research, the most relevant part of which is reproduced below:


In this graph, Fed Funds rates (pre-1935 rates are from the NY Fed) are in green, and long term government bond rates are in red (you can ignore the other two). As you can see, for virtually the entire period beginning in late 1929 and continuing right through the Great Depression and into the 1950s, the yield curve was resolutely positive. And yet that period coincided with the two worst downturns in the last 100 years, as well as three other recessions.

With help from a paper by a fellow named Ben Bernanke, I was able to reproduce graphs of long term interest rates (green), the fed funds rate (blue), and the CPI (red). Here they are for the 1920's:


And here they are for the early 1930's:


The result is, the yield curve inverted and accurately signaled the inflationary recession of 1920-21, the 1926 recession, and the onset of the 1929 "great contraction," but utterly failed to forecast its continuation, or the 1938 recession, or the two immediate post-WW2 recessions.

Of particular note, from early 1928 until late 1929, the yield curve was inverted. In fact, during 1929, with fed interest rates 6% over the CPI, the inverted yield curve (with long term bonds ~1.5%-2.5% under short term rates), was the most serious inversion until 1981 when Paul Volker killed inflation by raising interest rates some 9% over the inflation rate.

To sum up: in deflationary recessions, a positive yield curve is useless. An inverted yield curve in the face of deflation, however, does accurately signal the onset of a deflationary recession.

A Noted Increase in the Calls for Infrastructure Spending

From Hedge Fund Manager Barton Biggs:
Instead, Mr. Biggs, former chief global strategist for U.S. investment banking powerhouse Morgan Stanley, demanded the U.S. government temporarily return to ideas used in the Great Depression as a way to get the country back to higher growth.

"What the U.S. really needs is a massive infrastructure program … similar to the WPA back in the 1930s," he says.

The plan would be to employ some of the many unemployed people, jump start the economy, as well as help catch up with Asia, which is building state-of-the-art infrastructure from new mechanized port facilities to high-speed trains.

He suggested financing such building through the sale of U.S. Treasuries.

From Bill Gross of PIMCO:

Additionally and immediately, however, government must take a leading role in job creation. Conservative or even liberal agendas that cede responsibility for job creation to the private sector over the next few years are simply dazed or perhaps crazed. The private sector is the source of long-term job creation but in the short term, no rational observer can believe that global or even small businesses will invest here when the labor over there is so much cheaper. That is why trillions of dollars of corporate cash rest impotently on balance sheets awaiting global – non-U.S. – investment opportunities. Our labor force is too expensive and poorly educated for today’s marketplace.

In the near term, then, we should not rely solely on job or corporate-directed payroll tax credits because corporations may not take enough of that bait, and they’re sitting pretty as it is. Government must step up to the plate, as it should have in early 2009. An infrastructure bank to fund badly needed reconstruction projects is a commonly accepted idea, despite the limitations of the original “shovel-ready” stimulus program in 2009. Disparate experts such as GE’s Jeff Immelt, Fareed Zakaria, Jeffrey Sachs and Paul Krugman believe an infrastructure bank to be an excellent use of deficit funds: a true investment in our future. While the current administration admits that the $25 billion in Recovery Act spending on infrastructure only created 150,000 jobs, it also stabilized and improved this nation’s productivity for years to come. Clean/green energy investments also come to mind, most of which require government funding and a government thrust in order to create millions of jobs.

From Larry Summers:

Larry Summers, the outgoing director of the White House National Economic Council, said the US must ramp up spending on domestic infrastructure to drive the economic recovery.

Speaking at the Financial Times’s View from the Top conference in New York, Mr Summers called it a “short-term imperative and a long-term macroeconomic imperative” that the US government increase infrastructure investment. He said that a combination of low borrowing costs, cheap building costs and high levels of unemployment in the construction sector made this the ideal time to rebuild roads, bridges and airports.

What's interesting is the financial people don't seem to be concerned with fixing the deficit; they view the overall threat to growth as the primary problem facing the economy right now.

Treasury Tuesdays

Last week, I wrote the following about the Treasury market:
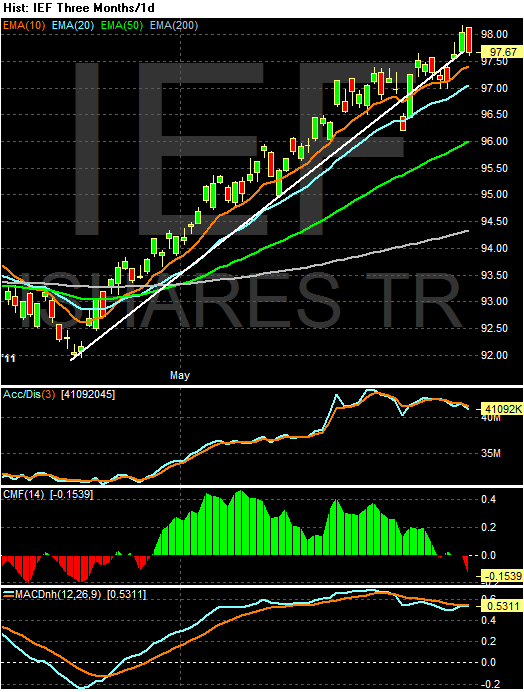
The fact that the long end of the curve didn't follow the belly higher is interesting. That and the continued deterioration in the TLT's technicals tells me the long end of the curve is selling off -- or at least holding even for awhile. I'm not convinced the IEFs are going to maintain a strong rally here, largely because the long-end of the curve is not following through. As such, I don't see the IEFs current move higher continuing. That would analysis would change if the TLTs break higher to new levels.
The Treasury market sold-ff last week. Yesterday, the WSJ today reported on the sell-off thusly:
The three-month run-up in Treasurys prices may be running out of steam—if the market isn't poised for an outright reversal. The longest selling streak in months has persuaded some analysts that yields have reached the bottom.

U.S. Treasury debt has sold off after a set of weak government debt auctions in the past five sessions—and has done so on notable trading volume. Until that point, prices had rallied since early April, fueled by a drumbeat of soft U.S. economic data and alarming headlines out of Europe.

On June 27, the benchmark yield touched a 2011 low of 2.842%. It has since catapulted above 3.20%. The 0.342 percentage-point jump in the past five sessions is the largest weekly advance since August 2009, prompting some analysts to suspect the bull run may be fizzling out. Bond yields move inversely to prices.

Goldman Sachs Group chief interest-rate strategist Francesco Garzarelli, on Thursday said he believed the Treasurys rally is over, as U.S. economic activity is expected to pick up in the second half of the year. He isn't the only one.

Barring any bad news from Europe, "we suspect the bottom is in," said Eric Green, chief U.S. rates strategist at TD Securities. He specifically pointed to the past months of weak data giving way to stronger economic growth and more attention to inflation.

Chris Ahrens, interest-rate strategist at UBS, says he sees yields pushing higher. "After a steady downward path since early April, it marks an important moment for the bond markets," he said. "The pressure is going to be on data to prove the more constructive [economic] scenario."

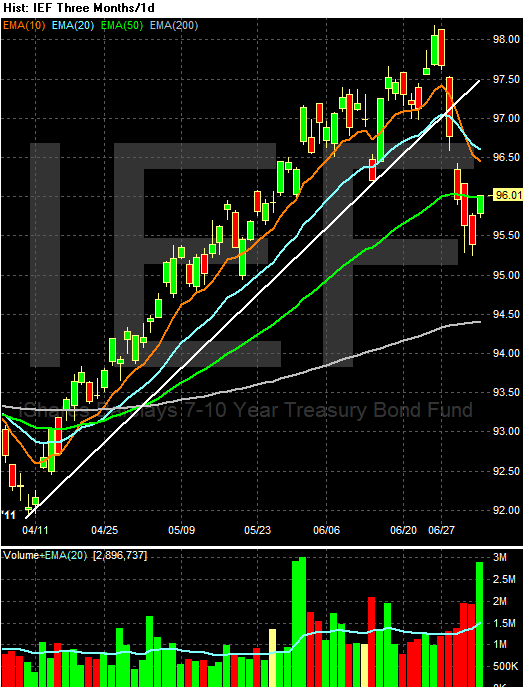
I'm not sold on the second half recovery story yet; although the recent action in the equity, copper and bond markets indicate traders are certainly buying into the argument. I do think the end of QEII is having a pronounced effect as the largest buyer of debt is effectively leaving the market. Let's take a look at the charts:

The 5-minute IEF chart shows the strength of the downtrend over the last 10 days. I've included Fibonacci retracement levels, as I would expect some type of rebound trade this week.


Prices have clearly moved below the 10, 20 and 50 day EMAs on an increase in volume. The 10, and 20 day EMA are both moving lower, and the 10 day EMA has crossed below the 20 day EMA. Prices have broken the upward sloping trend line. I would expect prices to rebound into the 10 or 20 day EMA before continuing their move lower with a price target of the 200 day EMA.


The TLT chart is slightly more bearish, as the 50 day EMA is also moving lower and prices are right below the 200 day EMA. However, notice the drop-off in volume as prices have moved lower these last two days, indicating the market may be using the 200 day EMA as a place to "pause" and catch its breath.

Given the low trading volume and the price action around the 200 day EMA, I'm thinking the TLTs will pause here or rebound into the EMAs. However, I think the IEFs are targeting the 200 day EMA. Given the Fed's departure, I believe the Treasury market is moving lower for the time being.

Tuesday, July 5, 2011

BRIC Economies Are Raising Short-Term Interest Rates

Consider the follow charts of short-term rates in China, Brazil and India:


Three of the four BRIC countries are hiking interest rates to combat inflation. Higher rates = lower growth.

Economic Week in Review

On Monday's I'm going to start looking at the previous week's major economic releases, analyzing the numbers along the same lines as used in the Fed's Beige Book. The reason is simple: this will help us all digest the news in a way that helps us understand the macro-level direction of the economy. Unlike NDD's higher frequency analysis, this will focus on the largely coincidental economic numbers that are released monthly and in some cases quarterly.

Consumer spending: Real personal consumption expenditures dropped .1%. The primary reason for the decrease is a drop in both non-durable and durable goods expenditures, which was caused by a drop in auto purchases. Real PCEs have now dropped the last two months, after a strong rise starting in early 2009. Consumer sentiment is still weak, as evidenced by both a drop in the Conference Board's number and the University of Michigan consumer sentiment number.
Link
Manufacturing: The ISM number surprised on the upside, but the new orders number was weak, as was the overall production number. In addition, the Chicago PMI also surprised on the upside. However, as I'll show later today, emerging economies are raising short-term interest rates, thereby slowing their respective economies. We've also seen signs of a slowdown at the global level in manufacturing, leading me to conclude this months numbers were abberations in an otherwise slowing manufacturing environment.

Real Estate: The good news here is the Case Shiller number increased, indicating the housing market may be bottoming. As I noted last week (see also here and here) -- and as NDD has also pointed out (see this post as well)-- it appears the housing market is closer to a bottom than conventional wisdom implies.

While the good news last week was Greece avoiding a default, the overall tenor of most reports was negative. Consumer sentiment is slipping, causing a drop in spending. Since this is 70% of US GDP, this is hardly a good development. Globally, manufacturing is in a slowdown, largely caused by emerging economies raising interest rates to control inflation.

Equity Week in Review and Preview of the Upcoming Week/Month

Last week, I wrote the following about the markets:
Right now, the 200 day EMAs are providing enough technical support to allow the markets to "catch their breath" from the recent sell-off. Traders have understandable concerns about the pace of recovery and the Greek debt situation. However, the disciplined pace of the sell-off and the stalling of the descent at the 200 day EMA indicate there is enough bullish sentiment to give the market pause -- at least for now.

However, a strong, multiple market break (involving 2 of the 3 major averages) below the 200 day EMA would be a watershed moment for this market. Should that happen, I would wait for a rebound into an EMA and then short.
I obviously did not see the strength of last weeks advance. Take a look at this five minute chart:


That is an incredibly strong rally that lasted for the entire week. All the EMAs are moving higher, prices are using the EMAs for technical support and there is a strong uptrend in place. The chart is printing a series of higher highs and higher lows -- a classic rally chart.


Prices have clearly bounced off the 200 day EMA and moved through all the EMAs. All the EMAs are moving higher, and the 10 day EMA has crossed over the 20 day EMA. Also note the strength of the bars, especially Friday's. Four of the five bars last week have very long bodies, indicating prices advanced throughout the day. There was also a nice bump up in volume for the last three trading days of the week. The fact the market did not sell-off on Friday is incredibly encouraging.


The A/D and CMF all indicate that money is flowing into the market, and the MACD indicates momentum is increasing.


The above chart shows possible support levels in case of a market pullback, which would be expected after a strong rally like that which occurred last week.

This week's rally was caused by three factors: first, we had end of the quarter fund manager window dressing, which forced managers with extra cash to put it to work. Second, the Greek vote agreeing to new austerity measures means the problems caused by the EU periphery have abated at least for now. Third, the market was oversold.

At this point, we should acknowledge that the stock market is a leading indicator. The question now becomes, was this week's advance a sign that equity traders think the worst is over, and therefore it's time to get into the action? The weakness in the Treasury market last week would bear this out, as would the rise in the oil market and copper's recent advance through key resistance areas. However, I'm personally not sold on a third or fourth quarter rebound yet. Consumer spending is weakening, global manufacturing is softening, emerging economies are increasing interest rates (US exports have been strong during the recovery) and Washington is full of idiots doing everything they can to screw up the economy. I would need to see an advance through previous highs on multiple indexes (with the Russell 2000 being one) before I'm sold on the veracity of this rally.

Monday, July 4, 2011

Happy Fourth of July

We'll be back tomorrow morning when the markets open

Friday, July 1, 2011

Weekly Indicators: manufacturing and commercial construction improve edition

- by New Deal democrat

Monthly data released this week showed relief from the manufacturing slowdown, as the Chicago PME rebounded to a strong 61.0 and the ISM manufacturing survey also rebounded to 55.3. The employment, new orders, and vendor delivery components were also up slightly.

New construction spending was mixed, with residential construction in May down 2%, but nonresidential construction up 1.2%. Residential construction is meandering near the bottom of a 3% range established since last July, while nonresidential construction has essentially been flat so far this year (i.e., it appears to be bottoming).

Real personal income was flat, and real personal spending decreased -0.3% in May, indicating further impact of high gas prices, and consumer confidence and University of Michigan consumer sentiment were both down. The Case-Shiller house index also declined, but but not as much as expected.

The high-frequency weekly indicators were also mixed this week.

Let's start with the good:

YoY weekly median asking house prices from 54 metropolitan areas at Housing Tracker showed that the asking prices declined only -3.5% YoY. This is the best reading since May 2007. The areas with double-digit YoY% declines decreased by three to 7. The areas with YoY% increases in price increased by four to 7. This adds more weight to the belief that in nominal if not real terms housing prices may bottom as early as this winter.

The ICSC reported that same store sales for the week of June 25 increased 3.0% YoY, and increased 2.9% week over week. This is the best YoY comparison in a month. Shoppertrak failed to report this week.

Other series remained in their recent range:

M1 was up 0.5% w/w, up 0.2% m/m, and up 12.5% YoY, so Real M1 was up 9.1%.
M2 was up 0.3% w/w, up 0.5% m/m, and up 5.2% YoY, so Real M2 was up 1.8%.
Real M1 remains very bullish, while Real M2 remains stuck in the caution zone under 2.5%

The BLS reported that Initial jobless claims last week were 428,000. The four week average increased slightly to 426,750. We appear to have stabilized under 430,000.

The Mortgage Bankers' Association reported that seasonally adjusted mortgage applications decreased 3.0% last week. It was 4.5% higher than this week last year. This is the fifth week in a row that YoY comparisons in purchase mortgages were positive. Except for the rush at the two deadlines for the $8000 mortgage credit, these are the first YoY increases since 2007. Refinancing decreased 7.6% w/w despite a decline in mortgage rates.

Topping the weak or bad numbers is the report from Railfax, which was up a mere 1.3% YoY for the week. Baseline traffic is actually down 662 carloads from a year ago. Cyclical traffic was also down, 7141 carloads YoY. Intermodal traffic (a proxy for imports and exports) was the only component up this week, at +19,128 carloads YoY. This series is very close to turning negative on a carload basis.

Oil was near $94 a barrel midday Friday, right at the level of 4% of GDP which according to Oil analyst Steve Kopits is the point at which a recession has been triggered in the past. Gas at the pump fell for the sixth week in a row, declining $.08 more to $3.57 a gallon. Gasoline usage at 9261 M gallons was -2.2% lower than last year's 9462. This is the first time in five weeks that gasoline usage has been significantly less than last year.

The American Staffing Association Index remained at 87 for the third week in a row This series is just barely above a stall, and is a significant danger sign. It is weaker than early 2007, but not trending down as during the recession.

Weekly BAA commercial bond rates remained the same at 5.73%. This compares with yields on 10 year treasury bonds decreasing .01% to 2.99%. The continuing decline in treasury rates shows fear of deflation, and the relative increase in corporate rates shows a slight increase in relative distress in the corporate market.

Adjusting +1.07% due to the 2011 tax compromise, the Daily Treasury Statement showed that for the first 21 days of June 2011, $135.2 B was collected vs. $136.5 B a year ago, for a decrease of $1.3 B YoY. For the last 20 days, $134.8 B was collected vs. $115.9 B a year ago, for an increase of $18.9 B, or 15%. Use this series with extra caution because the adjustment for the withholding tax compromise is only a best guess, and may be significantly incorrect.

While much of the data shows a stall, almost none of it shows any actual decline in economic activity. Housing and Oil prices continue to appear to be moving in the right direction. Contractionary fiscal policy coming out of Versailles remains the biggest risk.

Have a happy and safe Fourth of July weekend!

Stock prices and pre-WW2 recessions

- by New Deal democrat

This continues my look at leading indicators as they may apply to pre-WW2 deflationary recessions. I have already looked at BAA bonds, housing starts, and commodity prices. Stock market prices, in the form of the S&P 500, of course are part of the modern set of LEI. How did they perform in the Roaring Twenties and Great Depression? Let's have a look.

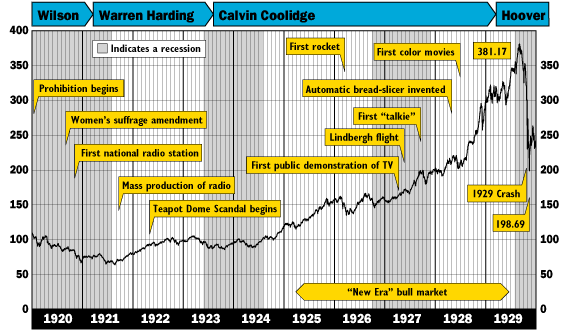
Here is a graph of the DJIA (the S&P 500 wasn't created until later) during the Roaring Twenties:


The 1920-21 recession was very much like the 1981-82 recession. High inflation during WW1 was broken via a deep but short-lived bust. Thereafter while the stock market did accurately top and bottom before the peak and trough of the 1923 recession, it rose right through the 1926-27 recession and infamously topped in September 1929 after the downturn that became the Great Depression had already begun.
For a more detailed look, here is a chart of the yearly highs and lows of the DJIA, with the date of those highs/lows in parenthesis, compared with recession dates:

YearYr. high (date)Yr. low (date)Recession dates
1920108.76 (Apr) 66.75 (Dec) 1/20-
192181.50 (Dec) 63.90 (Aug) - 7/21
1922103.43 (Aug) 78.59 (Nov) -
1923105.38 (Mar) 85.76 (Oct) 5/23-
1924120.51 (Dec) 88.33 (May) -7/24
1925159.39 (Nov)115.00 (Mar) -
1926166.64 (Aug) 135.20 (Mar) 10/26-
1927202.40 (Dec) 152.73 (Jan) -11/27
1928300.00 (Dec) 191.33 (Feb) -
1929381.17 (Sep) 198.69 (Nov) 8/29-
1930294.00 (Apr) 157.51 (Dec) cont.
1931194.36 (Feb) 73.79 (Dec) cont.
193288.78 (Mar)41.22 (Jul) cont.
1933108.67 (Jul) 50.16 (Feb) -3/33
1934110.74 (Feb) 88.57 (Jul) -
1935148.44 (Nov)96.71 (Mar)-
1936184.90 (Nov) 143.11 (Jan) -
1937194.40 (Mar) 113.64 (Nov) 5/37-
1938159.51 (Nov) 96.95 (Mar) -6/38
1939155.92 (Sep)121.44 (Apr) -
1940152.80 (Jan)111.84(Jun) -


The DJIA did make a trough in 1932 before the end of the contractionary part of the Great Depression, and did both peak and trough before the economic peak and trough of the 1937-38 recession.

Of the 9 total economic peaks and troughs in this period, the DJIA was a leading indicator 5 times, coincident 2 times, and missed one recession altogether. In short, useful but not perfect.

Manufacturing Slowdown is Global

Over the last two months or so, we've seen a variety of US manufacturing indexes show signs of a slowdown. However, the slowdown is not limited to the US

From Bloomberg

Manufacturing growth is slowing in from China to Europe, creating a dilemma for central bankers considering higher interest rates to combat inflation.

China’s factory index fell to the lowest level since February 2009, while in the 17-nation euro area, a gauge slipped to to an 18-month low. German manufacturing expanded at the weakest pace in 17 months, while Italy, Ireland, Spain and Greece contracted.

“There is a broad-based slowdown taking place in the manufacturing sector,” Silvio Peruzzo, an economist at Royal Bank of Scotland Plc in London, said by telephone. “But it’s still too early to jump on the view that we’re heading toward an environment where activity will be contracting.”

Europe’s debt crisis and slowing U.S. growth are damping demand for goods, putting pressure on policy makers to delay further rate increases even as prices gain. Inflation quickened to the fastest pace since 2008 in China, exceeded 20 percent in Vietnam last month and prompted protests in India. Euro-area inflation remained at 2.7 percent in June, exceeding the European Central Bank’s 2 percent ceiling for a seventh month.

Inflation pressures have prompted Asian central banks to be among the quickest to withdraw monetary stimulus as growth accelerated following the global recession in 2009. India, South Korea, Thailand and Taiwan raised their benchmark rates last month to contain rising prices, while China ordered lenders to set aside more cash as reserves.

See also this article from the WSJ

The article highlights the basic global themes we've seen over the last few months.

1.) Inflation is accelerating in emerging economies -- the same economies that are now the engine of global growth. As inflation has accelerated, emerging economy central banks have raised their respective rates. In fact -- we've seen emerging market's bond markets go inverted over the last few months.

2.) Not mentioned in the article -- but of equal importance -- is the effect of the Japanese earthquake, which has negatively impacted a variety of manufacturing issues.

3.) The US appears be hitting a slowdown caused by a lack of consumer confidence. With unemployment still high, job growth weak, gas prices high and political paralysis the standard method of conflict resolution in Washington, consumers appear to be lessening their spending on all but necessities at this point. As this makes up 70% of GDP growth, the overall impact is quite negative.


Thursday, June 30, 2011

Friday Dollar Analysis

Last week, I wrote the following about the dollar:

The A/D line shows a big move into the market in early May, but not much since. The CMF confirms the lack of movement into the market. The MACD shows increasing momentum, but note the current peak is lower than the last, indicating overall declining momentum right now. While the 10 and 20 day EMAs are still below the 50 day EMA, the shorter EMAs are now moving sideways rather than lower. They are also intertwined. The downward angle of descent on the 50 day EMA is also lower.

The chart is showing many signs of a reversal in progress.

The story in the currency markets for the last few weeks has been the Greek situation. Any story that was Greek resolution negative moved the euro lower and the dollar higher while the opposite was true. It is interesting to note the dollar is probably forming a bottom at an apex of the Greek vote story.

Let's start by looking at the really long view:


Last year, the market formed a head and shoulders pattern. In addition, since the top in mid-2010, prices have formed a down/up/down, lower high/lower low pattern. Currently, prices are forming a triangle pattern.


The above chart shows the consolidation in more detail. First, note the EMAs are moving closer together, which is usually a sign of market consolidation.


The jump in the A/D four weeks ago shows a big volume spike -- but nothing since then. The CMF indicates that money flowing into the market is evening out, while the MACD shows a slowing momentum.

I'm still thinking the dollar is forming some type of bottom at this time. The EU situation appears to be at a head, giving the market "closure."

Special Bonddad blog midyear graph-reading contest

- by New Deal democrat

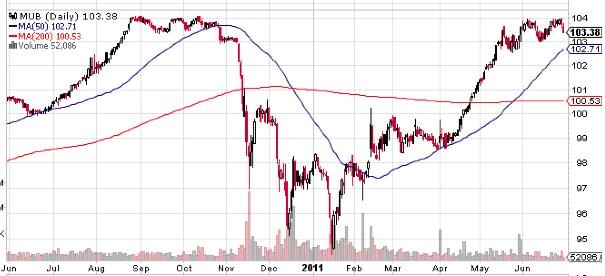
Today is June 30, and that means tomorrow starts a new fiscal year for most states. Which means it certainly is about time for Meredith Whitney's forecast of 50 to 100 significant municipal defaults totaling about $100 billion this calendar year, to start kicking in. Let's pull up a graph of a Municipal Bond index fund for the last year and see how far it's plummeted:


Oh, wait ....

So your special midyear graph-reading contest is, on what two dates did the Pied Piper of Doom predict that "the shit may, indeed, be hitting the fan concerning ... the truly dire straits of the finances of at least some of our country's states and municipalities," and specifically tout Whitney's prediction of a "meltdown" above?

Hint: he at least managed not to bottom-tick the price this time.

P.S. As of the most recent data, state tax collections continue to surprise to the upside, although that still doesn't make up for the loss of federal assistance.

Treasury Market Selling Off?

From the WSJ:

For the third consecutive session, Treasury investors on Wednesday balked at buying new bonds at a large government-debt auction, sending prices lower and yields higher.

The yield on the benchmark 10-year note reached 3.11%, its highest since May 25. Yields on the 10-year note have risen every day this week, adding about 0.24 percentage point since Friday and sparking speculation that the bull run in the bond market may have passed its peak.

The Treasurys on sale on Wednesday were $29 billion of seven-year notes. That followed sales of two- and five-year notes, all of them showing low levels of demand in the private sector and among foreign buyers.

The poorly received auctions raised eyebrows ahead of Thursday's official finish of the Federal Reserve's second bond-buying initiative, a $600 billion "quantitative easing" program widely known as QE2.

This is something I've been writing about for the last few week (see here, here and here).


Small Business Lending Heating Up?

From Reuters:

Borrowing by small U.S. businesses rose at a record pace in May, data released by PayNet Inc on Thursday showed, a sign that economic growth is poised to pick up in coming months.

The Thomson Reuters/PayNet Small Business Lending Index, which measures the overall volume of financing to U.S. small businesses, rose 26 percent in May from a year earlier, PayNet said.

The index is now at its highest since July 2008, two months before the collapse of Lehman Brothers and the near derailment of the world financial system.

.....

"If small businesses are taking these kind of chances, taking risks, making long term investments, they are seeing some long-term opportunities on the horizon," PayNet founder Bill Phelan said in an interview. "That's got to be a big positive sign for the economy."

Separate data also released on Thursday showed small business loan defaults at their lowest in five years, tying records set in April and May 2006.

Accounts in moderate delinquency, or those behind by 30 days or more, fell in May to 1.95 percent from 2.06 percent in April, PayNet said on Thursday.

Accounts 90 days or more behind in payment, or in severe delinquency, fell to 0.59 percent in May from 0.63 percent in April.

I have never heard of Paynet, but thought this was an interesting development in light of recent news.

Wednesday, June 29, 2011

Thursday Oil Market Analysis

Last week, I wrote the following about the oil market:
The oil market is caught between two different issues. In the short-term, there is concern about the pace of expansion. Lower growth = lower oil demand = lower prices. However, as I pointed out above, there has been a strong, fundamental, long-term shift in the world's oil demand as countries like India and China have grown with their demand supplementing US/EU demand, providing a long-term floor under prices. But currently, these countries are also tying to slow growth due to increased inflationary pressures within their respective countries. In other words, there is currently a great deal of negative sentiment weighing down oil prices.
On the same day, the IEA announced a coordinated effort to release oil from various strategic oil reserves in an effort to lower prices, which in fact happened.

The above analysis still stands: there are short-term issues that are hitting oil prices, but longer term supply and demand are still incredibly tight. Professor Hamilton summed up the basic issue in his article on the release:

In any case, the deed is now done, and the IEA has run an interesting experiment for us in how oil markets function. But I would recommend against further SPR sales, regardless of the final outcome of the current effort. The reason is that I see the long-run challenge of meeting the growing demand from the emerging economies as very daunting, and in my mind is the number one reason we're talking about an oil price above $100/barrel in the first place.

A one-time release from the SPR, or even a series of releases until the SPR runs dry, does nothing whatever to address those basic challenges.

And the growing demand from emerging markets is the primary underlying force in the oil market right now, which I believe is putting a floor under oil prices.

That being said, let's take a look at the chart:

The price chart is still negative. All the EMAs are moving lower and prices have been using the EMAs are technical resistance. Also notice that the EMAs have fanned out, obtaining a bit of distance from each other. The MACD is also weak; it's in negative territory and has shown little advance over the last month. However, it is about to give a buy signal.

My long-term prediction for oil is for prices to again move higher and stay there because of the macro level supply/demand situation (see the link above for the charts). However, right now the chart has to move through a fair amount of technical resistance. Prices have to advance through the EMAs and several resistance levels. I would give prices through July or mid-August to accomplish that feat before moving into higher territory.

June YoY house price declines least since May 2007

- by New Deal democrat

Consider two different scenarios by which house prices could still decline 25% in real, inflation-adjusted terms, from the present:

(1) nominal prices decline 5% a year for 5 years, and inflation is 0% over that time.
(2) nominal prices do not decline at all over the next 5 years, but inflation is 5% a year.

Both of those give us "real" price declines of 25%, but with very different results, and very different amounts of pain.

In the first scenario, more and more homeowners are "underwater" with houses not worth what they paid for them, and not even worth the outstanding mortgage amount. They are unable to sell, since they can't bring cash with them to the closing table to make up the difference. More and more allow their houses to slide into foreclosure, thus increasing the shadow inventory of bank-owned houses.

In the second scenario, however, no more homeowners whatsoever are "underwater." Even better, mortgage payments - and purchases - are made with inflated currency. There is no further incentive to hand in the keys and walk away from the house, and shadow inventory is worked off.

Needless to say, the second scenario is a lot less painful than the first one and yet accomplishes the same result.

Over the last several weeks, I've read more and more commentary suggesting that at least nominal prices in the housing market might start to make a bottom. Now that we have the most recent Case-Shiller report (from April, but really a February, March, and April average), and the final June asking price data from Housing Tracker, which accurately showed the turn at the top of the market in 2006, let's take a look at whether housing prices may better fit the first or second scenario.

Here is the updated chart of YoY% change in asking prices from Housing Tracker's 1,000,000+ home database:

Month2007 2008 2009 2010 2011
January ----7.5%-11.5%-5.8%-8.7%
February ----7.8%-12.0% -5.2%-8.4%
March ----8.3% -10.9%-5.0%-7.3%
April -2.7% -8.6%-9.6%-5.0%-6.8%
May -3.5% -9.1% -8.1%-5.0%-5.6%
June -5.0%-9.8%-7.0%-5.0%-4.4%
July -5.4% -10.4%-6.1% -5.1%---
August -6.0% -10.6%-5.5%-6.1%---
September -6.2% -11.1%-5.1%-6.6%---
October -6.7% -11.4% -4.5%-7.0%---
November -6.6%-11.7%-4.5%-6.7%---
December -7.2% -11.4%-5.6% -7.8%---


The YoY -4.4% decline in June is the smallest YoY decline since May 2007. Here is the same information (through 2 weeks ago) shown graphically (h/t Silver Oz):


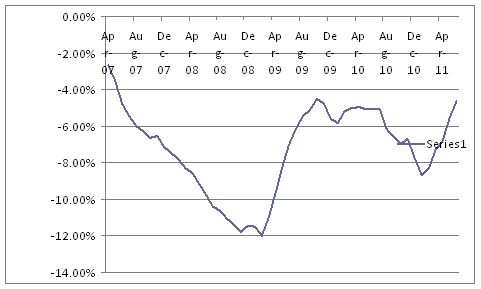
In comparison, here is the YoY% change up through the February - April average in the Case-Shiller 20 city index:


Over the time period of comparison, the Housing Tracker trend in asking prices has appeared to run 1 to 4 months ahead of the Case-Shiller sales data. Keep in mind that the most recent Case-Shiller data compares sales from a period when buyers and sellers wanted to close quickly to take advantage of the $8000 housing credit, with a period one year later where there is no credit. Even so, it looks like the YoY% change may be close to bottoming.

I fully expect the Case-Shiller series to bottom out in YoY% terms within the next several months, and to mirror the more current better YoY comparisons in the Housing Tracker database. In other words, it continues to look like the second scenario set forth above is going to be closer to the truth, and among the possibilities, that's good news.

Quick Update on the Equity Markets

Consider this chart from Bespoke Investment Group regarding the last two days of equity price action:


Notice that the rally has been led by more speculative areas of the marker -- technology and consumer discretionary.

Consider this in line with the treasury market, which should absorb the outflow of money from the stock market in the event of an equity sell-off. For the last few weeks, the Treasury market rally has shown decreasing momentum (see here and here), with the long-end of the curve moving sideways and the belly of the curve rallying a bit. At the same time, the stock market has found support at the 200 day EMA (see here and here). The question now becomes -- is this rally in the markets the beginning of a new trend, or a simple relief rally from the sell-off?

There are several possible scenarios. This chart from Channels and Patterns Blog offers a very realistic possibility.


That chart makes sense if the market becomes bearish on the second half outlook. While many economists have lowered their growth projections, the consensus is still for second half growth, albeit below trend. However, should we continue to see bad news for the foreseeable future, this is a real possibility.

A second possibility is the current sideways action is a rectangle consolidation, which traders are using to consolidate gains, and take some profits off the table. This makes sense if the current Treasury market stall is caused by a change in growth perceptions rather than concern about a possible default.

Either way, the markets are very much in a "wait and see" mode.

The Economic Ball's In Washington's Court -- And That Ain't Good

As I see current economic events, the real story actually lies in Washington.

First, recent economic news has been poor. It started with high commodity prices squeezing margins and consumers. At the same time, we saw international growth engines India, Brazil and China raise interest rates and reserve requirements to slow their economies, thereby also muting the increased demand caused by their growing economies. In the US, consumers have switched focus from mass consumption to paying down debt and a frugal approach to buying, making the slowing demand from India and China that much more important as it creates a slight vacuum for macro-level, international demand.

This was followed by the shock of Japan's earthquake, which more or less completely threw-off global supply chains for consumer electronics and autos. This added further downward momentum to the manufacturing cycle, which was one of the strongest ares of the domestic economy. At the same time, the budget talks were then getting underway with every event being reported as if the situation were in a cage match.

In short, all action appears to be on hold until Washington solves (and I use that word in the most liberal manner possible) the current budget impasse. As I pointed out yesterday, this is creating a tremendous amount of uncertainly as both possible "solutions" offer little to no real help for the economy in the short-run. As such, I think most major economic players are moving into a disaster mentality, conserving capital and putting all major plans on hold.

Tuesday, June 28, 2011

Wednesday Commodity Round-Up


The long-term gold chart shows that prices have broken one uptrend, but the longer trend started last year is still in place. Prices have technical support in the 144 and 140 area.


Prices are now below the 10, 20 and 50 day EMA. The 10 and 20 day EMAs are both moving lower, and the 10 day EMA has crossed below the 20. The 50 day EMA is now moving sideways. Also note that after peaking in late April, prices have yet to approach previously established highs.


While the A/D line shows a slight increase in inbound money, the CMF and MACD are both moving in negative directions. These two indicators tell us that momentum is decreasing and less and less money is flowing into the market.

Gold appears to be in a holding pattern right now. As commodity prices have dropped, the need for inflation protection has also dropped. However, there is still a fair amount of economic uncertainty, putting a bud under prices.

A Note on Home Prices


Click on the above chart for a larger version.

The above is from the latest Case Shiller home price index. Notice the area in the black square. Note particularly that is has been around this level for the last two years or so. Finally, notice that prices have been in a fairly tight range for this period.

There's been an awful lot of talk/hype/pixels spilled lately regarding home prices. The above chart tells us that home prices have been fairly stable for the last two years. In fact, as NDD has pointed out, home prices may be far closer to stabilizing than previous thought.

Commodity prices and pre-WW2 recessions

- by New Deal democrat

In the last week I have been looking at some economic data series that go back to at least the 1920s to determine which might serve as leading indicators of deflationary busts. Previously I have looked at BAA corporate bonds and housing starts.

Now let's look at commodity prices. These have been kept since 1913. Some sort of commodity index is thought to be an element of ECRI's growth index. Similarly, frequently you will read Bonddad and others making reference to "Dr. Copper," the idea that the use of that industrial metal is a good guide to the health of the economy overall.

Wholesale commodity prices have a somewhat spotty record. First, let's take a look at the pre-WW2 recessions:


While it's true that YoY commodity prices went negative before the 1927 and Great Depressions, they were coincident indicators for 1923 and 1938. Further, they gave a false signal in 1936.

Here is the same series from 1998 to the present:


While wholesale commodity prices plunged during recessions, they gave scant notice of the dot-com recession, and continued rising ($147 Oil!) 7 months into the "Great Recession."

I suspect there is a more complex relationship at play. Inflationary recessions are in part caused when commodity prices rise much faster than consumer prices (meaning producers cannot pass on costs and profit margins are squeezed), which explains the 1923 recession (commodity prices rose 10% while consumer prices barely rose at all) and the energy shock portion of the "great recession." To the contrary, commodity weakness in the face of deflation in consumer prices as well may be a signal of an oncoming deflationary bust (1927, 1929, and thereby excluding 1936). If there is a reliable signal, it is more complex than simply a rise or fall in commodity prices.

PCEs Down .1%

From the WSJ:Link
Consumer spending, a key driver of economic growth, was flat in May, the Commerce Department said Monday. Incomes rose 0.3%, providing some hope that spending could pick again later in the year.

Economists surveyed by Dow Jones Newswires were expecting spending to rise by 0.1% and income to register a 0.4% gain.

For April, spending was revised down to 0.3% from an initial estimate of 0.4%, with incomes also changed to 0.3% from 0.4%.

May's weak spending levels give further evidence that the recovery has slowed during the first half of the year, as a rebound in the unemployment rate combined with higher gasoline and food prices have caused consumers to tighten their belts.

Monday's report showed that when adjusted for inflation, spending actually went down 0.1% in May.

Let's take a look at the data:

Real PCEs have now moved lower for the last two months.

Services -- which comprise 65% of PCEs -- rose law month. Also note the overall trend of these purchases is increasing.


Non-durable goods comprise about 22% if PCEs. Notice this indicator has been more or less flat for the last four months.


Durable goods expenditures -- although comprising the smallest part of PCEs are by far the worst performing segment, falling the last three months.

The above charts indicate that consumers are feeling a pinch from several places: high gas prices (which are lowering car expenditures and thereby durable goods) and still high unemployment. As a result, they are pulling back on spending. As this accounts for 70% of overall economic growth, this is a bad development.

Monetary Velocity Indicates Slowing Economy

While it's important for the Federal Reserve to increase money supply during a recession to give the spending public more money for purchases, it's also important for the pace of purchases to increase, indicating more and more people are conducting purchases at a faster pace. This is called monetary velocity, and it's a very important statistic. Although not a perfect predictor, there is a strong relationship between the percentage change from last year in various monetary velocity indicators and GDP growth (this is something I researched a few months ago).

Consider these charts:


All of the above charts show that the pace of YOY percentage change in monetary velocity has dropped and has taken GDP growth with it.

In short, the pace of money moving through the economy is decreasing, indicating a slowing down of overall economic activity.

Monday, June 27, 2011

Treasury Tuesdays

Last week, I wrote the following about the Treasury market:
While I'm not seeing anything to indicate a mass exodus from with security, I do think the rally is over for now. I'd take profits if you haven't already.
My concern for the rally was based on two things. First, the MACDs of both the IEF and TLTs were giving sell signals. In addition, the charts of both were starting to break down. The IEFS had dipped below support followed by a subsequent rally and the TLTs had broken their uptrend and were moving sideways.

Over the last week, the Treasury market has continued to benefit from Greece fallout and concern over the US economy.


On the daily chart, notice the IEFs are still in an upward rally and have broken through resistance to make a further advance. All of the EMAs are bullishly aligned -- all are moving higher, and shorter are above the longer and prices are using the EMAs for technical support. Also note the slight uptick in volume for the last few weeks, possibly indicating a buying climax.


Notice that the A/D line -- after making a strong advance, hasn't increased for a few weeks. This lack of volume is confirmed by the CMF. The MACD indicates momentum is decreasing.


The long end of the yield curve is still moving sideways and has again broken below the EMAs. Yesterday's price action was also a big move lower. Note the underlying technicals are giving way to bearish developments. The A/D line tells us new money is not flowing into the market. The CMF is moving lower as well, and the MACD shows a distinct lack of momentum.

The fact that the long end of the curve didn't follow the belly higher is interesting. That and the continued deterioration in the TLT's technicals tells me the long end of the curve is selling off -- or at least holding even for awhile. I'm not convinced the IEFs are going to maintain a strong rally here, largely because the long-end of the curve is not following through. As such, I don't see the IEFs current move higher continuing. That would analysis would change if the TLTs break higher to new levels.

Housing starts as a Pre-WW2 leading indicator

- by New Deal democrat

This is another post concerning leading indicators from before the inflationary era. Previously we saw that BAA corporate bond rates were one such indicator. Now let's look at housing starts.

Unfortunately the only data for housing starts before WW2 comes from the Statistical Abstract of the United States, and is annual. While that limits our ability to judge its effectiveness somewhat, the good news in that regard is that, as Professor Edward Leamer has shown, post-WW2 housing starts typically haven't had their maximum impact on the economy until a year or even 6 quarters out. Thus if we see that housing starts peak the year before a recession, and bottom the year before a recession ends, that is strong supportive evidence that Leamer's theory holds for the pre-WW2 era of deflationary busts.

It is also good to keep in mind that the 1920's housing boom was every bit the equal in population-adjusted terms as the boom of the first part of the last decade.

So here is the data (in 100's):

YearNonfarm housing startsRecession dates
1919 315 -
1920 247 1/20-
1921 449 - 7/21
1922 716 -
1923 371 5/23-
1924 893 -7/24
1925 937 -
1926849 10/26-
1927 810 -11/27
1928 753 -
1929 509 8/29-
1930 330 cont.
1931 254 cont.
1932 134 cont.
193393 -3/33
1934 126 -
1935 221 -
1936 319 -
1937 336 5/37-
1938 406 -6/38
1939 515 -
1940 602 -


Sure enough, while the data isn't perfect, housing starts generally peaked the year before the recession began, and bottomed the year before it ended. As to the 1927-28 recession, note that housing starts declined -88k in 1926, - 39k in 1927, and -57k in 1928, which on a second derivative basis conforms to the hypothesis. Similarly, while the 1937-38 recession took up almost half of each of 2 years, it is impossible to know if the hypothesis works, after increasing 98k in 1936, they only increased 17k in 1937 before accelerating by 70k in 1938, which likewise on a second derivative basis conforms to the hypothesis.

Note also that like our era, the 1920s housing bubble popped several years before the severe economy-wide downturn kicked in.

In other words, while the fact that the data is annual rather than monthly limits our ability to test it somewhat, there is strong evidence that housing starts are an equally valid leading indicator in eras of deflationary busts, as well as the post-WW2 inflationary era.

The Washington Uncertainty Situation

Consider this fact pattern: you are currently a business owner thinking about either hiring someone or taking out a loan. As part of this process, you think about political events over the next few months and see the following:

1.) Washington allows the debt ceiling debate to expire. As a result, US Treasuries sell-off, yields spike and the entire yield curve is thrown off. This of course increases the cost of your capital and makes the possibility of closing a loan nearly impossible. If you are looking at hiring a new person, you see this scenario as one that halts any forward economic momentum, meaning an already weak aggregate demand situation becomes weaker, making hiring someone a low priority.

2.) Washington solves the debate issue. In doing so they negotiate huge spending cuts. This lowers GDP growth (remember, government spending is a variable in the GDP equation). As such, this deal also hurts your company in the medium term, thereby lowering the possibility of taking out a loan or hiring somebody.

Here's the point of the above scenario: no matter what Washington does right now, all possible, publicly floated program options will lower overall growth. That means Washington is clearly a problem, creating a large amount of macro-level uncertainty that is in turn freezing action.

Sunday, June 26, 2011

Equity Week in Review and Preview of the Upcoming Week/Month

Last week, I wrote the following about the market:
The IWMS and QQQs are both down ~ 9.5% from their peaks, while the SPYs are down ~ 7.25%, meaning the sell-offs are still in standard correction territory. This week, the most important developments will occur regarding the 200 day EMAs. The QQQs have already moved through this key technical area, while the IWMs and SPYs are holding their ground. If we see the IWMs and SPYs break this important level, the sell-off could get much worse.
There are two issues for the financial markets right now. First, for the last month the pace of economic deceleration in the US has led to concerns about the long-term implications for the recovery. Secondly, there is the issue of Greece; last week, the EU went through another white knuckle round of measures related to the Greek fall-out. Both of these events have led to bearish sentiment and market action over the last two months.


The chart above of the 5-minute/10 day price action shows that most of the action occurred in a very narrow price range. While prices twice attempted to move higher, they were unable to maintain upward momentum, and returned to their previous trading range.


The daily chart shows that prices are wedded to the 200 day EMA. The 20 and 50 day EMAs are both heading lower, but the 10 day EMA is now moving sideways. Also notice the slight uptick in volume over the last week and a half. While not significant enough to indicate a selling climax, it could indicate a price pause at the 200 day EMA level.


The technical indicators show that inflowing money more or less stalled in March. While we saw a slight uptick in May, it was hardly enough to justify a strong upward move. The CMF confirms this view, while the MACD indicates that momentum has been declining over the same period. Overall, this chart has strong bearish implications.


While the QQQQs dropped below the 200 day EMA, they are now about the 200 day EMA.


The IWMs have bounced off the 200 day EMA and are now entwined with the 10 and 20 day EMAs.

Right now, the 200 day EMAs are providing enough technical support to allow the markets to "catch their breath" from the recent sell-off. Traders have understandable concerns about the pace of recovery and the Greek debt situation. However, the disciplined pace of the sell-off and the stalling of the descent at the 200 day EMA indicate there is enough bullish sentiment to give the market pause -- at least for now.

However, a strong, multiple market break (involving 2 of the 3 major averages) below the 200 day EMA would be a watershed moment for this market. Should that happen, I would wait for a rebound into an EMA and then short.