Tuesday, November 6, 2007

A Look At Oil, the Energy ETF and It's Largest Holdings

Energy is the best performing sector of the last year and since the beginning of the year. According to stockcharts.com perf function, the energy ETF is up 37.32% over the last year and 29.71 year to date (as of Sunday). So let's take a look at a chart of oil, the XLE ETF, and some of the largest holdings in the ETF.


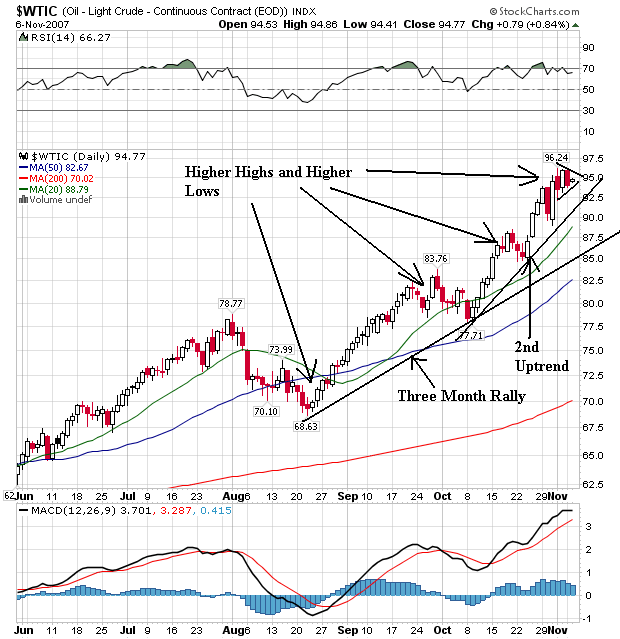
Oil's daily chart is strong. It is in the middle of a three month rally which has a consistent pattern of higher highs and lower lows. Prices have continually moved through previous levels. There are two trend lines in place. All of the simple moving averages (SMAs) are moving higher, the shorter SMAs are above the longer SMAs and prices are above all the SMAs. This is a great example of a bull chart.
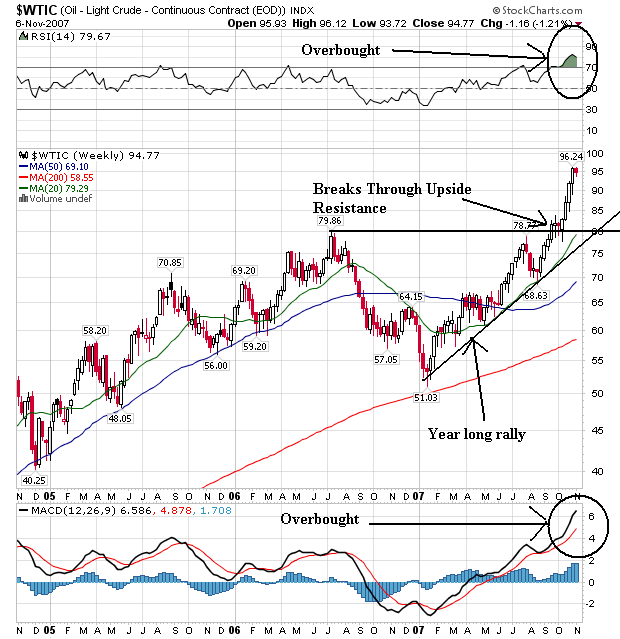


The weekly chart shows an uptrend that started at the beginning of the year. It also shows prices moved through the July 2006 level, consolidated just above that level and then continued higher. The main drawback to this chart is the overbought reading on the RSI and MACD. However, these do not completely determine market direction; these readings could stay pegged for some time.

So -- the underlying commodity of this sector is in a very clear bull market. Let's see what the ETF looks like.
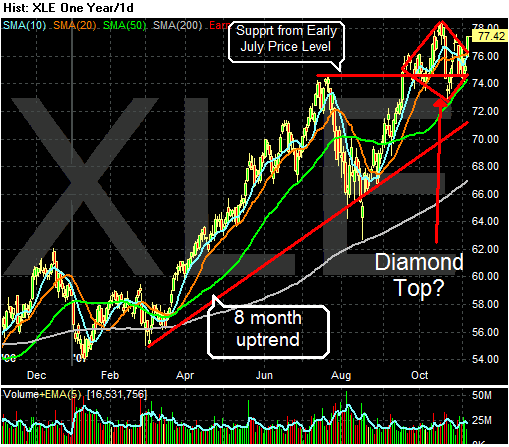


The ETF is in the middle of an 8-month uptrend. Current prices are receiving strong support from the mid-July high. A diamond top may be forming, but prices also broke out from that pattern yesterday thanks to oil's record close. The 50 and 200 SMAs are both moving higher, but the shorter SMAs are a bit bunched up indicating a lack of direction. Yesterday's price break out is a good start, but prices need to move above the mid-October high to indicate a new uptrend is in place.

According to Yahoo finance, the largest stocks in the sector are Exxon, Chevron, Schlumberger, Occidental Petroleum and Conoco Phillips. We'll take them in order of largest percentage of the index to the smallest.
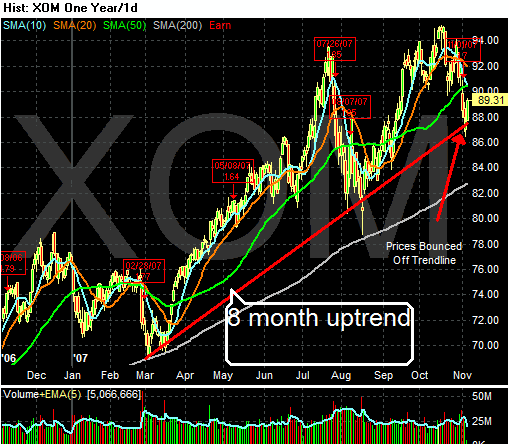


Exxon is in the middle of an 8-month long rally. It has bounced off the trend line twice. Yesterday's bounce printed a very strong bar. The bearish side of the chart notices the 10 and 20 day SMA moving lower with the 10 day about to cross the 50 day SMA. However, the strength of yesterday's bar along with the oil market's rally provide a strong reason for this bounce to continue.
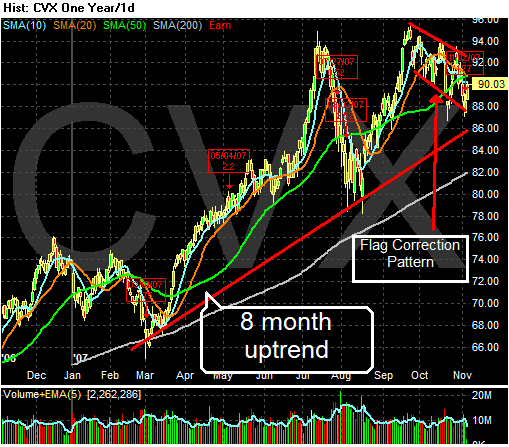


Chevron is in the middle of an 8 month rally, but is also in the middle of a month-and-a-half long flag correction. The shorter SMAs are headed lower and the chart may have printed a double top with the first top in early July and the second in late September. However, the stock hasn't moved out of the flag pattern, indicating it may simply be going through a standard correction before it moves higher.
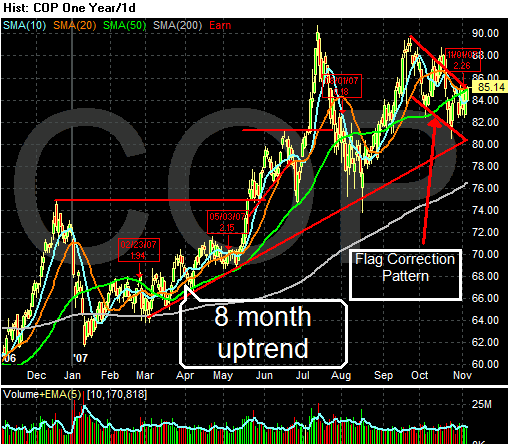


Conoco Phillips chart mirrors Chevron's in many ways. The main difference is prices are at the top of its respective flag pattern. Should they move through resistance this stock could be looking at a 3-5 point move.
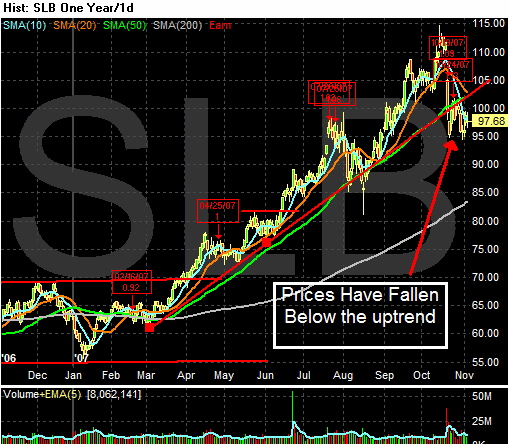


Schlumberger is the only bad stock in the bunch. It has broken through its 8 month long uptrend indicating a clear change of direction. Although prices are consolidating right below the trend line, the shorter term SMAs are both headed lower indicating the short-term trend is down.
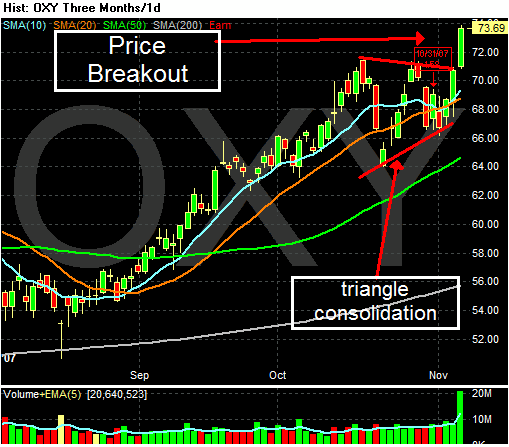


Occidental Petroleum printed a month long triangle consolidation and is now breaking out of that pattern on strong volume. Here is the year long chart
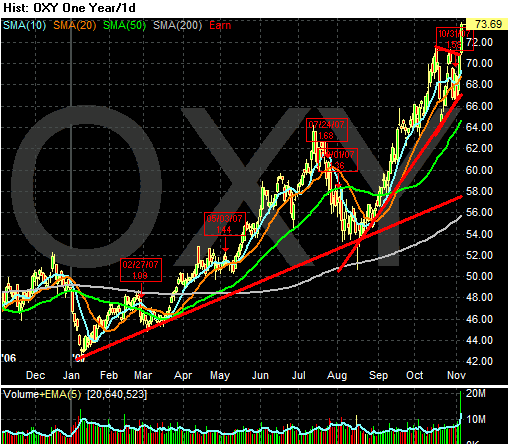


Which shows a definite uptrend in place.

Retail Is "Just Wrong"

From CNBC:

With retail stocks down 11% year to date, you would think some would be out looking to call a bottom, but bearishness remains very high among retail analysts. Morgan Stanley very typical of that mood this morning, was out with a long note on retailers called "Not Too Hot, Not Too Cold, Just Wrong."


Here's a chart from CBS.Marketwatch of the S&P retail sector:


When sectors break through three year support, you know there's trouble out there.

Today's Markets


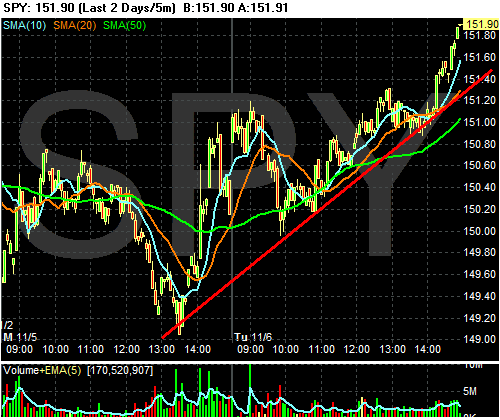
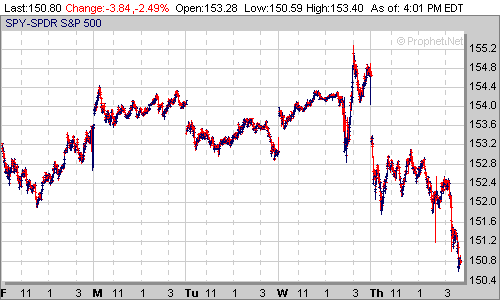
As the two day chart shows, the SPYs are rallying upwards. The markets got a jolt yesterday around the 149 level with heavy volume buying. My guess is 149 was an important level for some computer programs.


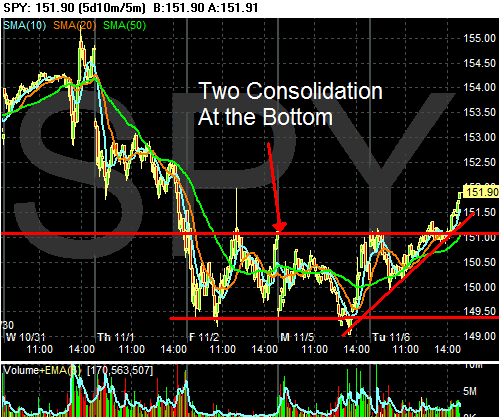
The 5-day chart shows a two day consolidation between the 149.40 and about 151. We also see the market's broke out of this range at 2PM CST today on good volume.


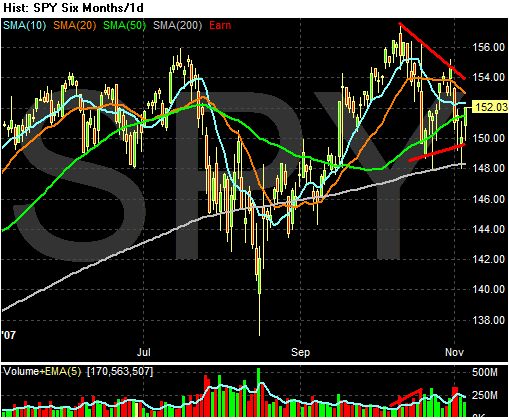
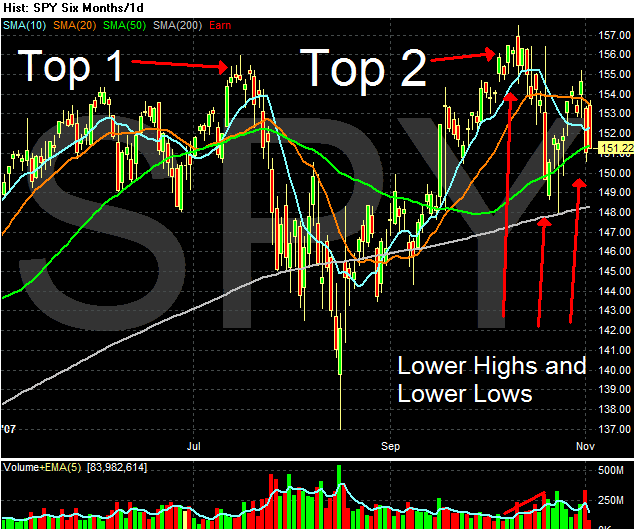
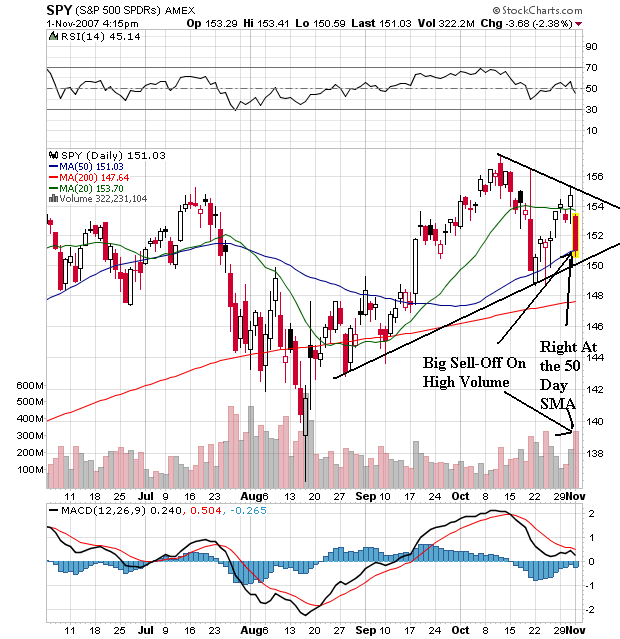
The six month daily chart shows some interesting points. First, we have a possible double top, with the first top occurring in early July and the second occurring in early October. These levels are near record highs for the S&P which have provided top side resistance for the last four months. As I mentioned in this post over the weekend it's looking like that area will provide stiff upside resistance.

In addition, we may have a triangle consolidation pattern forming over the last few weeks. This would make sense given the overall uncertainty of the financial markets right now. While the last Fed statement alluded they would not lower interest rates again, the recent news from the financial sector may still fuel the bull's hopes. This would give the market some upside pressure. However, record high oil prices along with concern about Christmas will give the bears ample ammunition. In other words, there are still decent arguments from both sides of the street, putting the market squarely in a trading/consolidation range.


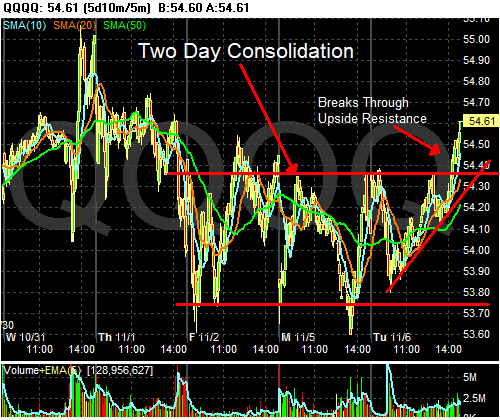
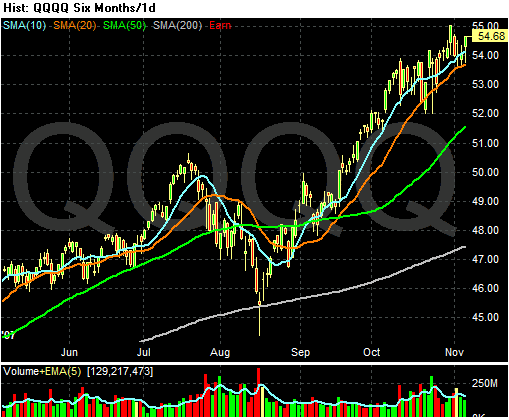
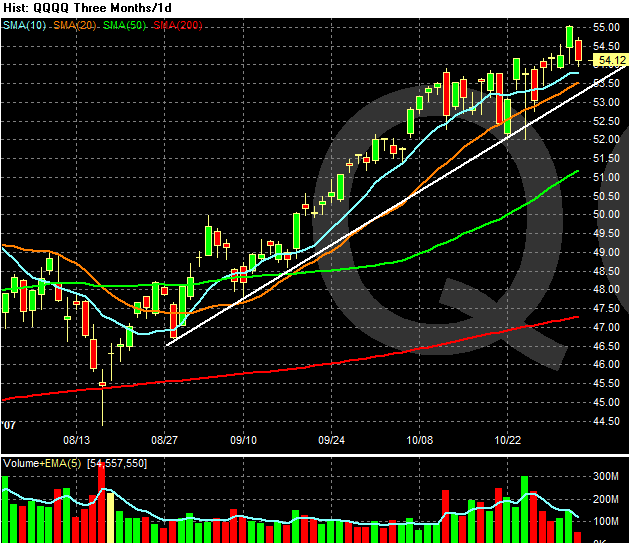
Like the SPYs, the QQQQs show a two day consolidation pattern and a break through upside resistance in today's session.


However, the QQQQs daily chart shows a rally still in place. The simple moving averages (SMAs) are all heading higher, the shorter SMAs are above the longer SMAs and prices are still above all the SMAs.

Aren't You Glad Food and Energy Costs Aren't Important?

From CNBC:

Some retailers have already lowered their October forecast. Target Corp. reduced same-store sales guidance mid-month, for the second month in a row, citing "greater-than-normal daily volatility and continued disappointing sales results."

......

Meanwhile, specialty retailers are facing declining mall traffic as consumers curb discretionary spending due to high gas and food prices and other economic concerns.

.....

"Mall traffic continues to be down, making it even more important to convert the customers who do walk through the doors," wrote Buckingham Research Group analyst John Zolidis in a client note on Monday.


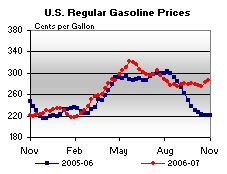
This chart from This Week in Petroleum doesn't mean anything and has no effect on anything.

What Inflation?

From the WSJ:

With the price of crude oil hovering above $90 a barrel, airlines are accelerating efforts to raise ticket prices to help offset the higher cost of fuel.

.....

AMR Corp.'s American Airlines, the world's largest carrier by traffic, succeeded in pushing through an unusually large fare increase announced Thursday. That increase of $20 on round-trip domestic fares was double the typical boosts made by American and many of its competitors.

Those airlines matched American's increase over the weekend.

.....

"Given surging crude prices, fare increases are occurring at a stepped up pace," said J.P. Morgan airline analyst Jamie Baker, who said he has also witnessed stepped up efforts from smaller airlines, including AirTran Holdings Inc. and JetBlue Airways Corp. in the past week.

.....

The price of refined jet fuel has risen more than 40% since January. That has put increasing pressure on an airline industry that just returned to profitability last year. Airlines have slashed their costs sufficiently to remain profitable this year. They have also curbed growth, which has helped the industry boost fares more successfully.


Don't look any further at this post, because there isn't a chart of oil that shows a near record price. In fact -- the chart that follows (which isn't important because it's not a core price) won't show you anything you need to know. Just go to another website, OK?


Great -- now you've looked at oil prices and have seen they are rising fast. But they're not part of core inflation, so just try to forget about this information, OK?

Citigroup's Problems Continue; Start to Infect the Whole Sector

From the WSJ:

One day after the departure of Chief Executive Charles Prince, Citigroup Inc. officials said it will take the bank until the middle of next year to clean up its problems caused by credit-market turmoil.


Let's stop right there are acknowledge the obvious. Citigroup is publicly stating the turmoil in the financial sector is not a one-time event, but instead the beginning of a rather long process that will take at least until the end of June 2008 -- 8 months from now. That makes a hell of a lot more sense given that no one really knows how much further damage is possible. Anyone who says this is a one time event or this won't cause damage beyond the end of the year is lying through their teeth.

Citigroup's new woes underscored for many investors that the fallout from credit-market turmoil will likely continue for longer than many expected. Counting Citigroup's potential new losses, banks and investment houses will have racked up combined losses of more than $30 billion because of mortgage- and debt-market problems [in the latest quarter]. Many worry that Citigroup's predicament is a signal that more losses could be in store for other financial players.


The third quarter has demonstrated two very important points. First, the problem is widespread. I can't think of a major financial player who hasn't announced some type of portfolio writedown this quarter. Secondly, the problem is big. So far this quarter we've seen $30 billion in writedowns. That's a significant amount of capital that is vanishing into thin air. And Citi's tacit acknowledgment that further writedowns are possible indicates this won't be the last time we see the phrase "writedown" in a financial company's earnings release.

The magnitude of Citi's writedowns are starting to negatively impact trader's and analyst's perception of the sector:

For followers of banking stocks, the scary part isn't that Citigroup (C) might write down as much as $11 billion in subprime mortgage losses this quarter.

The scary part is that Citi and other leading banks might still be lowballing their losses in hopes that things won't get any worse.

Citi on Sunday said it expects to write down $8 billion to $11 billion before taxes for its $55 billion of exposure to U.S. subprime mortgages.

Last quarter, the banking giant swallowed $6.5 billion related to subprime mortgages, loan losses and other debt. Those losses trimmed its third-quarter profit by 3 cents a share.

Sunday's announcement came less than a month after Citigroup told investors it had a "good, sustainable strategic plan" for managing the subprime mess.

Boasts like that might have calmed some nerves during the early stages of the subprime crisis. But with the bad news continuing to repeat itself, Wall Street is having a harder time seeing the glass as half full.

Skepticism is so high that many analysts are already questioning whether Citigroup went far enough with its latest write-down.

"Maybe they could have taken off $10 billion to $15 billion," said Kris Niswander, senior banking analyst at SNL Financial. "Whether or not that was aggressive enough is yet to be seen."


(Back to the WSJ article)

Chief Financial Officer Gary Crittenden, on a conference call with analysts yesterday, acknowledged that the $8 billion to $11 billion in losses flagged by the bank are an estimate of write-downs that may be needed. The bank "can't give any assurance" that the loss won't grow as the quarter progresses, he added.


Further writedowns should surprise no one at this point given the breadth and depth of the problems we've seen so far. But public acknowledgment of the problem is important.

Citigroup is getting hammered right now because it is one of the largest financial firms in the world. But it is hardly alone right now -- every major financial player is going though similar problems. Note the following action on Monday:

Fitch Ratings on Monday called into question the capital reserves at financial guarantors such as Ambac (ABK - Cramer's Take - Stockpickr - Rating), MBIA (MBI - Cramer's Take - Stockpickr - Rating) and Security Capital Assurance (SCA - Cramer's Take - Stockpickr - Rating), along with closely held Financial Guaranty Insurance and CIFG Guaranty.

Fitch's review is due to take four to six weeks. If it cascades into full blown ratings downgrades, it could create another wave of forced selling in the credit markets -- this time in the $14 trillion municipal bond market.

"It's starting to feel a lot like summer," says Sid Bakst, senior portfolio manager at Weiss Peck & Greer Investments, and he's not referring to the weather.


Short version: this ain't over by a long shot.

Monday, November 5, 2007

Deparment Stores Have Been Naughty

With the Christmas season fast approaching, it's time to start looking at retailers. Traders aren't very happy about big department store prospects.

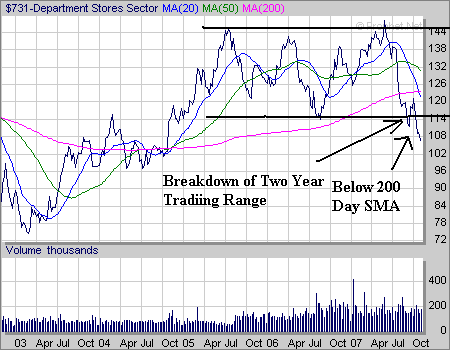
First, here is a chart from Prophet.net of the department store sector.


There are several significant points to make about this 5-year chart.

1.) Most importantly, the index broke a two year long trading range.

2.) The index is trading below all of its SMAs.

3.) The index is below the 200 day SMA, indicating bear market territory.

4.) The 20 and 50 day SMAs are both headed lower.

All in all, this chart says "sell me....now."

According to Yahoo finance the five largest stocks in this index by market cap are Sears Holdings, Kohls, Macy's TJ Maxx and J.C. Penney. Let's see how those individual charts look.


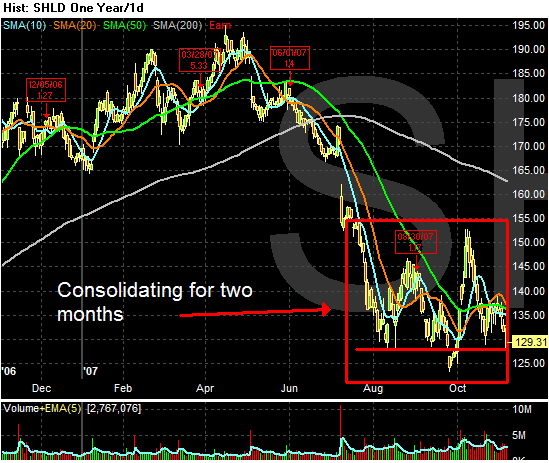
Sears is below the 200 day SMA. It dropped hard with the summer's sell-off and has yet to rally convincingly from that sell-off. Right now it's consolidating. The 10, 20 and 50 day SMAs are all bunched together indicating there is no clear short-term trend in place. But a move below 125 would indicate further selling is underway.


Like Sears, Kohls sold-off during the summer. But this stock has fallen through technical support on strong volume. In addition, the 10, 20 and 50 day SMAs are all heading lower indicating the short-term trend is down. Finally, the stock is convincingly below the 200 day SMA, indicating its already in bear market territory.


Macy's chart resembles Sear's. It sold-off in the summer, but is currently consolidating in a triangle consolidation pattern. Finally, it too is in bear market territory.


TJ Max is hugging its upward trend line like nobody's business. Today it moved though support. In addition, the stock has moved below the 200 day SMA, but it has been flirting with this line since April. In addition, the 10, 20 and 50 day SMAs are all heading lower. This chart stinks -- and it is the best one of the lot.


JC Penney is below the 200 day SMA, the 10, 20 and 50 day SMAs are all headed lower (as is the 200 day SMA), the shorter SMAs are below the longer SMAs and prices are below all the SMAs. This chart says sell me -- NOW.

It looks like the big department stores were definitely naughty this year.

Like Lemmings Off a Cliff....

From Bloomberg (note these two paragraphs are in the same story...)

U.S. stocks pared losses as CNBC reported that Goldman Sachs Group Inc. denied a rumor of a writedown.

.....

Lehman Brothers Holdings Inc. said today it expects banks to suffer $200 billion to $250 billion of combined losses on mortgage portfolios over the next five years and $50 billion next year. Fitch Ratings downgraded Citigroup's debt to AA, with a negative outlook.


I'm not saying that I have any knowledge that Goldman will write anything down. But everybody has written something down over the last month. This reminds me of Countrywide saying its latest results were the low point of the cycle on the same say they announced massive write downs, job cuts, an increasing loan loss reserve and a loss for the quarter. Of course, Countrywide rallied that day......

Today's Markets


The markets opened lower and then traded in an inverted saucer pattern until they got to about 149. Then the volume really picked up which is usually an indication of serious program trading activity. The markets couldn't hold the upward momentum and sold-off a few minutes before the close.


The 5-day chart shows consolidation over the last few days with today's late action breaking the downward trendline.


The daily chart shows the price action below the 10, 20 and 50 day SMAs along with some heavy volume over the last few trading sessions. As the VIX chart below and long candles of the last few days show, volatility has been creeping up over the last few sessions.


The QQQQs have more support for their current market position. That's the good news.


The bad news is although the QQQQs are holding to their short-term averages....


The NASDAQ advance/decline line is breaking down


As is the QQQQs new highs/new lows line.

The market internals for the NASDAQ -- which is the market's great hope right now -- are not looking good at all. Fewer and fewer stocks are contributing to the rally.

Financials Look Terrible


The financial sector looks terrible. Note the following very bearish conditions on the chart.

1.) Prices are below the 200 day SMA and have been there awhile.

2.) The shorter SMAs are below the longer SMAs -- another very bearish signal.

3.) Prices are below the SMAs, which will pull them lower over the short term as well.

4.) In early October the index rallied to the 200 day SMA but couldn't get higher. That means there wasn't enough enthusiasm for the sector to take it out of bear market territory.

This is a chart that should concern everybody.

Sunday, November 4, 2007

What Inflation?

According to the Federal Reserve, the only inflation rate that matters is "core" inflation. This is the inflation rate less food and energy prices. The underlying reasoning of this position is because commodities' prices seasonally fluctuate, their impact isn't that pronounced unless the price increase bleed through to core inflation -- inflation less food and energy.

In a world where commodities' prices are seasonal -- that is they rise and fall in predictable patterns -- this way of looking at inflation makes sense. But in a word where commodity prices continually increase on a multi-year basis, this policy of focusing solely on core inflation ranks up there with "we can win a land war in Asia" as one of the dumbest ideas around.

As the following smattering of news stories indicate, commodity price increases are not an ivory tower theoretical issue; they are starting to hit businesses in practical, day-to-day ways.

From the BLS' latest inflation report:

The index for energy, which advanced at annual rates of 22.9 and 32.9 percent in the first two quarters, declined at a 14.8 percent rate in the third quarter of 2007. Thus far this year, energy costs have risen at an 11.7 percent SAAR after increasing 2.9 percent in all of 2006. In the first nine months of 2007, petroleum-based energy costs (energy commodities) advanced at a 20.6 percent rate and charges for energy services (gas and electricity) increased at a 1.3 percent rate. The food index rose at a 5.7 percent SAAR in the first nine months of 2007 after advancing 2.1 percent in all of 2006. Grocery store food prices increased at a 6.7 percent annual rate in the first nine months of 2007, reflecting acceleration over the last year in each of the six major groups. These increases ranged from annual rates of 4.0 percent in the index for other food at home to 17.7 percent in the index for dairy products.


From Forbes:

Oil prices affect every corner of the market, even the most quotidian ones. And with oil at $96 a barrel one unobtrusive sector suffering is containers and packaging.

Packagers are heavy consumers of petrochemicals, which are basically plastic. So the higher the oil price, the higher plastic resin prices are. So packagers that use plastic resin have been hit hard.


From the Motley Fool:

But in Kraft's case, the top-line "momentum" didn't trickle down to the bottom line. Earnings per share on a reported basis were $0.38, a decline of 15.6% from the prior year. Excluding unusual items, the picture looks somewhat better -- $0.44, or a decline of 4.3%. The one scrap of good news in these lower earnings: The company did beat consensus analyst estimates by $0.02 per share, which propelled the stock higher shortly after the release.

The earnings culprit is "higher input costs," meaning that dairy raw material costs rose more quickly than the company could hike its prices to compensate. For example, raw material costs to make cheese, a key product for Kraft, have skyrocketed 40%.


From CNBC:

Consumer products maker Procter & Gamble Co. said Tuesday its first-quarter profit rose 14 percent, but said rising commodity, energy and product investment costs will hurt its second-quarter margins.


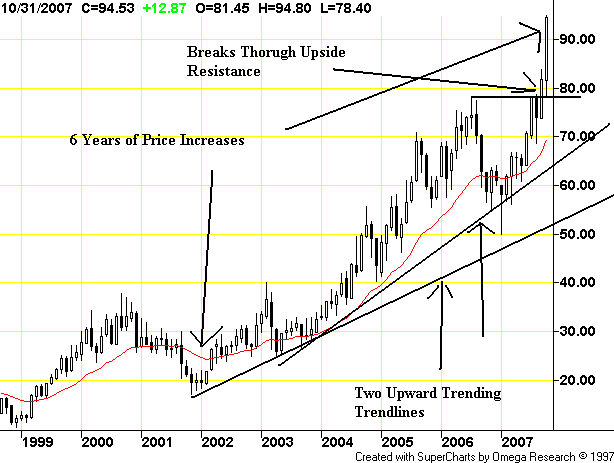
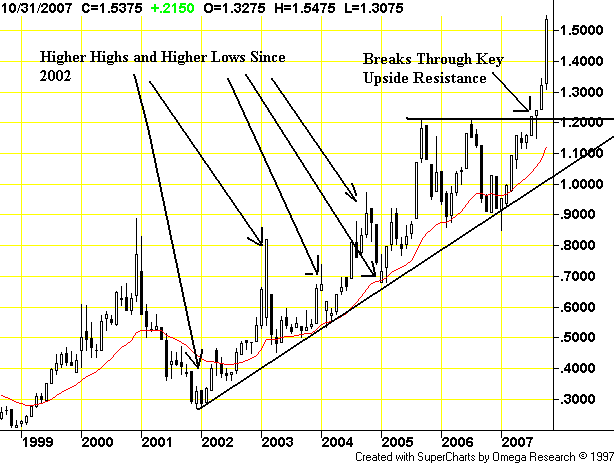
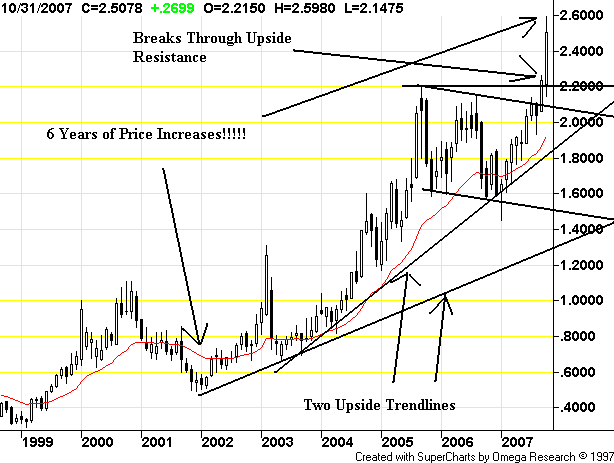
And as the charts below show, price increases caused by commodity inflation are hear to stay.

Wheat:


Soybeans


Oats


Corn


Oil


Propane


Heating Oil


Thank God none of these multi-year price increases have anything to do with inflation. Then we'd really be in trouble.

Citigroup To Write Down $6 - $10 Billion

From CNBC

Citigroup faces a write-down in the range of $6 billion to $10 billion, mainly because of exposure to subprime mortgages and collateralized debt obligations, CNBC has learned.

Citigroup will be parting ways with CEO Charles Prince, according to sources.

Citi Chief Executive Officer Charles Prince has already offered to resign from his post, according to a person familiar with the situation, and the financial services company's board is expected to accept his resignation at an emergency meeting scheduled for Sunday.

The size of Citi's write-off is still being debated, though a source told CNBC that Citi's board is pressing company finance executives to clarify the issue. The firm's audit committee is also scheduled to meet Sunday, in advance of the emergency board meeting.


This should not surprise anyone. Financial firms are writing off tons of debt right now. Citigroup is one of the largest financial firms in the country and they are involved in just about everything.

Prince will be Citi's sacrificial lamb. Considering the breadth of the street's exposure to these items, blaming Prince is a pretty stupid idea. I'm sure everyone thought he was a genius when he thought Citi should invest in CDOs etc...

The article goes on to note that some analysts are forecasting broad writedowns across the industry, with Merrill, Bank of America, Wachovia and Morgan Stanley specifically named.

Friday, November 2, 2007

Two Charts of the SPYs That Should Cause Some Concern


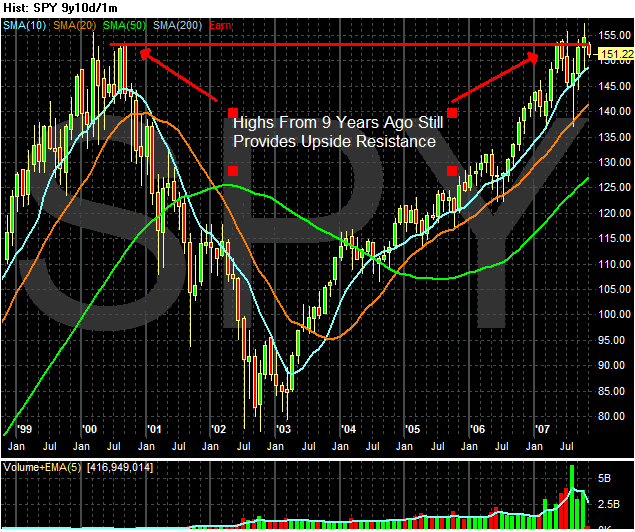
This is a 9-year chart of the SPYs. Traders have many adages. One of them is, "markets have memories." What this means is previous price levels are important. The above chart illustrates this point. Notice that a high achieved nine years ago is providing a ton of upside resistance for the SPYs now. Remember that chart, and then look at this one:


This is chart that shows a double top formation that occurred right around the previous highs. The markets tried to get through previous levels twice and couldn't make it. Now the markets are selling off in what is starting to look like a downward pattern of lower highs and lower lows. We don't know if that is how this will play out, but there are some strong bearish currents in the market right now. The financial sector (which comprises 20% of the S&P 500) is under extreme pressure thanks to subprime mortgage exposure. The energy sector -- which is one of the top performing sectors of the last year -- is taking earnings hits this quarter. Exxon and Chevron both reported sub par earnings.

The point is there are plenty of reasons for the market to move lower right now.

More on the Markets Tomorrow

I just got back in town and I'm beat. I'll post on the markets tomorrow morning.

Everybody relax and have a good Friday night.

Jobs Up +166,000

From the BLS:

Total nonfarm payroll employment rose by 166,000 in October to 138.4 million, following increases of 93,000 in August and 96,000 in September. In October, job growth continued in several service-providing industries, while employment in manufacturing continued to trend downward. Construction employment was little changed over the month.


Let's go back to the latest GDP report which had growth at 3.9% with an unbelievably low inflation level (.8%). Now, lets' approach the employment report from two angles.

1.) Let's assume the GDP report was correct and the inflation number was accurate. Then this number makes sense. With an economy growing at 3.9% you're going to see more job growth. It's that simple.

2.) Let's assume the GDP report was too high, largely because the inflation number was too low. Then this report is bit harder to swallow but it doesn't strain credulity. Let's assume that inflation is restated and takes the GDP report down to 2.5% -- which is a pretty large whack. Even at 2.6%, 166,000 isn't that hard to believe. While 2.5% isn't great, it's still growth and that means businesses will need more people to do stuff. In addition, employment figures have been low for the last three months indicating businesses may have been holding off on hiring and now have to hire because they have their "backs to the wall" as it were.

In short, given the latest GDP number this report isn't out of line with the current environment.

A Look at Financial Sector Charts


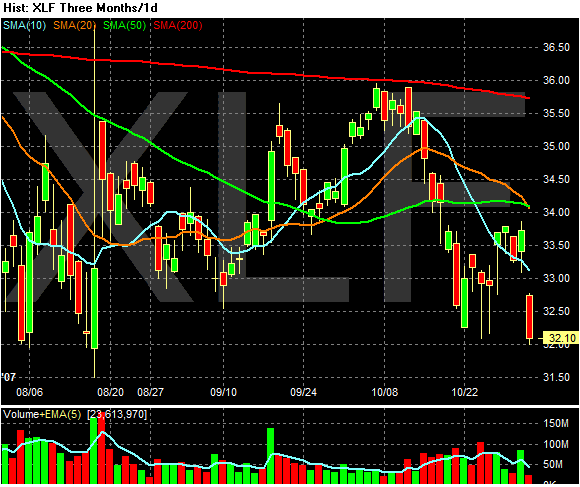
This is the three month chart of the XLF -- an ETF that tracks the largest financial sector stocks. Notice the following.

1.) The ETF is below the 200 day SMA and has been for the last three months. This is bear market territory.

2.) With the 20 day SMA crossing the 50 day SMA yesterday we now have a very bearish moving average picture. The shorter SMAs are below the longer SMAs and prices are below all the SMAs. In addition, all of the shorter SMAs are all heading lower. Add all of these elements together and you get a very negative reading for the financials market.


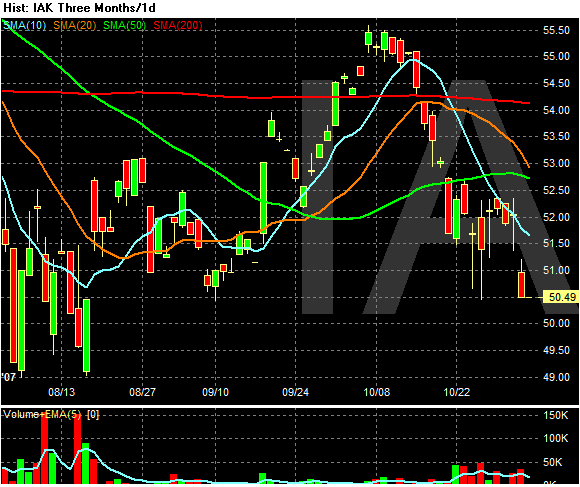
In insurers ETF is also incredibly negative.

1.) The 10 and 20 day SMAs are both heading lower.

2.) The 20 day SMA is about to cross the 50 day SMA.

3.) The index is below the 200 day SMA.

4.) Prices are below the SMAs and prices have been unable to get above the 10 day SMA over the last few weeks.

5.) Starting at the end of October we have a pick-up in volume. That indicates selling pressure is increasing.


The Broker/Dealers is in a bit better shape.

The 10, 20 and 200 day SMA are bunched up. This indicates a lack of direction from either side of the market. While prices are below the 20 day SMA, they're trading around the index and have for the last month or so. This isn't so bad.

However on the negative side we may have the beginning of a classic downward shifting market making lower highs and lower lows. The key to this possibility is is this leg gets below $49.74 or so.

About That Citigroup Writedown and the Financials

Citigroup (NYSE:C - News) may have to cut its dividend to lift its capital levels, said CIBC World Markets. Morgan Stanley and Credit Suisse also downgraded the financial giant.

...

Stocks dived on the day's news. The Nasdaq fell 2.2%, while the S&P 500 and Dow slid 2.6%. The small-cap S&P 600 plunged 4.1%.

Banks led the way, with the SPDR financial ETF crashing 5%. Citigroup fell 7% to a 41/2-year low.

Credit Suisse (NYSE:CS - News) fell 5% after saying third-quarter profit fell 31%. It wrote down $1.9 billion in mortgage and leveraged loan losses.

Bond and mortgage insurers such as MBIA (NYSE:MBI - News) and Ambac (NYSE:ABK - News) dived on worries that subprime defaults will keep soaring. Insurance giant AIG (NYSE:AIG - News) fell 6% to a 52-week closing low.

The 10-year Treasury yield fell 11 basis points to 4.36%.


But it's not just problems at Citigroup:


After August's turmoil, credit markets had generally stabilized, and stock investors had begun to act as if the problems were over, driving stocks into record territory again. But beginning last week, with the $8.4 billion write-down by Merrill Lynch & Co., a drumbeat of bad news began to send a different message.

Merrill's write-down, which was larger than expected and led to the departure of its chief executive, was significant in that it included fresh financial information from September. All of the other major Wall Street firms ended their quarters in August, so investors interpreted Merrill's news as a sign that markets had soured that month.

Swiss bank UBS AG followed with a warning on Monday
that the fourth quarter was likely to be weaker than it had projected. Bad news from mortgage and bond insurer Radian Group Inc. and from lender GMAC, which yesterday reported large third-quarter losses, added to worries that problems would persist at least through the end of the year.


First, I have to add that I love the irony of an analyst at one financial company downgrading another financial company for problems that are industry wide. That scenario is just, well, really funny.

But..on to more serious problems. All of the action quoted above (financials down, Treasuries up) indicates that investors are nervous about the financial implications of credit market problems. Basically we are returning to the central problem of credit derivatives: there are a ton of them out there and we have no idea what they are worth. Compounding that problem is that financial stocks comprise about 20% of the S&P 500. So -- the largest market segment has a huge balance sheet issue that won't be resolved for some time. That's the type of uncertainty that traders hate.

Right now photobucket is down for routine maintenance. I'll post charts when it's back up and running. Also, I'm traveling again today so I'll be posting from airports throughout the eastern and central US.)
Thursday, November 1, 2007

Today's Markets Pt. II

One of the funny things about traveling is you realize that there are certain things you just can't live without. I use QuoteTracker as my market following program and for charting etc... I literally can't live without it anymore.
Anyway, let's look at today's charts from a program that I know how to use.


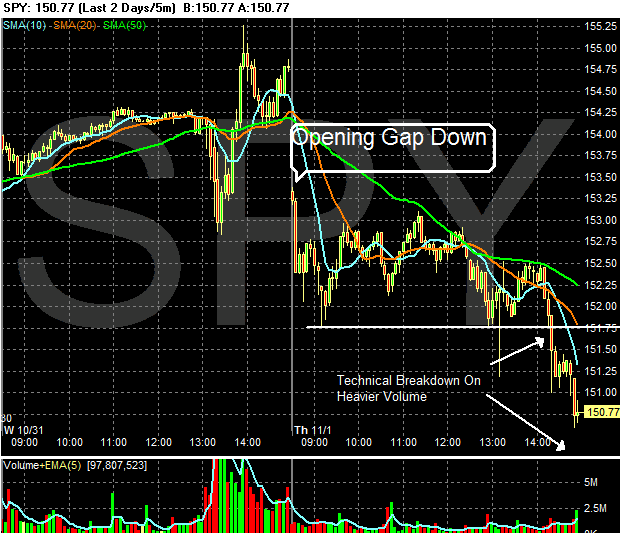
The SPY's gapped down at the opening and then traded in a range until about 2 PM. This is when the SPYs ran into upside resistance from the 50 day SMA. At this point volume picked up and traders literally ran for the doors.


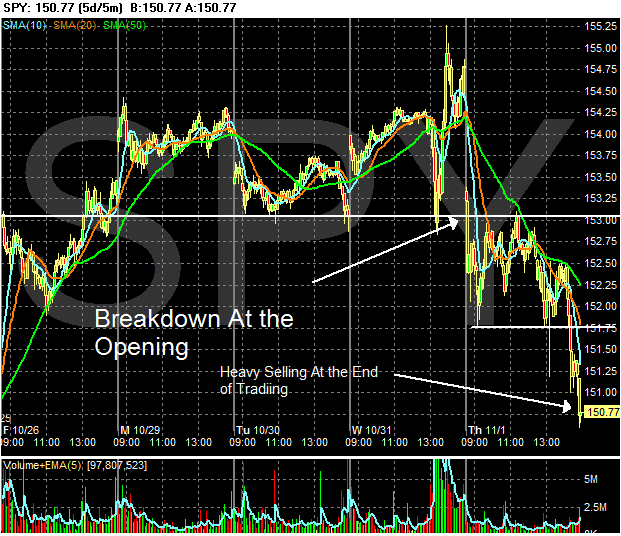
On the 5-day chart we have a complete technical breakdown. The SPYs were holding to a consolidation pattern above about 153 as they waited for the Fed. That broke down right at the opening with the markets falling further as trading went on.


This chart should cause some concern. The good news is we are still above the 200 day SMA. The bad news is...

1.) Today the SPYs fell through 3 SMAs -- the 10, 20 and 50. That means there are three SMAs that will now provide upside resistance to a rally. That's not good.

2.) The upswing that started on 10/22 is now gone. From a long-term perspective, we could be seeing the market move into a period of lower highs and lower lows. In other words a correction (at least) and a bear market (at worst). However, the bear market is a long way off at this point. I'm simply thinking out loud on what the downtrend that started on 10/8 could be starting to look like.


The QQQQs on the other hand, are still in good shape.

1.) The shorter SMAs are higher than the SMAs

2.) Closing prices are still above all the SMAs.

3.) All the SMAs are still headed higher. There may be some trouble brewing with the 10 day SMA, but we'll need a few more days of data for that.


As I mentioned below, the biggest change today is that bad news is now bad news and not fodder for "the Fed will cut rates again." That means the floor the thought of a Fed easing is now gone from traders thinking. That means we could have some seriously rocky times ahead.

Today's Markets

This is part 1. After dinner I'll put up some more charts with more analysis to see exactly what is going on.

Wow -- just one day after the Fed cuts rates the markets tank hard. So the question is -- why? Let's take a look at yesterday's Fed statement.

Readings on core inflation have improved modestly this year, but recent increases in energy and commodity prices, among other factors, may put renewed upward pressure on inflation. In this context, the Committee judges that some inflation risks remain, and it will continue to monitor inflation developments carefully.

The Committee judges that, after this action, the upside risks to inflation roughly balance the downside risks to growth.
The Committee will continue to assess the effects of financial and other developments on economic prospects and will act as needed to foster price stability and sustainable economic growth.


Traders interpreted this to mean the rate cuts were over -- no more liquidity for the stock market.

In addition, there was a ton of bad news today. An analyst report downgraded Citigroup and also speculated they would cut their dividend. The ISM manufacturing number was less than expected. Foreclosures doubled from year ago levels. In short -- it was a terrible news day.


Looking at the 5 day SPY chart above notice a few things. First, the market opened lower but then consolidated. However, the market continued to sell-off in a big way at the end. That indicates traders are concerned about the news that will come out overnight. It also shows there was a ton of selling pressure late in the day.


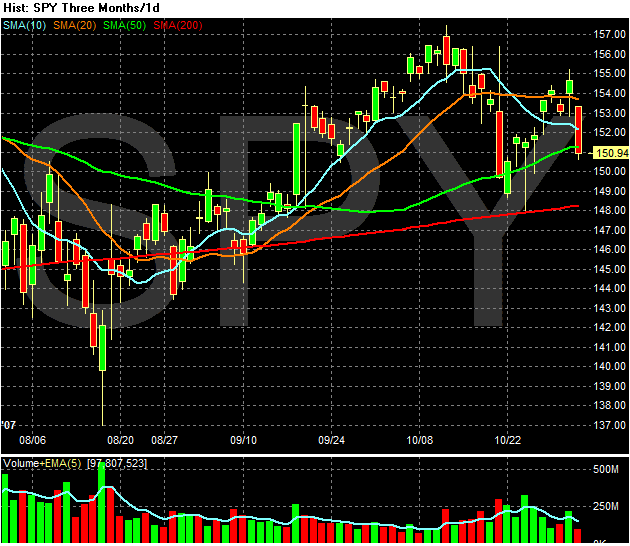
On the daily chart we have the following developments.

1.) We printed a big bar on heavy volume. That's not good.

2.) The market has reversed direction from the rally it started on October 22. Also not the market did not get above previous highs on the most recent rally.

3.) The 20 day SMA is slightly downward, indicating the short-term trend is down.

4.) The market is trading right at the 50 day SMA.

Today's action did some technical damage to the index.