Saturday, February 10, 2024

Weekly Indicators for February 5 - 9 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.


Most notable is that two of the long leading indicators - interest rates and corporate profits - have turned from very negative to at very least neutral, increasingly suggesting better economic news ahead.

As usual, clicking over and reading will bring you up to the virtual moment as to the economy, and reward me a little bit for my efforts.

Friday, February 9, 2024

And now for something completely different: portents of DOOOM


 - by New Deal democrat


The lion’s share of the employment news recently has been very good. But not all of it. In particular, several of the annual revisions to the Household jobs Survey, and several other measures of employment and unemployment have been downright gloomy.


Since I haven’t discussed them at any length, I thought I would collect them all here.

First, there’s been a marked divergence between the Establishment jobs survey (red in the graph below) and the smaller, noisier Household survey (blue) ever since March of 2022. In the latter, about half of all the growth in jobholding was recorded in the two months of December 2022 and January 2023. For the entire 21 month period, jobholding has only increased by 1.9%, far below the payroll employment pace:


Some of this has to do with the annual revision, which is entirely included in the January number each year, rather than revising each of the past 12 months. For example, without the population revision, the month over month gain between December and January this year would have been +239,000 rather than -31,000.

But that issue disappears when we measure YoY% changes, and in the Household survey, jobholding is only up 0.6% YoY in January. The below graph subtracts that to show January at the 0 level, to easily compare earlier times when the YoY growth has been the same:


With the exception of single months during 1996 and 2013, YoY jobholding growth has never been this slow since the 1950s without occurring shortly before or after a recession.

My suspicion is that the current downward spike will prove to be like the two above, but there is other, similar information that gives me pause.

Both the Establishment and Household survey numbers are estimates based on sampling. By contrast, the QCEW survey, which is released quarterly with a 6 month lag, is not a survey but rather the actual number of jobs gained or lost based on employer tax withholding, which must be reported to the government, and includes about 97% of all establishments. The most recent update, for Q2 2023, was reported in early December. Here it is, shown in comparison to both the Estabslishment and *adjusted* Household job numbers (via Menzie Chinn at Econbrowser):


Like the Household survey, the QCEW showed a nearly complete pause in job growth in 2022 after Q1, although it increased more strongly in the first half of 2023. We won’t get the Q3 update until the end of this month, but for Q2 of last year it was up 2.2% YoY vs. the Establishment jobs gain which averaged 2.5%.

And further reason to worry that the Household survey may have been giving a better but more pessimistic reading on jobs growth comes from withholding tax payments. Again, these are not surveys but rather the total amount of income tax withheld for all employees nationwide. 

Matt Trivisonno of the Daily Jobs Update has been updating the YoY changes for the full 365 days compared with the previous 365 days the year before, updated every workday. Here’s what his long term graph (minus the last 90 days) shows:


In October and early November of last year, tax withholding payments for the previous 365 days were only averaging about 0.75% more than they were for the 365 day period ending in early November 2022. With the exception of the year following the 2018 tax law changes, and the 2002-03 near “double-dip” recession, since the beginning of the Millennium this has only occurred during recessions.

Similarly, the State of California’s Treasury Department updates its withholding tax payment information once or twice a month. At the end of January, they showed that December’s payrments were only 1% higher than in 2022, and January’s were -1% *lower:*


And the Department of the Treasury updates their income statement daily. While I can’t show you a graph, their Statement for January 31 of this year shows $1,122.1 Billion withholding tax payments collected since the beginning of the fiscal year on October 1 vs. $1,112.6 Billion collected over the same 4 month period the year before, an increase of only 0.9%.

While there may be other issues going on, e.g., a decline in the aggregate $ amount of stock options exercised, or the effect of a 7% increase in tax brackets due to inflation, this 0.9% is a paltry gain, even if we were to treat it as indexed to inflation rather than nominal.

In addition to the above issues with employment gains, there are several components of un- and under-employment which are contrary to the dominant narrative.

Every Thursday recently I have been pointing out that continuing employment claims (dark blue in the graph below) are running at a higher YoY% rate (presently about 11% higher YoY) vs. the better YoY comparisons in initial claims (light blue), the 4 week average of which is only about 5% higher (note - graph ends at 2019 to avoid the huge spike during the pandemic; both series subtract their current YoY comparison so that it shows at the 0 line):


Contra the story with initial claims, continuing claims have only been 10% or more higher YoY in the past 60 years when a recession is beginning.

A similar story is told when we compare the U6 underemployment rate (dark blue below) to the U3 unemployment rate (light blue). While the latter is at the same level it was a year ago, the U6 rate is 0.5% higher (again, graph subtracts this to show both current levels at the 0 line for easier historical comparison):


With the exception of the 2002-03 near “double-dip” recession scare, the U6 rate has only had this increase since its inception 30 years ago at the onset of recessions.

To reiterate: all of the above data runs counter to most of the jobs-related data I track, in addition to the very positive income, spending, and much improved real sales data that dominate the economy. But all of them - especially the tax withholding and QCEW data - are worth keeping an eye on, to see if they continue to suggest that the economy is weaker than the most popular survey series have been showing.

Thursday, February 8, 2024

Initial jobless claims confirmatory of continued expansion


 - by New Deal democrat


Initial claims continue at their very low level, declining -9,000 to 218,000 last week.  The four week moving average rose 3,750 to 212,250. With the usual one week lag, continuing claims declined -23,000 to 1.871 million:


For forecasting purposes the YoY% change is more important. YoY weekly claims are down -0.9%, the 4 week moving average up 4.4%, and continuing claims up 10.8%:


Both weekly and the four week average of claims are well within the range of forecasting continued expansion. While continuing claims are elevated, and in the past few months sparked some speculation that they signified recession, and taken by themselves, they would, initial claims always precede them. Instead, continuing claims - as usual - have followed initial claims, and are nar their lowest YoY gains in the past year.

The last full month of initial claims, for January, continues to suggest that if anything, the unemployment rate will decline in coming months:


The first week of February data is confirmatory. The Sahm rule is not going to be triggered in the near future.

Wednesday, February 7, 2024

Scenes from the January jobs report: revisions changed the picture in the Establishment Survey


 - by New Deal democrat


Last Friday’s jobs report contained a number of annual revisions which change what the trend line for the last year looks like. Particularly the extent to which there has been continued deceleration, or even a downturn, in a number of significant statistics in the Establishment Survey.


In the below graphs, the original numbers are in blue, the revised numbers in red.

First, in December the YoY% change in jobs created had trended down to +1.7%. With revisions, that increased to 2.0%, and in January it was 1.9%. In the past 6 months, to the extent there has been further deceleration, it has only been from July’s 2.1%:


A similar increase happened to average hourly earnings for nonsupervisory workers. In December the YoY% change was reported as 4.3%. With revisions, it became 4.6%. January saw an increase to 4.8%, almost equal to the YoY% change last August:


A particular weak spot in job creation has been in the higher paying sector of professional and business employment. This had shown an outright decline ever since last spring. There were downward revisions for the earlier months of 2023, and a renewed uptrend in the last two months instead:


While YoY job creation in this sector is still a relatively meager 0.9% (not shown), it is not so poor as the 0.5% which in the past had only happened during recessions.

The revisions weren’t all positive. Aggregate hours of nonsupervisory workers was revised downward for the past 20 months:


Aggregate hours as revised are no better now than they were last August.

But the combination of higher hourly pay and fewer hours meant there was no effect on aggregate payrolls for nonsupervisory workers:


Since this last measure - aggregate payrolls - adjusted for inflation has not changed, the most important coincident indicator of expansion vs. recession remains quite positive.

Tuesday, February 6, 2024

The Senior Loan Officer Survey makes an important turn


  - by New Deal democrat


The Senior Loan Officer jSurvey is a long leading indicator, telling us about credit conditions that typically turn worse a year or more before the economy turns down, and improve just at the economy is ready to turn up.


The one downside is that the information is only reported Quarterly, and with a one a one month lag. Which is a way of saying that data for Q4 of last year was only reported yesterday.

And yesterday’s report was pretty important. Because, for the first time in several years, it was almost entirely positive.

There are two series that have a long enough record to give us a lot of information. The first is whether banks are tightening or loosening standards. Since tightening is shown as an increase, this is one of those series where higher means worse. In Q4, more banks tightened than loosened standards, the percentage of banks so doing decreased sharpl:


This is what happens coming out a reecssions.

The second series, demand for commercial and industrial loans, is almost as positive (and confusingly, in this one higher does mean better. Two of of three measures also showed improvement:


Again, demand has decreased, but not nearly as sharply as before, and this is typically what has happened coming out of recessions.

It has been a long time since the long leading indicators have turned up. But led by interest rates, it appears that has begun to happen.

Monday, February 5, 2024

Travelin’ Man


 - by New Deal democrat


I’m on the road today, so no post. Fortunately, the data is light, so no big deal.

I’ll be back tomorrow, discussing some important revisions in the latest payrolls report. This week I’ll also comment on the updated long leading indicators, including from the recent GDP release as well as the Senior Loan Officer Survey.

Saturday, February 3, 2024

Weekly Indicators for January 29 - February 2 at Seeking Alpha


 - by New Deal democrat


My “Weekly Indicators” post is up at Seeking Alpha.

One week ago many of the high frequency indicators hit an “air pocket.” This week some - but not all! - resolved.

At present there is one of the more anomalous situations I have observed. Most of the data is not just positive, but frequently strongly so. On the other hand, there is a nagging minority of data which is near or flat-out recessionary, some of which (like income tax withholding) is hard to dismiss.

To get the full rundown, click on over and read. It will also reward me a little bit for my efforts in laying the data out for you in an organized format.

Friday, February 2, 2024

January jobs report: a very strong report, but with pockets of significant weakness


 - by New Deal democrat


As per usual, the Establishment and Household portions of the jobs report gave somewhat different impressions, complicated by annual revisions to each. In general, not only was January excellent of the Establishment report, but  most months in the past year were revised upward as well. The Household report mainly was “meh,” neither particularly improving nor declining. Finally, aggregate hours and payrolls were a little concerning.


My focus remains on whether jobs gains are most consistent with a “soft landing,” i.e., no further deterioration, or whether deceleration is ongoing; and more specifically: 
  • Whether there is further deceleration in jobs gains compared with the last 6 month average (Needless to say, the answer to this was a resounding “NO!”)
  • Whether the unemployment rate is neutral or decreasing; or whether there is further weakness; (As expected from the information from initial claims, there was no further weakness) and
  • Based on the leading relationship of the quits rate to average hourly earnings, weather YoY wage growth continues to decline slightly (To the contrary, it rebounded).

Here’s my in depth synopsis.


HEADLINES:
  • 353,000 jobs added. On a YoY basis, jobs rounded to up 1.9%. Due to the annual revisions, this is now tied for the lowest YoY% gain since March 2021. 
  • Both November and December were revised upward, by 9,000 and 117,000 respectively, for a total of 126,000. Almost every month last year, there was a steady drumbeat of downward revisions. This has been all but wiped away by the annual revisions, in which 9 of the last 12 months were revised higher.
  • Private sector jobs increased 317,000. Government jobs increased by 36,000.
  • The alternate, and more volatile measure in the household report, declined by -451,000 before taking into account the annual revisions. After doing so, the month over month change would have been +239,000.  More importantly, the YoY% gain in this report - which avoids issues with seasonal adjustment - declined sharply to +0.6%, the lowest since the pandemic lockdowns.
  • The U3 unemployment rate remained at 3.7%.
  • The U6 underemployment rate increased +0.1% to 7.2%, 0.7% above its low of December 2022.
  • Further out on the spectrum, those who are not in the labor force but want a job now increased 122,000 to 5.793 million, its highest level since September 2022, vs. its post-pandemic low of 4.925 million set last March

Leading employment indicators of a slowdown or recession

These are leading sectors for the economy overall, and help us gauge how much the post-pandemic employment boom is shading towards a downturn.  With one exception, these were positive.:
  • the average manufacturing workweek, one of the 10 components of the Index of Leading Indicators, declined sharply, by another -0.3 hours to 40.0, down -1.5 hours from its February 2022 peak of 41.5 hours, and the lowest level since June 2020.
  • Manufacturing jobs rose 23,000.
  • Within that sector, motor vehicle manufacturing jobs rose 3,100. 
  • Construction jobs increased by 11,000.
  • Residential construction jobs, which are even more leading, rose by 2,500. This is a yet another new post-pandemic high.
  • Goods jobs as a whole rose 11,000 to another new expansion high. These should decline before any recession occurs. After revisions, these are up 1.2% YoY, the lowest growth since early in the pandemic, but which is nevertheless average compared with most of the last 40 years.
  • Temporary jobs, which have generally been declining late 2022, rose by 3,900, and are down about -250,000 since their peak in March 2022.
  • the number of people unemployed for 5 weeks or fewer declined -51,000 to 2,140,000.

Wages of non-managerial workers
  • Average Hourly Earnings for Production and Nonsupervisory Personnel increased $.13, or +0.4%, to $29.66, a YoY gain of +4.8%. The last 3 months have seen the previous deceleration in this metric stop.

Aggregate hours and wages: 
  • the index of aggregate hours worked for non-managerial workers fell -0.2% to the lowest level in 5 months, and after revisions is only up 0.2% YoY, the lowest since March 2021.
  •  the index of aggregate payrolls for non-managerial workers rose 0.2%, and decelerated to being up 5.0% YoY. This is still 1.7% above the most recent YoY inflation rate. In the last 3 months, inflation has only averaged 0.1% monthly, so this may be a positive in real terms as well.

Other significant data:
  • Leisure and hospitality jobs, which were the most hard-hit during the pandemic, rose another 11,000, which is only -75,000, or -0.4% below their pre-pandemic peak.
  • Within the leisure and hospitality sector, food and drink establishments rose 4,600,. This sector has completely recovered from its pandemic downturn. 
  • Professional and business employment increased 74,000. These tend to be well-paying jobs, This series had been declining since last May, but after revisions, the last 2 months have both made new record highs.
  • The employment population ratio increased +0.1% to 60.2%, vs. 61.1% in February 2020.
  • The Labor Force Participation Rate was unchanged at 62.5%, vs. 63.4% in February 2020.


SUMMARY

This month’s report was complicated by extensive revisions to the Establishment side, and population adjustments to the Household side. In general, the Establishment numbers were revised downward in the early part of last year, but upward in almost all months ever since. With these revisions, almost all of the monthly deceleration which I discussed monthly last year has disappeared, although it remains on a YoY basis - but the YoY level of growth is presently to 1.9%, which historically has been perfectly normal.

As noted above, almost all of the leading (and coincident) job sectors showed gains, a number to new post-pandemic highs. Nonsupervisory wage gains appear to have leveled off (i.e., have stopped decelerating) on a real, inflation-adjusted basis.

There were some negatives. The manufacturing workweek is practically screaming “recession” in that sector. In fact, this is a decline typical at the bottom of recessions. Additionally, aggregate hours declined, and aggregate real payrolls *may* have stalled. Also, the U6 underemployment rate increased again. This series only has a 30 year history, but during that history, the level of increase we have seen has only happened early in recessions.

Overall, I interpret this as a very strong report, but with pockets of significant weakness.

Thursday, February 1, 2024

New month’s data starts out with leading indicators in both manufacturing and construction indicating expansion


 - by New Deal democrat


As usual, the new month’s data starts out with information on manufacturing and construction.


The ISM manufacturing index has been a good leading indicator in that sector for 75 years. The difference over time, especially the last 20 years, is that manufacturing makes up a smaller share of the total US economy.

With that caveat, after almost 18 months in contraction, the most leading new orders subindex in the ISM report rose from 47.0 to 52.5. Since any reading above 50 indicates expansion, this is welcome news (although I hasten to add that it is diametrically opposed to the poor regional Fed manufacturing readings for January). The Index as a whole rose from 47.1 to 49.1, still showing very slight contraction, but nevertheless a 1+ year high:


This is (relatively) good news for the manufacturing sector.

Construction spending continued its strong improvement. Total spending (light blue below) rose 0.9% in December, and the more leading residential construction sector (dark blue) increased 1.4%, both to new all-time (nominal) highs:


Since producer prices for construction materials rose 0.6% in December (red), this indicates real growth of 0.8% in residential construction spending, a strong showing.

The bottom line is that this is good news in both leading goods-producing sectors to start out the month.

Continuing claims near 2+ year high; likely the effect of Silicon Valley layoffs


 - by New Deal democrat


Initial claims rose by 9,000 to a three month high of 224,000 last week. The four week moving average also rose 5,350 to 207,750. With the usual one week lag, however, continuing claims rose sharply, by 70,000, to 1.898 million, close to a 2+ year high:


On the more important YoY% change basis, initial claims were up 12.6%, while the four week average was up 4.1%, and continuing claims were up 14.3%:


Although the one week average superficially would be a cause for concern, this comparison is against nearly all time lows set late in January 2023, as shown in the first graph above. In February 2023 claims rose to the 215-230,000 level, so we would need to see claims rise to roughly 240,000 or more for this to be a real concern.

There had been some commentary a few months ago about the elevated YoY level of continuing claims. They certainly do suggest that some people are having trouble finding new employment. In this regard, periodically I check the California Department of Revenue for their analysis of income tax withholding payments. For January, they indicated a YoY decline of -1%.

Such a decline typically means an outright decline in nonfarm payrolls, in this case, for the State. We know that the explosive growth in Silicon Valley early in the pandemic has very much faded, with layoffs being in vogue. It seems likely that this is the source for both the decline in CA withholding tax payments, and the stubborn increase in continuing claims, as this one sector may well be in a recession.

But updating the Sahm Rule analysis, January as a whole showed a continuing decline in initial claims  from last spring and summer’s more elevated levels:


and since claims lead the unemployment rate, this suggests that in tomorrow’s report, as well as the next few months, unemployment is very unlikely to increase above 3.8%, and is more likely to decline towards 3.6% or even 3.5%.

A comment on median vs. mean, and job-stratified wage growth


 - by New Deal democrat


Before today’s avalanche of data, I wanted to comment briefly on the Employment Cost Index for Q4 that was reported yesterday.


This index has the advantage of weighting for type of employment. If low wage workers gain a disproportionate number of jobs, that will tend to hold down *average* wages. But the ECI hold the weighting of low, medium, and high wage jobs constant, so that it tells us how much pay for the *same job* varies from quarter to quarter. And because it is a median vs. average measure, it isn’t skewed by disproportionate gains at the very high end.

The quarter over quarter change in the ECI is shown in red in the graph below, since the peak in wage growth in 2021, compared with average nonsupervisory wage growth (light blue) and average total private wage growth (dark blue):


All three show deceleration, and all three are currently between 4.0% and 4.5% growth YoY, as shown in the graph below:


Note that average hourly wages spiked during the pandemic lockdown period, when low wage service workers were very disproportionately laid off. When they were rehired in 2021, and seemingly every retail business had a “help wanted” sign on their front window or roadside sign, average hourly wages for lower income, nonsupervisory workers spiked far more than other wages. By contrast, the wage paid for *the same work* was not affected by the pandemic layoffs, but did increase sharply as the unemployment rate fell to historical lows.

This “game of reverse musical chairs,” as I have called it over the past couple of years, has pretty much come to an end, and more typical wage growth for an expansion has ensued. 

Tomorrow both average wage measures will be updated for January as part of the jobs report. I anticipate further deceleration.

Wednesday, January 31, 2024

December JOLTS report: while hiring has weakened, firing (and quitting) continue to show a strong labor market


 - by New Deal democrat


Yesterday’s JOLTS report for December showed a labor market that, while decelerating, remains relatively strong.


Let me start with layoffs and discharges, which increased by 85,000 to 1.616 million (blue in the graph below). This is nevertheless about average for the past year, and as usual mirrors the pattern in initial jobless claims (red):


Meanwhile, job openings (blue in the graph below), a soft statistic that is polluted by imaginary, permanent, and trolling listings, increased 101,000 to 9.026 million. Actual hires (red) increased 97,000 to 5.621 million. Voluntary quits (gold) declined -132,000 to 3.392 million. In the below graph, they are all normed to a level of 100 as of just before the pandemic:


Interestingly, while job openings are still 29% higher than just before the pandemic, both hires (-6.3%) and quits (-2.8%) are lower than that level. So is the jobs market actually weak?

Not really. 

To show you why, the below graph norms the rates of hires, quits, and layoffs and discharges to the zero line as of the average of their most recent readings, and shows you their record in the 20 years before the pandemic:


Layoffs and discharges are lower now than at any time before the pandemic. Voluntary quits are higher than at any point before the pandemic except for 3 years (2000 and 2018-19). Only hires are relatively weak, lower now than at about 60% of all years since the series began.

More often than not, hiring slows down before firing picks up. As a share of the available labor, hiring has indeed slowed down - to a slightly less than average level. But both voluntary quits as well as layoffs and discharges continue to show a very strong labor market.

ADDENDUM: Since the quits rate tends to lead average hourly earnings, I wanted to add that. The quits rate remained even compared with November, at the lowest rate since the pandemic. This implies that average hourly earnings, which will be updated as part of Friday’s employment report, will decelerate further:


Tuesday, January 30, 2024

Repeat home sale prices continue rebound; rents continue decline


 - by New Deal democrat


Since the Fed started raising interest rates almost two years ago, homebuilding has shifted away from single family houses to condos and apartments, the construction of which has made repeated all-time highs.


This has become reflected in house price vs. apartment rental indices.

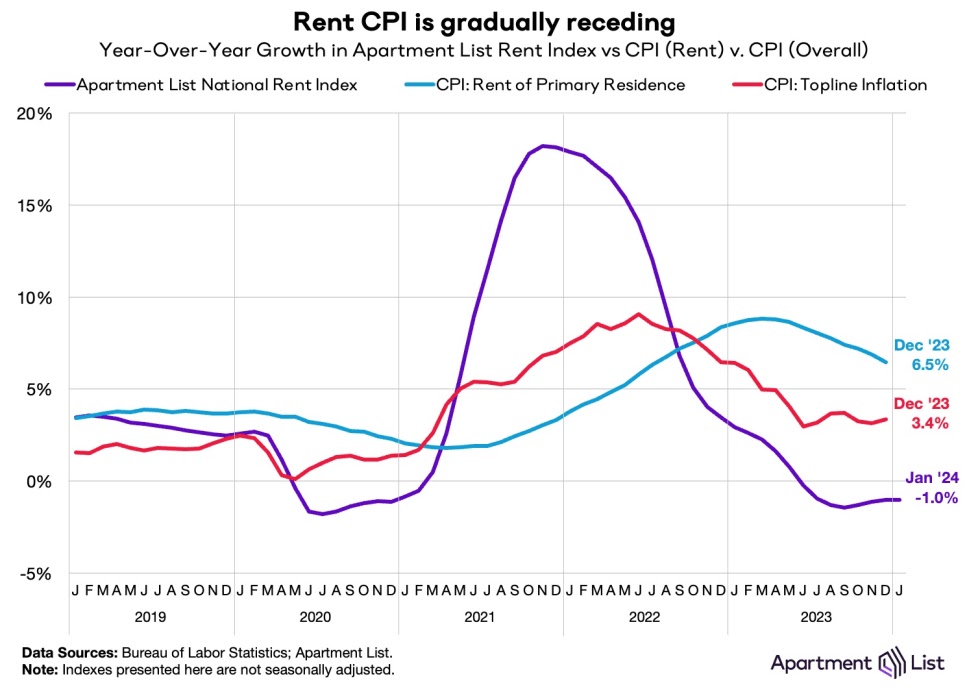
Starting with apartment rents, according to the Apartment List National Rent Report, new rental prices declined seasonally in January by -0.3%:


On a YoY basis, apartment rents are down 1%, as they have been for the last six months. As the report points out, because of this we can expect the CPI measure of “rent of primary residence” to continue to decline from its current 6.5% YoY level:


The story is more complicated with regard to single family homes, which were chronically under-built ever since the Great Recession. Needless to say, this shortage was not going to be resolved either by higher prices or higher mortgage rates. 

And that is what has shown up in both the FHFA and Case-Shiller Indexes for November which were reported this morning.

The FHFA index rose 0.3% on a monthly basis, while the Case-Shiller National index increased 0.2%. This compares with generally declining monthly prices one year ago::


On a YoY basis, the FHFA index rose further slightly to 6.6%, and the Case Shiller index also rise further slightly to 5.2%. As the below graph shows, although this seems like a major increase, it is par for the course for YoY gains in both indexes for most of the last 25 years outside of recessions. Further, because these house price indexes lead the CPI measure of Owners Equivalent Rent, it remains likely that there is going to be further deceleration in that index, although the pace of that decline may itself decelerate:


This in turn suggests that both headline and core CPI have bottomed out on a YoY basis as well.

Monday, January 29, 2024

Both production and transportation are down from 2022 peaks; why wasn’t that enough to cause a recession?


 - by New Deal democrat


While I have written about how the Index of Leading Indicators failed last year, as the loosening of and disinflation in supply chains overwhelmed the effects of Fed tightening, it wasn’t as if Fed tightening had no effect. In fact in the typical places where we would first expect to find those effects - namely, in the production and transport of goods - it did indeed show up.


To wit: total industrial production, manufacturing production, and the construction of total housing units all peaked in September or October 2022, and have not made any new highs since:


The difference between the experience since then and on earlier occasions can be seen in this longer term look at the same data:


In all other cases, construction and/or production turned down significantly, bringing about recessions, vs. 2023, when the decreases in both were very small.

And that isn’t the only typical metric that behaved in the manner we would expect in response to Fed rate hikes. Way back in the late 1800s, Charles Dow, writing about stock prices, invented the “Dow theory”, which posits very sensibly that all goods produced must be transported to market for sale. Therefore both production and transportation should turn up or down in tandem.

Indeed, heavy vehicle sales (red in the graph below) tend to turn down over 10% months before any recession begins; sooner and more decisively than light vehicle sales (blue):


Sales of heavy weight trucks have declined almost 20% since last May, a severity of decline that more often than not in the past has meant an oncoming recession.

The downturn in transportation isn’t limited to sales of trucks. The US Freight Transportation Index also has not made a new high since August 2022:


although it, like industrial and manufacturing production, has rebounded since last spring.

What has helped the economy considerably is that even though production and transportation turned down from 2022 into 2023, real sales (red in the graph below) bottomed earlier in 2022 and have increased consistently since the beginning of last spring, making new highs beginning in September:


An important reason why sales have been faring better than production or transportation is that, as I have said many times over the years, sales lead inventories.

Sales turn both up and down before inventories do. As the below graph shows, on a YoY basis sales peaked in 2021, while inventories continued to increase into 2022:


YoY sales thereafter decelerated and were even negative in the first half of 2023. Inventories have followed, although they have never turned negative. As of last month, sales were up 1.0% YoY, while inventories were up 0.4%.

What the below YoY graph of real sales, the transportation index, and industrial production shows is that transportation of goods to market turns negative as sales decelerate and inventories increase (see, e.g., 2015-16):


If sales steady with the reduction of inventory, transportation and production begin to improve as well.

That appears to be what happened in the second half of 2023. Even though Fed rate hikes had their traditional effect on goods production and transportation, the sharp deflation in producer costs and disinflation in consumer prices, including fuel, allowed sales to increase sufficiently for production to take only a minor hit.

Saturday, January 27, 2024

Weekly Indicators for January 22 - 26 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.

Every now and then the data has a particularly noisy week, and this past week seems to have been one, as a number of - especially coincident - indicators hit an air pocket.

Perhaps more concerning is that the 4 week total of tax withholding YoY has gone negative again. But consumer spending, in both nominal and real terms, remains very robust.

In any event, clicking over and reading will bring you up to the virtual moment as to the economy, and reward me a little bit for my efforts in organizing and digesting the data.

Friday, January 26, 2024

December 2023 personal income and spending: Goldilocks is in the house UPDATED


 - by New Deal democrat


[Note: The St. Louis FRED site is down for maintenance, which means unfortunately there are no graphs available to accompany this post at present. As soon as FRED is back up and adds the data, I will update with graphs. Additionally, one metric - real manufacturing and trade sales - also cannot be calculated until FRED updates.

UPDATED: The problem is now fixed.]


Personal income and spending has become one of the two most important monthly reports I follow, because it nets out the impacts of higher interest rates and abating inflation due to the unlinking of the supply chain.

Nominally income rose 0.3% in December. Nominal spending rose 0.7%. Prices as measured by the PCE deflator increased 0.2% for the month, meaning that in real terms income rose 0.1% and spending rose a strong 0.5%. Since just before the pandemic real incomes are up 6.3%, and spending is up 10.5% (NOTE: Data in all graphs below except for YoY comparisons is normed to 100 as of just before the pandemic):


On a YoY basis, the PCE price index is up 2.6% for the second month in a row, the lowest since February 2021, and almost back to the Fed’s target of 2.0%:


Perhaps most importantly, for the last 11 months this price index is only up 1.7% - under the Fed’s 2% target. Last January this index rose 1.0%. If in next month’s report it only rises 0.3% or less, the Fed’s target will have been fully met:


For the past 50+ years, real spending on services has generally increased even during recessions. It is real spending on goods which declines. Last month real services spending rose 0.3%, and real goods spending rose a strong 1.1%:


As per form, real services spending has risen consistently since the pandemic, while goods spending have been somewhat of a mirror image of gas prices, which peaked in June 2022.

Real durable goods spending tends to turn before non-durable goods spending. The former increased a very strong 1.5% for the month, while the latter increased 0.9%:


Durable goods spending had been very much affected over the past several years by the shortage of new vehicle inventory, which has largely abated as this year has progressed.

The one significant blemish on this report is that another important metric for the near future of the economy is the personal savings rate, which declined -0.4% to 3.7%:


As I’ve noted for the past few months, this remains among the lowest rates of savings ever. Only the record lows of 2005-07, and 2022 were lower in the entire history of the series.

On the positive side, this indicates a lot of consumer confidence. But it also indicates vulnerability to an adverse shock.

The NBER pays particular attention to several other aspects of this release. Real income excluding government transfers (like the 2020 and 2021 stimulus payments) continued to increase, up 0.1% for the month, to a new record high:


Once again, this has been something of a mirror image of gas prices, rising consistently since June 2022.

Finally, the deflator in this morning’s report is used to calculated real manufacturing and trade sales, another metric relied upon by the NBER. This increased a strong 0.9%,also to a new record high:


In summary, this month’s report continued to reflect a consumer economy that is doing very well. Inflation has returned to the Fed’s preferred baseline rate, and both incomes and spending are up substantially. You would be well within your rights to call this a “Goldilocks” economy.