Saturday, January 20, 2024

Weekly Indicators for January 15 - 19 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.


The big headlines yesterday were that stocks made a new all time high, for the first time in two years.

Meanwhile, estimated plus actual earnings so far for the 4th Quarter of 2023 were on track for their lowest number since Q1 of 2021.

Either corporate earnings are going to rebound sharply or stocks have gotten far ahead of themselves. Either way this discrepancy is going to resolve.

If corporate earnings are not just in a one Quarter air pocket, we can expect increased layoffs and cutbacks in capital spending. We’ll see.

As usual, clicking over and reading will bring you up to the virtual moment as to the economy, and reward me with a little lunch money for my efforts.

Friday, January 19, 2024

Briefly noted: existing home sales appear to be bottoming near 30 year lows as prices continue to firm


 - by New Deal democrat


Last month I wrote that existing home sales “are likely in the process of bottoming, as they have been in the range of 3.79 million to 4.10 million for the past five months:”


That continued to be the case in December, as sales declined -3,000 on an annualized basis to 3.78 million:


On a longer term basis, existing home sales are at the lowest level in almost 30 years, and down over -40% from their post-pandemic peak:


With so many people locked in to mortgages of 3% or so, inventory continues to be anemic, so potential buyers are bidding on the relatively few homes available. This is keeping prices close to their highs. Prices have been higher YoY for the past six months, currently up 4.4%:


This is in contrast to new homes, where builders can control sizes, amenities, rebates, and prices to generate demand. In that market prices are down about 10% YoY and sales are down about 25% from just before the Fed started raising rates. So the bifurcation of the two markets continues.

Thursday, January 18, 2024

Housing construction changes little in December; but increased mortgage rates from H2 2023 have not yet been digested


 - by New Deal democrat


For this post, I’m going to show what the housing market looks like from most to least leading of the indicators. That shows that, although this morning’s release for housing permits and starts for December was generally positive, it is more likely that housing construction will decline rather than advance further in coming months.


Since interest rates lead housing construction, let’s start with the YoY change in mortgage rates (inverted, red) vs. the YoY change in housing permits (/10 for scale):


In December, mortgage rates were only about 0.4% higher than they were one year ago, suggesting that housing permits, which were actually 6% higher than in December 2022, will cool off in the coming months.

This shows up better when we compared the actual numbers. Mortgage rates rose significantly in October and November of both 2022 and 2023, only to decline in December of both years. In the first part of 2023, they remained lower than they had been in late 2022. With a lag, permits followed, turning down at the end of 2022 and then rising in the first half 2023 before leveling off in the second part of the year:


We are probably going to see a downturn in permits in the coming months, in reaction to the increase in mortgage rates during autumn.

The next most leading marker is that single family new home sales, although very noisy and heavily revised, tend to lead single family permits by several months. In reaction to the rise in interest rates in late 2023 discussed above, new home sales (blue) have already turned down (their 3 month average is down -7.5% from last spring’s peak), suggesting that single family permits (red), which made 1.5 year high in December) are going to follow:


Housing starts (light blue in the graph below) follow typically permits (blue) with a one to two month lag, and they are noisier:


Starts have trended sideways to slightly higher in the second part of 2023, but their noise makes a true trend almost impossible to see.

Finally, lagging all of the above is the actual economic impact of housing, units under construction. In contrast to conditions which have preceded recessions, these have turned down only slightly in the past year:


Because there has been a particular emphasis on multi-unit construction, here are single family (red), multi-unit (gold), and total units (blue) under construction for the past 5 years:


Single family housing under construction is down about -20%, at the lowest level since May 2021, while multi-unit construction has declined only -1% from its peak early last year. Total units, which typically have declined -10% or more before recessions, are only down -2%, nevertheless at their lowest level since April 2022.

To see where these trends are headed, here are permits for each:


All of the recent increase in permits has been for single family housing, which increased to its highest level since May 2022. The big increase in multi-unit permits has completely reverted to pre-pandemic levels, a -35% decline. While multi-unit permits increased slightly in December, they remain just slightly higher than their 3 year low set in November. Because multi-unit construction takes much longer than single family housing construction, the decline in apartment and condo construction is likely to slowly play out over this entire year.

To summarize: although there was a big decline in mortgage rates in December, the higher rates of the second half of 2023 have yet to work their way through housing construction. We can expect permits, starts, and units under construction to decline in the months ahead. Because manufacturing for the past year has been generally recessionary, how much housing construction declines will be very important for the economy in the latter part of this year. The course of housing thereafter depends on whether the decrease in mortgage rates since Thanksgiving is sustained or continues. 

Jobless claims: bar one week, the lowest number of layoffs in over half a century


 - by New Deal democrat


To reiterate my theme from last week, we’re back to the virtuous scenario where almost nobody is getting laid off.


Initial jobless claims last week declined -16,000 to 187,000. Except for one week in September 2022, this is the lowest number in over 50 years (since 1969, to be more precise). The 4 week average declined -4,750 to 203,250, the lowest since last January. With the usual one week delay, continuing claims declined -26,000 to 1.806 million:


The one caution here is that some of this may be due to seasonal adjustments, which are particularly hard during and just after the holiday season, especially as distorted by the pandemic years.

On a YoY% basis, initial claims were down -6.5%, and the more important 4 week average was down -1.3%. Continuing claims were up 10.5%, which nevertheless was the lowest increase since the end of last March:


All of this bodes well for employment in the next few months.

Finally, since initial claims lead the unemployment rate by several months, for purposes of forecasting the effect on the “Sahm rule” measure of the unemployment rate, the first two weeks of January have averaged a decline of -4.2% YoY:


Since in the first half of 2023, the unemployment rate varied between 3.4% and 3.8%, this forecasts that the unemployment rate in the next few months is going to tend down towards the lower part of that range. Needless to say, this strongly suggests that the “Sahm rule” is not going to be triggered anytime soon.


Wednesday, January 17, 2024

Industrial production continues in near-recessionary trajectory


 - by New Deal democrat


In contrast to this morning’s good news on consumption, production continued its lackluster 2023 all the way to the end.


Total industrial production (blue in the graph below) increased 0.1% in December, but revisions to the two previous months totaled -0.2%, so the net result was a -0.1% decrease compared with where we thought we were in November. Manufacturing production (red) had an identical December increase and negative revisions. The below graph shows each in comparison with their respective September and October 2022 peaks. 


Total production remains down -1.0% since then, and manufacturing production down -1.2%.

Because December 2022 was awful, with declines of -1.5% and -2.2% respectively, the YoY comparisons for total and manufacturing production improved to +1.0% and 1.2%:


The conclusion remains that manufacturing is in at least near-recessionary conditions. But because manufacturing forms a significantly lower share of the economy now than it did before the “China shock” that began in 1999, it isn’t enough to tip the entire economy over. Construction in particular has been holding up well - and we’ll get the latest read on that sector with tomorrow’s report on housing permits and starts.

December real retail sales: the good economic news keeps on coming


 - by New Deal democrat


The good economic news kept coming with this morning’s retail sales report for December. Remember that this is one of my favorite indicators because, adjusted for population, it is a fairly good long leading indicator, and on a short term basis has a consistent record of leading the trend in employment.


Nominally retail spending increased 0.6% for the month. More importantly, after adjusting for inflation, which rose 0.3%, real retail spending rounded to up 0.2%. This continued a nearly perfect record of monthly increases that started last March, and is 2.2% above its post-pandemic stimulus low in February 2022. The only negative is that it does remain -1.9% below its post-pandemic peak in April 2022:


The best way to visualize retail sales’ lead over employment (red in the graph below) is YoY (blue, /2 for scale), shown for the past 30 years. I also show real personal consumption on goods since the turn of the Millennium (light blue), which has a similar record:


Here is the close-up since July 2022:


The good news here is that YoY comparisons of real retail sales continue to improve, now up 1.1%. Real personal consumption on goods has similarly improved, up 1.8% as of November. Since nonfarm payrolls were up 1.7% YoY, both consumption series suggest that any further deceleration in jobs gains will be slow, and it is possible we get the fabled “soft landing,” with job growth leveling out at this trend rate.

To reiterate: this was a good report.

Tuesday, January 16, 2024

As vehicles and outdoor appliances become increasingly electric, long term gas usage - and “real” prices - decline


 - by New Deal democrat


What is the “real” cost of gasoline? When measuring this, some people compare with the CPI. But that actually just tells you the *relative* inflation in gas vs. other items. That’s why, for example, when I want to look at the “real” cost of housing, I measure against income, such as average hourly earnings. That tells you how much labor it costs the average person to buy an item.


So here are oil prices (blue, right scale) and gas prices (red, left scale) divided by average hourly wages for nonsupervisory workers since 1998. I start here because gas prices hit a generational low of $0.80/gallon at the beginning of 1999 - barely above where they were in 1974:


At their peak in July 2008, oil prices were 8x their price in wage-adjusted terms compared with 1999. Gas prices were almost 3x as high. At their pandemic lockdown lows, they were barely unchanged since 1999. Currently oil prices are 2.6x their cost in wages compared with their 1999 low. Gas at the pump is only 50% higher than 1999. This is on the low side of average since the big slide in prices 10 years ago in 2014.

Put another way, right now gas is relatively cheap compared with most of the past 25 years.

And there is good reason to believe that going forward oil price shocks will not be as big a deal as they have been over the past 50 years. That’s because many outdoor appliances like lawn mowers and leaf blowers are now electric powered. Even more importantly, in the past 3 years the percentage of new light vehicles sold that are hybrids or electric has risen from 5% to 16%:


I suspect if anything this trend is going to accelerate, as electric vehicles become less expensive and have increased range, and more two vehicle households buy at least one for shorter trips. Meanwhile hybrids have solved their previous issues with acceleration.

The effects of this can be seen in the weekly update of gasoline usage by the E.I.A., data on which goes back to 1991:


The all-time peak of gasoline usage was in August 2019, when nearly 9.8 million barrels were used per day. The post-pandemic peak was 9.528 million in August 2021. This past summer the peak was 9.388 million barrels.

As a bigger and bigger percentage of vehicles on the road are hybrids or EVs, I expect the decline in gas usage to continue. This in turn will lessen considerably the effect of oil price shocks in the future.

Monday, January 15, 2024

For MLK Day: Blacks are faring better during the post-pandemic Boom than at almost any time in the previous 50+ years


 - by New Deal democrat


On this MLK Jr. national holiday, let’s take a look at how Blacks are faring in the current economy.


And the answer is, pretty good!

The unemployment rate for Blacks in December was the 2nd lowest ever in 50+ years of history, at 5.2%. The lowest was last April at 4.8%:


The Black unemployment rate was only 1.7% higher than that for Whites, also the lowest gap in 50+ years (blue, right scale). Because Black unemployment has typically risen faster than White unemployment when the economy weakens, and has typically been in the range of twice the level of White unemployment, I also show the ratio of Black to While unemployment as well (red, left scale):


Black unemployment was slightly below 1.5x the level of White unemployment in December, the lowest multiple ever.

Finally, the employment-population ratio for Blacks was 60.1% (vs. 59.9% for Whites, not shown):


This is the 2nd lowest of the past 25 years, vs. last March’s 61.7%. These numbers were only exceeded during the late 1990s tech Boom, peaking at 61.4%, vs. 65.5% for Whites.

The post-pandemic jobs Boom hasn’t just been a “rising tide lifting all boats,” it has particularly benefitted those historically most marginalized in the jobs market.

Saturday, January 13, 2024

Weekly Indicators for January 8 - 12 at Seeking Alpha


 - by New Deal democrat


My Weekly Indicators post is up at Seeking Alpha.

There are almost always a few interesting ripples in the pond. In the past month, notably there has been the sudden collapse in YoY tax withholding payments. I’m not too concerned yet, but if it goes on much longer, it would portend some serious employment weakness.

Another such ripple, among the long leading indicators, is that the spike in corporate earnings in Q3 (remember the stellar GDP report?) has completely reversed in Q4, at least according to earnings estimates as they stand now. This could sharply reverse as actual earnings are reported; but usually by now the estimates are already being revised higher. Not happening so far this quarter.

As usual, clicking over and reading will bring you up to the virtual moment as to all the data, and reward me a little bit for my efforts.

Friday, January 12, 2024

Producer prices flat, commodities decline, confirming shelter as sole inflationary pressure


 - by New Deal democrat


Once again producer prices confirmed that the only significant problem in inflation is shelter.


In December commodity prices declined -1.3%. For finished goods they declined -1.2%. Even producer prices for services were unchanged:


On a YoY basis, commodity prices are down -3.2%, finished goods prices down -0.2%, and producer prices for services up 1.8%:


Needless to say, none of these suggest any producer inflation pressures in the pipeline at all. Here is what final goods producer prices (blue), headline consumer prices (red), and consumer prices excluding shelter (gold) look like since the energy inflection point of June 2022:


Producer prices are up only 1.4% since then, and CPI less shelter up 1.9%, vs. headline consumer prices up 4.8%.

The only real inflationary issue in the US economy is shelter as measured by the CPI. Paradoxically, high interest rates, which depress homebuilding, do not help this issue at all.

Thursday, January 11, 2024

Consumer inflation remains all about the lagged effect of house prices


 - by New Deal democrat


Consumer inflation in December continued to be a tale of the relative importance of gas prices vs. the lagged effect of home prices.


Headline inflation increased 0.3%, and was up 3.4% YoY. YoY headline inflation has bounced between 3.1%-3.7% for the past 6 months, i.e., ever since the gas price peak of June 2022 passed out of the YoY comparisons. “Core” inflation ex-food and energy also increased 0.3%, and was up 3.9% YoY, the lowest YoY increase since May 2021. Inflation ex-shelter rose 0.2%, and is only up 1.9% YoY (originally I wrote there was a monthly decline of -0.4%. That was in error. Not sure where that came from!):

Here are the YoY% comparisons for each:


And to demonstrate the importance of the peak in gas prices in June 2022, as well as the lagged effect of house prices, here is the % change in each since then:


Headline inflation is up 4.8% in the past 18 months, while core inflation, which does not include energy, is up 6.5%. But inflation ex-shelter is only up a total of 0.2% since then!

Once again, for all intents and purposes, consumer inflation for the past year and a half has been all about house and apartment prices (and the measurement thereof).

As to shelter, here is the update to my graph of the YoY% change in house prices, as measured by the FHFA, vs. Owners Equivalent Rent in the CPI:


The YoY% change in OER declined -0.2% to 6.5% in December, the lowest YoY change since August 2022. It will likely continue to decline at the same slow pace in the next few months. (As an aside, I shouldn’t have to say this, but I didn’t just start citing this when I expected OER to come down. I’ve been pounding on this theme since late 2021, when I expected the lagged effect of house prices to drag OER higher - indeed to 8% or more. Which it did.)

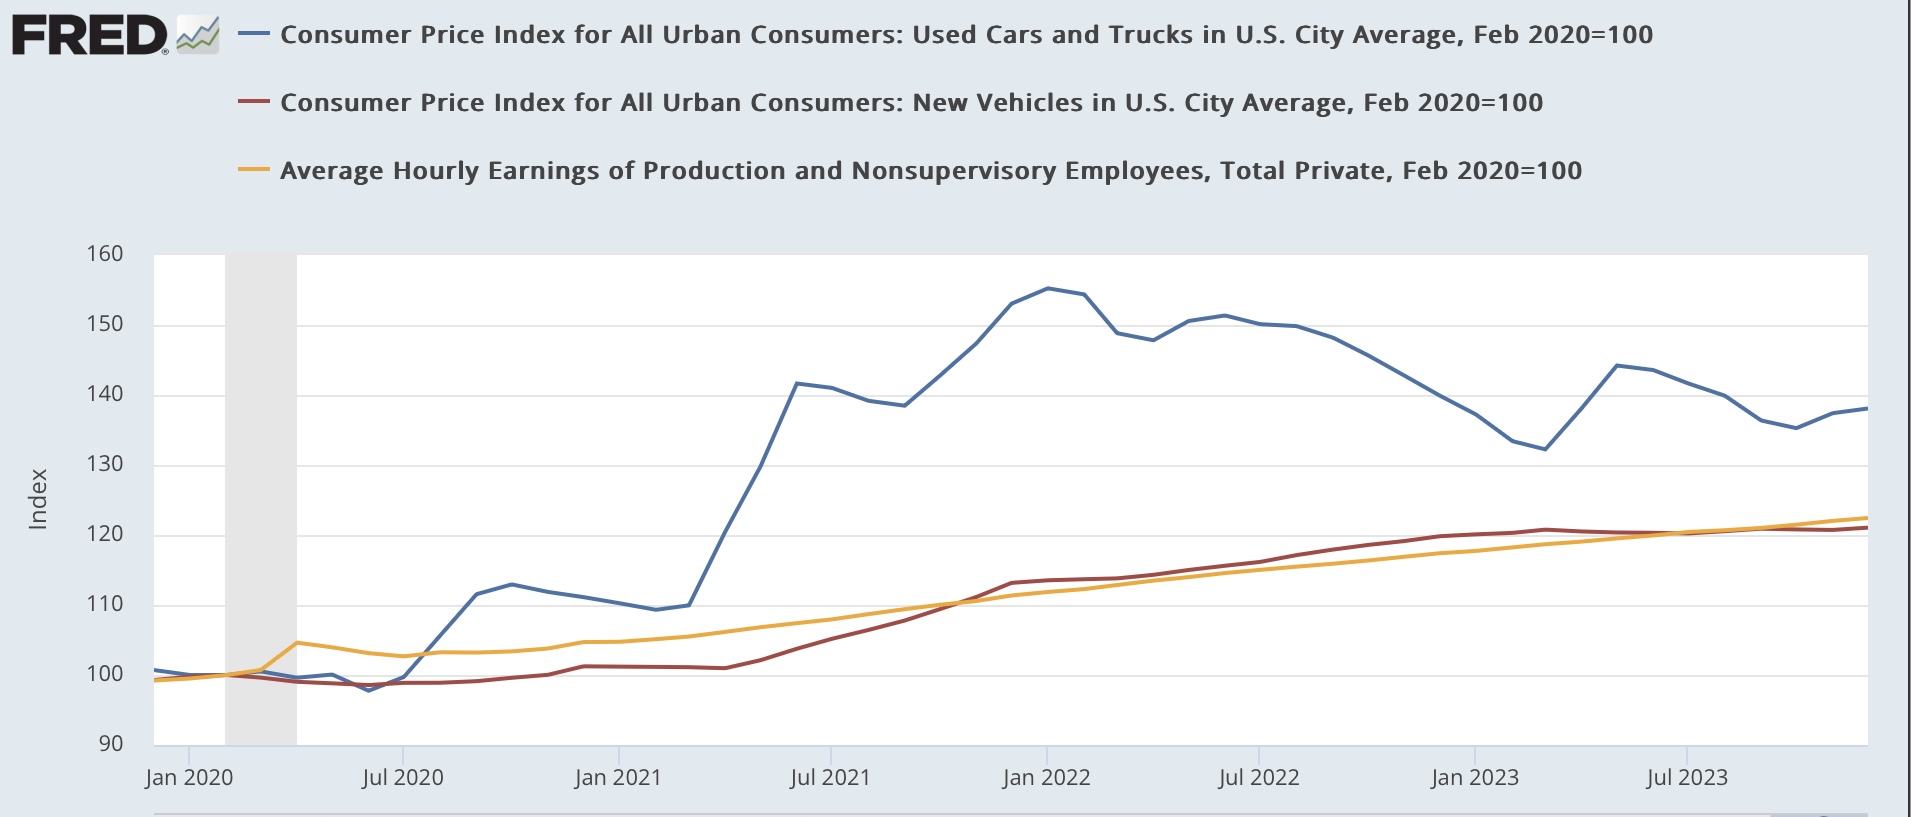
The former problem areas of new (red) and used (blue) car prices continue to cool, as the supply bottleneck for new cars and their components has eased. New car prices increased 0.3% in December, and are *down* -1.3% YoY. Used car prices increased 0.5%, reversing a declined from the previous month, and are up only 1.0% YoY. Below I show them normed to 100 as of just before the pandemic hit, and compare with average hourly wages for nonsupervisory workers (gold):


Wages have actually increased 1.3% higher than new car prices since February 2020, while used car prices, up 38.1% since then, are still about 16% higher than comparable wage growth. As a result I expect continued downward pressure on those.

The biggest current problem area is the related sector of transportation services, which includes car repairs and insurance. These only increased 0.1% in December, but remain higher by 9.5% YoY:


This has partly to do with a shortage of repair parts, and partly because vehicle owners responded to higher car prices by holding on to their older cars, which have required increasing repairs. I have also heard that there has been consolidation in the repair industry, leading to some oligopolistic price increases. Additionally, motor vehicle insurance has necessarily also increased in cost.

A second recent problem area has been food away from home, i.e., restaurants. These prices increased 0.3% in December and are higher by 5.2% YoY:


This also seems to be an issue where we can expect further downward pressure.

Finally, let’s update real aggregate nonsupervisory payrolls, an excellent indicator of the state of purchasing power. Since payrolls increased 0.2% in December, the net effect was a decline of -0.1% in this metric from its November all time high:


But it is still up 2.4% YoY. As you can appreciate, this is well within the range of noise and would only be of concern if no further progress is made.

So in summary, with the big decline in gas prices over for the moment, for all intents and purposes consumer inflation remains all about the lagged effect of house prices on the measure of shelter, which accounts for 33% of headline inflation and 40% of core inflation. We can expect that to continue to decline slowly in the months ahead, so the issue is going to be what happens with energy in particular over that time. The only negative I see is that YoY wage growth is likely to continue to decelerate, so if headline inflation remains reasonably constant, real aggregate payroll growth will probably continue to decelerate, and may stall out.

The good news on jobless claims continues


 - by New Deal democrat


The recent streak of very positive news on jobless claims continued this week.


Initial claims declined -1,000 to 201,000. The four week moving average declined -250 to 207,750. With the usual one week delay, continuing claims declined -34,000 to 1.834 million. The first two are close to their post-pandemic lows of one year ago, and continuing claims are the lowest since the end of October:


As usual, for forecasting purposes the YoY change is more important. YoY weekly initial claims are lower by -1.5%, and the four week average lower by -0.6%. While continuing claims are higher by 11.5%, this is the lowest level since last March:


This very much negatives recession in the immediate future, as is confirmed by comparing the monthly change in YoY initial claims through December, which leads the YoY change in the unemployment rate by several months:


Any triggering of the “Sahm rule” for recessions in the immediate future is off the table.

Wednesday, January 10, 2024

Sales lead employment: real aggregate payrolls update


 - by New Deal democrat


The drought in new data ends tomorrow with consumer inflation. In preparation, let’s take a look at real aggregate payrolls.


These increased 0.2% in December, one of the lower readings in the past 2 years:


On a YoY basis, aggregate nonsupervisory payrolls increased 5.8%, compared with consumer inflation in November, which increased 3.1%:


Recall that over the long term, real aggregate payrolls YoY have been an excellent coincident marker of recession:


They have typically made a rounded peak roughly 6 months before its onset. With real aggregate payrolls being up over 2.5% in November, and at a new record, the expansion has remained on solid footing.

Yesterday I posted another installment of “consumption leads jobs,” so I decided to take a look comparing real retail sales (blue in the graphs below) with real aggregate payrolls. I’ve split it up into three historical segments for better visibility.

Here is 1965 through 1993:


Here is 1994 through 2019:


And here is the post-pandemic record:


As usual, real retail sales are somewhat noisy, and the relationship is not perfect. But in general, real sales have tended to lead real aggregate payrolls by 1-2 months, especially as a smoothed average. Because of the noise, I don’t think we can use the former to forecast the latter, but because each measure independently has been generally reliable, watching them together will be particularly helpful.

I will update again tomorrow or Friday after the inflation report.

Tuesday, January 9, 2024

Scenes from the jobs report 2: the unemployment rate and consumption: weak, but not recessionary


 - by New Deal democrat


Yesterday I looked at some employment metrics from Friday’s jobs report. Today let’s look at un- (and under-)employment.


Every Thursday I repeat the mantra that jobless claims lead the unemployment rate. Here are both the U3 (blue) and U6 (red) rates from Friday’s report, compared YoY:


The unemployment rate is higher by 0.2% YoY; the underemployment rate by 0.6%.

This is actually pretty weak. Comparing historically, about 2 times out of 3, when the unemployment rate is higher YoY, you are close to or even beginning a recession.

Here’s the unemployment rate YoY from its inception in 1948 to 1994:


And here is 1994 through 2019, including the underemployment rate (which began being reported in 1994) YoY as well:


But as noted above, sometimes - e.g., 1967, 1984, 1996, 2003 - it just means weakness without a recession. Most notably, in 2003 both the U3 and U6 rates were significantly higher YoY than they are now, and while there was concern for a “double dip” at that time, there was no recession. Further, because as I’ve noted since early autumn, initial claims have been getting better, not worse, almost certainly now is one of those cases.

Another important consideration is that, just as consumption leads employment, it leads the unemployment rate as well.

Here are real retail sales YoY (blue, /4 for scale) compared with the YoY change in the unemployment rate (red, inverted so that negative means worse) from the onset of the metric in 1948 until 1994:


And here is the modern successor retail sales series through 2019:


Going back 75 years, while the data is noisy, and there are a few notable exceptions (1998-99), the YoY% change in consumption leads the YoY change in the unemployment rate by a few months.

Here is the post-pandemic trend:


YoY real retail sales turned flat in spring 2022. The YoY change in the unemployment rate got less positive starting that summer, and joined consumption as flat to slightly worse by about spring 2023. 

Real retails sales stopped deteriorating YoY last spring, and have been more or less flat YoY since summer. This tells us that the unemployment rate should stop deteriorating as well over the next few months.

Monday, January 8, 2024

Scenes from the leading sectors of the December jobs report: sectors of weakness and strength


 - by New Deal democrat


For nearly two decades, my focus on economic reporting online has been finding and examining leading indicators; those datapoints that tell us where the economy in general, and in particular jobs and income for ordinary Americans, are heading in the near future.

Usually that has meant batting away DOOOOMers; those people who always see terrible things dead ahead, usually based on an indicator they never mentioned before, and will never mention again once its forecast fails to come to fruition. 

But by the end of 2022, like for most forecasters, for me the stars appeared to be in alignment: something bad was indeed ahead. But then something akin to the reverse of THE GREAT FLAMING METEOR OF DOOM! happened: the unspooling of pandemic-related supply bottlenecks more than overcame the effects of the most stringent series of Fed rate hikes in 40+ years. For reference, here is the NY Fed’s Global Supply Chain Pressure Index for the past 25+ years:


Supply chain pressures were at their all-time highest in December 2021. They completely abated by February 2023, and were tied for their all-time loosest last May. In December they were very slightly tight, and in January reverted to very slightly loose - in other words, within their normal long term range.

So, what happens now? Does the improvement in interest rates recently mean better times ahead, or does the fact that they remains very elevated compared with two years ago mean that the tightening finally takes effect? We are in uncharted waters.

All of which is by way of introduction to the short leading indicators for employment constrained in the jobs report. One month ago I wrote that the leading internals of the report were much weaker than most commentators highlighted. 

Let’s see what happened with the December report. Last month I compared present data with long term trends. This time around I’ll use shorter term graphs, but here’s a link to the post one month ago in case you want to compare with longer term trends.

The leading data within the jobs report focuses on the manufacturing and construction sectors, the transportation bringing those goods to market, whether layoffs are increasing or not, and temporary help. That’s because service jobs generally are only affected substantially after jobs in the goods-producing, and transporting, sector are hit. 

The first metric to suffer - reliably enough that it is one of the 10 “official” leading indicators - is the manufacturing workweek. This declined to 40.4 hours in December, its first time below the modern 40.5 hour threshold that has meant contraction, and 1.2 hours below its post pandemic peak:


Only once in the past 75 years, in 1967, has a decline this much not occurred without a recession following shortly, if we were not already in one.

Manufacturing employment itself has almost always declined before the onset of a recession. For the past year, by contrast, it has been almost completely flat (blue). A significant positive has been the increase in motor vehicle production jobs, as the supply chain in that industry has unspooled (red, right scale). That segment might be peaking:


A somewhat similar dynamic has played out in construction, as residential construction employment (building houses) declined through most of 2023, before rising again to a new post-pandemic high in December; while total construction employment (led by the building of new on-shore manufacturing plants) has continued to increase throughout:


All of this has helped goods employment in total, which typically has rolled over or at least plateaued before a recession, continue to grow:


All goods produced, whether domestic or foreign in origin, must be hauled to market. Unsurprisingly, transportation employment (especially trucking) in the past has also typically turned down before a recession. Both of these peaked last May:


Like manufacturing - but unlike construction - transportation shows signs of rolling over.

Here’s what the monthly % change in goods-producing jobs + transportation jobs looks like for the 30 years before the pandemic:


And here it is for the past 2.5 years:


Not quite recessionary, but definitely weak.

Temporary help has probably also been distorted by the pandemic, as it surged well into record territory in late 2021, but has now sunk down below its immediate pre-pandemic level:


I think I would put more weight on its recent (as in, last 6 month or so) decline compared with the backing off from record levels in 2022.

Finally, whether or not layoffs have been increasing is shown by short duration (i.e., less than 5 weeks) new unemployment (blue). Typically (but not always!) these have increased for 6 months or more before a recession has begun. The series is noisier than initial jobless claims (red, right, averaged monthly) and thus it has largely been supplanted by them:


The 3 month average trend in short term unemployment has increased a little in the past 5 months, but is well within the range of noise.

In summary, we have a very weak manufacturing sector, as well as the transportation sector hauling those goods to market. This is counterbalanced by a still-strongly growing construction sector. There are further signs of weakness in the downturn in temporary hiring, and an equivocal, and noisy, slight uptick in short term unemployment. 

The more interest rates cooperate, the less likely this weakness will turn into an actual downturn, and the more likely we’ll see increasing strength.