Friday, March 17, 2023

Industrial production ‘meh’ in February, but down sharply since last summer; real manufacturing and trade sales forecast to decline in Febuary


 - by New Deal democrat


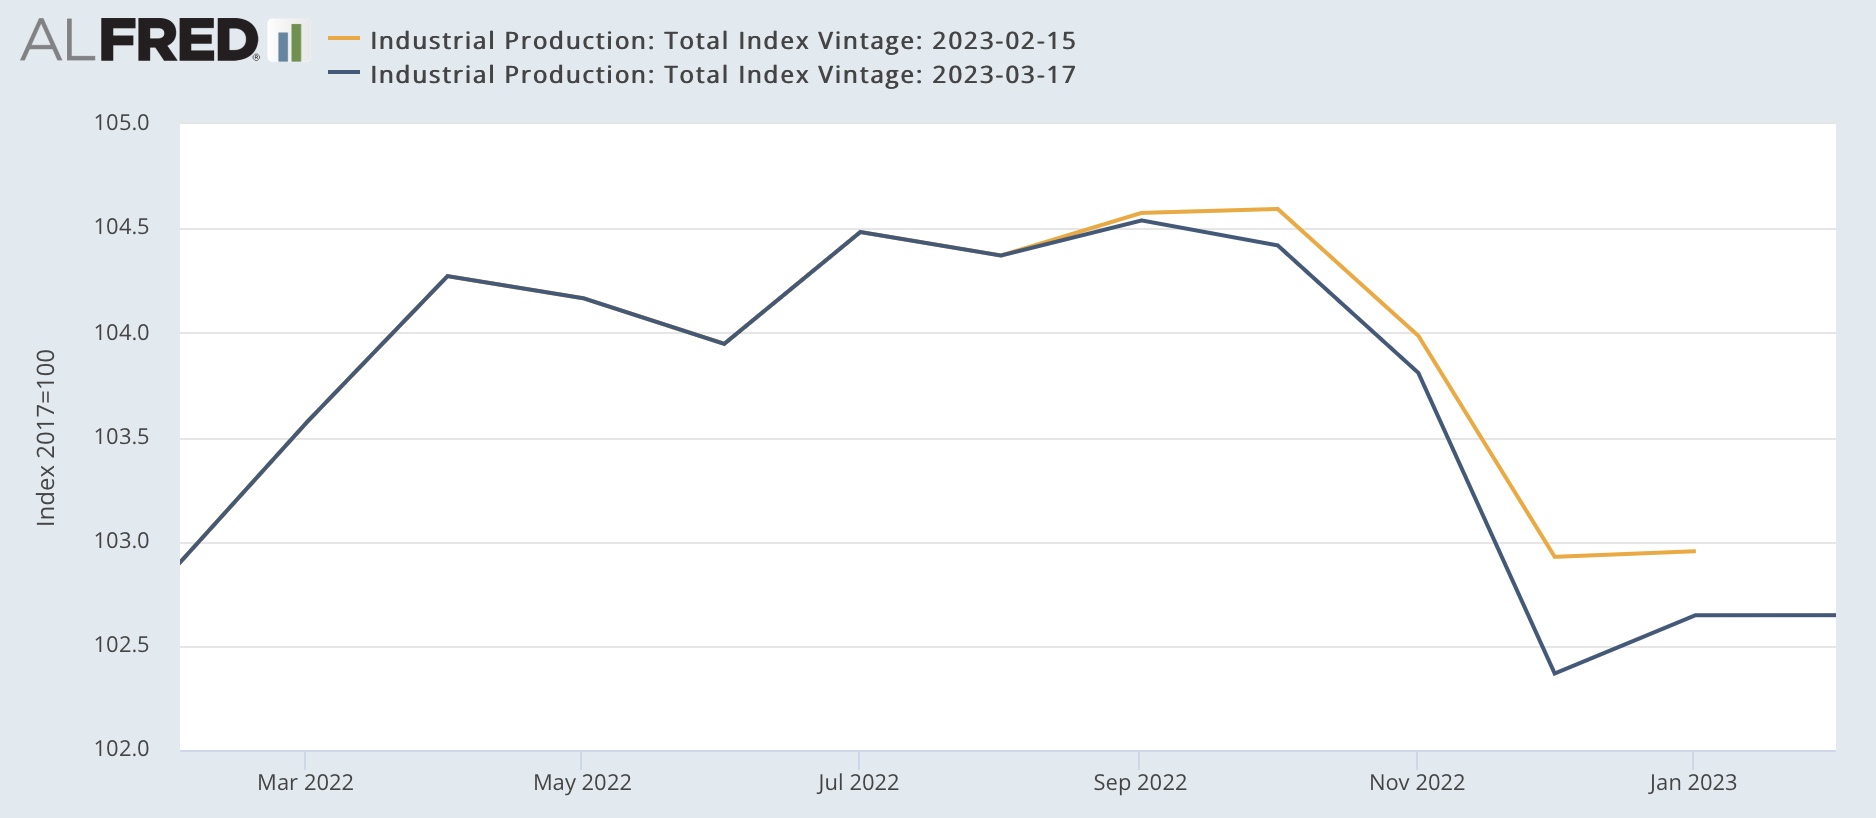
Industrial production was unchanged for the month of February, while manufacturing production rose +0.1%. But the bad news is that both were revised lower for the past 5 months, as shown on the two graphs below:


As a result, industrial production (blue below) is now -1.8% below its September peak, while manufacturing production (red) is -2.0% below its peak from last April:


With the exception of 1966, before 1990 such declines would always have been recessionary. Since then, because manufacturing has shrunk so much as a percentage of the overall economy, both in 2016 and 2019 there were bigger declines without there being a recession. Still, this is one of the 4 main coincident indicators relied on by the NBER in determining if the economy is in recession.

Industrial production is also the missing component I needed to make the first, preliminary estimate of real manufacturing and trade sales for February. 

Recall that we won’t even get the “official” measure for January until the deflators for personal income and spending are reported on the 31st. But we already have real retail sales for February, so what is missing are manufacturing and wholesalers sales for that month, minus the deflator. Industrial production fills in the manufacturing component, with the exception that we don’t know the relative inventory change vs. sales for that month.

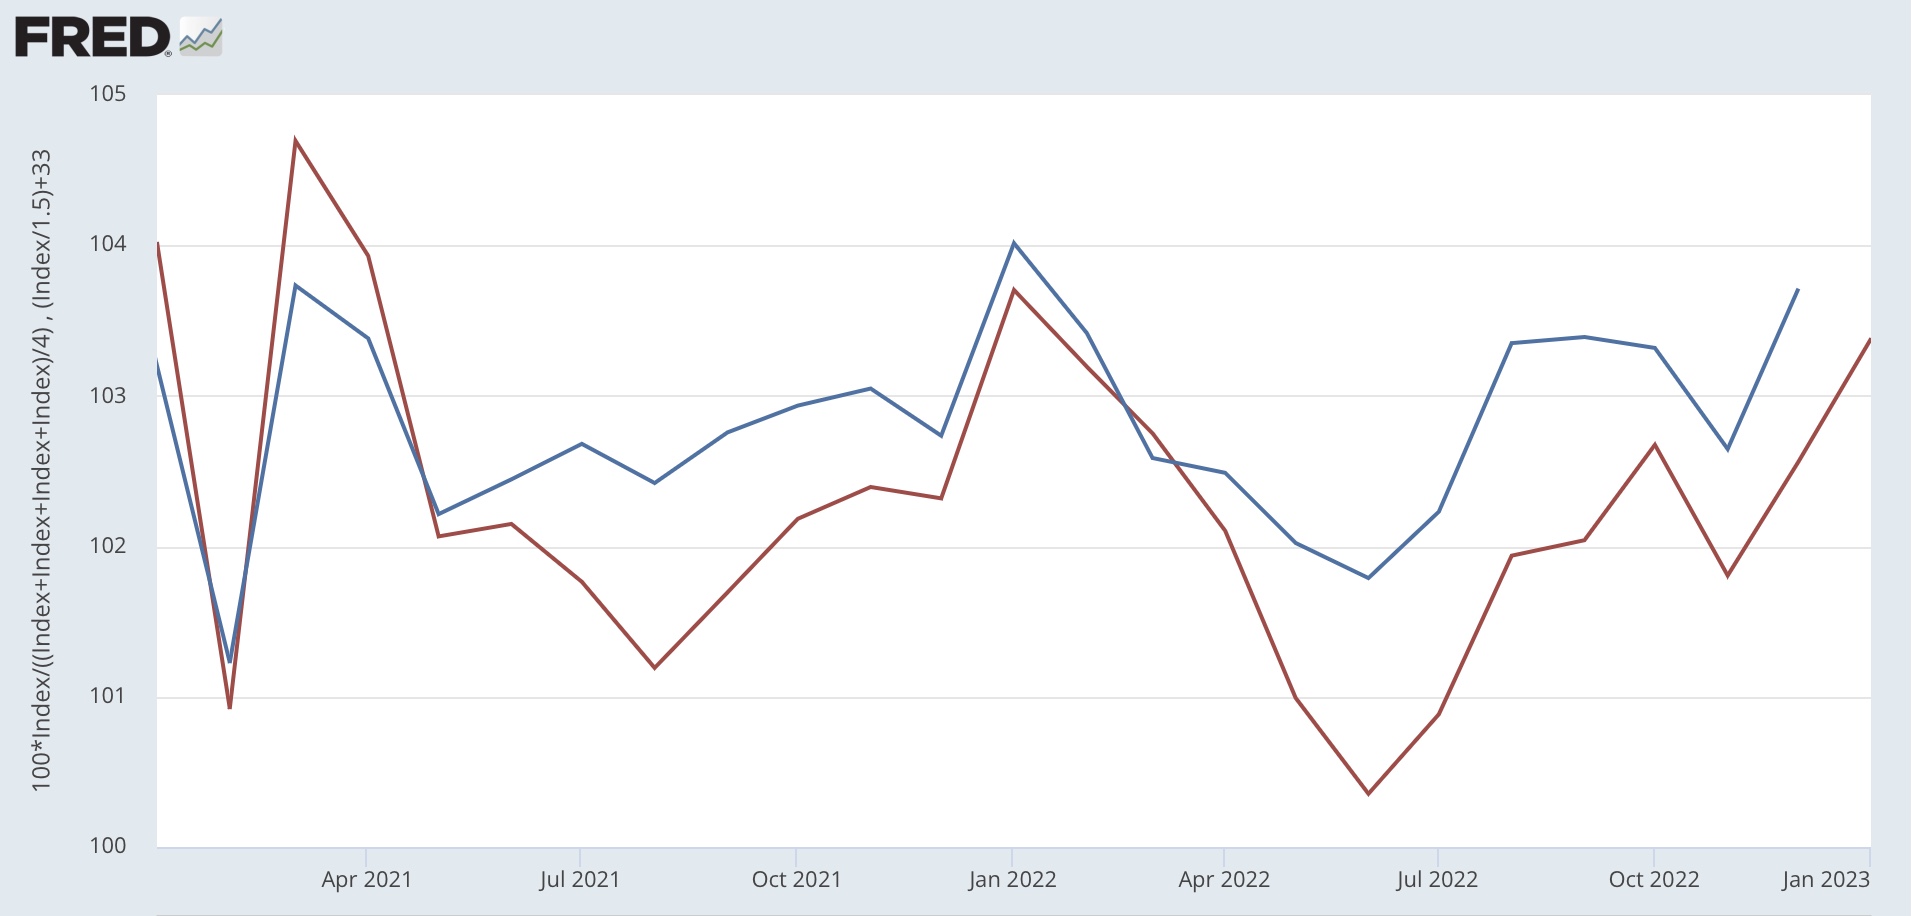
Without further ado, here is what the average of industrial production + real retail sales look like for the past 30 years compared with real manufacturing and trade sales:


Both the trend and the typical monthly change are reasonably close.

Now here is the percentage change for the last 22 months:


This method is not so accurate as the 2nd estimate I discussed several days ago, but does give us the main thrust. Like the 2nd estimate, for January it forecasts a sharp increase (+1.5% vs. the +0.8% of the 2nd estimate), followed by a -0.4% decrease in February. Like the 2nd estimate, it indicates a new record high for January.

As I wrote the other day, we’ll see how this forecast plays out on the 31st for January, and at the end of April for February. 


Thursday, March 16, 2023

Housing construction: good news and bad news


 - by New Deal democrat


This morning’s report on housing construction contained both good news and bad news.


First, the good news. Both permits (gold in the graph below) and starts (blue) increased, the former by 185,000 on an annualized rate, the latter by 129,000:


It is very possible that January’s rate of 1.339 million permits annualized and 1.321 starts will be the low for this cycle. That’s because mortgage interest rates (red, inverted), which along with Treasury yields frequently peak before the Fed finishes hiking interest rates, may very well have done so for this cycle at 7.08% in late October and early November. They declined to 6.09% by early February. As is usual, because permits and starts lag interest rates, the decline in mortgage rates showed up in the increase in permits and starts in this report.

As I have noted many times before, single family permits are the least volatile and most leading of the housing construction data, and these also rose by 55,000 to 777,000 annualized:


So much for the good news. The first bad news is that the decline which has already taken place is still consistent with an oncoming recession.

The second, more important piece of bad news is that housing under construction (red in the graph below) was revised lower for December and January, and declined further in February. It is now -1.2% off from its peak:


Since housing under construction is the “real” economic activity, this means that housing is finally putting some downward pressure on the economy as a whole. 

It isn’t that significant yet. Typically housing under construction has called more than 10% before a recession has begun. But this month’s report is confirmation that it has begun. Among other things, expect employment in residential construction, which was still increasing albeit by a very small 1,200 jobs in February, to begin to decline in the next few months.


Jobless claims: nobody is (still!) getting laid off


 - by New Deal democrat


Initial jobless claims declined -20,000 this week, back below 200,000 to 192,000. The 4 week average declined -750 to 196,500. Continuing claims, delayed one week, declined -29,000 to 1.684 million:


For all intents and purposes, it is still the case that “nobody” is getting laid off.

As the above graph shows, we are now almost one year past the lowest level of new jobless claims in history. Needless to say, this affects the YoY comparisons, which are now higher:


On a weekly basis, new jobless claims are 8.5% higher than one year ago, and continuing claims are 5.6% higher. The much more important 4 week average of new claims is 4.1% higher.

None of this is anywhere near signaling a recession warning. I would need to see the 4 week average at very least 10% higher, and lasting for longer than a month at such levels to even raise a yellow flag.

Finally, to pick up further on jobs vs. retail sales, which were reported yesterday, a corollary to the observation that consumption leads jobs is that retail sales tend to grow faster than jobs earlier in expansions, but grow slower than jobs late in expansions. The below graph subtracts the rate of jobs growth from the rate of retail sales growth to show that:


When the line is rising, sales are growing relatively faster than jobs. When the line is declining, jobs are growing faster than sales. The “zero” line in the graph is the rate at roughly the midpoint of the last 3 expansions. 

There was a huge shortfall in jobs growth compared with sales growth due to the pandemic. There has since been huge jobs growth to close that gap in the long-term trend. It is still about 4.4% from closing, historically still very wide, but declining fast. Remember that the gap can be closed by a decline in sales, an increase in jobs, or both. 

Wednesday, March 15, 2023

Forecast: real manufacturing and trade sales are likely to set a new record for January


 - by New Deal democrat


One of the four monthly series of coincident indicators most relied upon by the NBER in determining whether the economy is in expansion or recession is Real Manufacturing and Trade Sales. A significant problem with it is that reporting of the data seriously lags. For example, the result for January will only be reported more than two weeks from now on March 31, because the series relies upon the PCE deflator, which will only be reported then.


Fortunately, I have been able to decipher two methods to make earlier estimates of the series, one with less than a one month delay (which isn’t available yet for February) and I will post on separately when the relevant data comes in, and one that relies upon total business sales, which was reported this morning, to make a more reliable estimate for January.

First, let’s take a brief look at total business sales and inventories, unadjusted for inflation. Sales for January increased 1.5%, while inventories declined -0.1%:


Note that, unadjusted for inflation, sales have failed to make a new high since last June, while inventories appear to be just peaking.

A longer term view shows that this has historically been true: sales lead inventories, both at peaks and troughs:


While there have certainly been more farsighted producers, in the aggregate it appears that it is only a prolonged downturn in sales which leads to a cutback in inventories, presumably by cutting production. Hence one reason why a recession occurs.

The current data on sales and inventories, then, is consistent with an economy on the cusp of a manufacturing recession.

But now to my main point: we can make a good estimate of what real, inflation-adjusted manufacturing and trade sales will show for the month of January by using today’s unadjusted total business sales, and then deflating it by equally weighted measures of PPI for commodities, for intermediate goods, for final goods, and CPI. Because this method is slightly more volatile than the “real” method, a dampening measure is employed in the below graphs.

The below graph shows the last 10+ years of real manufacturing and trade sales (blue) vs. the estimate using total business sales deflated by PPI and CPI placeholders (red):


While it isn’t a perfect fit, the trend, including the monthly direction, is almost perfect.

Here’s what the monthly percent changes for each are for the past 21 months:


With only 2 exceptions, the direction is the same; and most often the monthly change in the “real” measures is no more than 0.2% different than the estimate.

For January 2023, the estimate is an increase of 0.8%. Here’s what that gives us zooming in on the past 2 years:


Because “real” manufacturing and trade sales for December were only 0.4% lower than their all-time record in January 2022, the estimate forecasts that when the official result is reported on March 31, more likely than not it will set a new record.

As indicated above, I’ll go further an make a preliminary estimate for February in just a few days. And of course, once the “real” number for January is reported on March 31, I’ll update with a post on how well (or not!) the forecasts performed.

Real retail sales decline in February, forecast further deceleration in jobs growth


 - by New Deal democrat


Unadjusted for inflation, retail sales declined -0.4% in February, although January’s blockbuster number was revised even higher, from up 3.0% to 3.2%. Adjusted for inflation, real retail sales fell -0.8%. The below graph, which norms this reading to 100, shows that real retail sales have essentially been flat for almost 1 1/2 years:


Nevertheless, that is still 14% higher than just before the pandemic hit 3 years ago.

The trend in the official retail sales number is confirmed by the weekly Redbook sales report, which came in at higher by 2.6% YoY earlier this week, the lowest increase since February 2021:


Redbook is not adjusted for inflation, so in real terms Redbook has been declining YoY for several months.

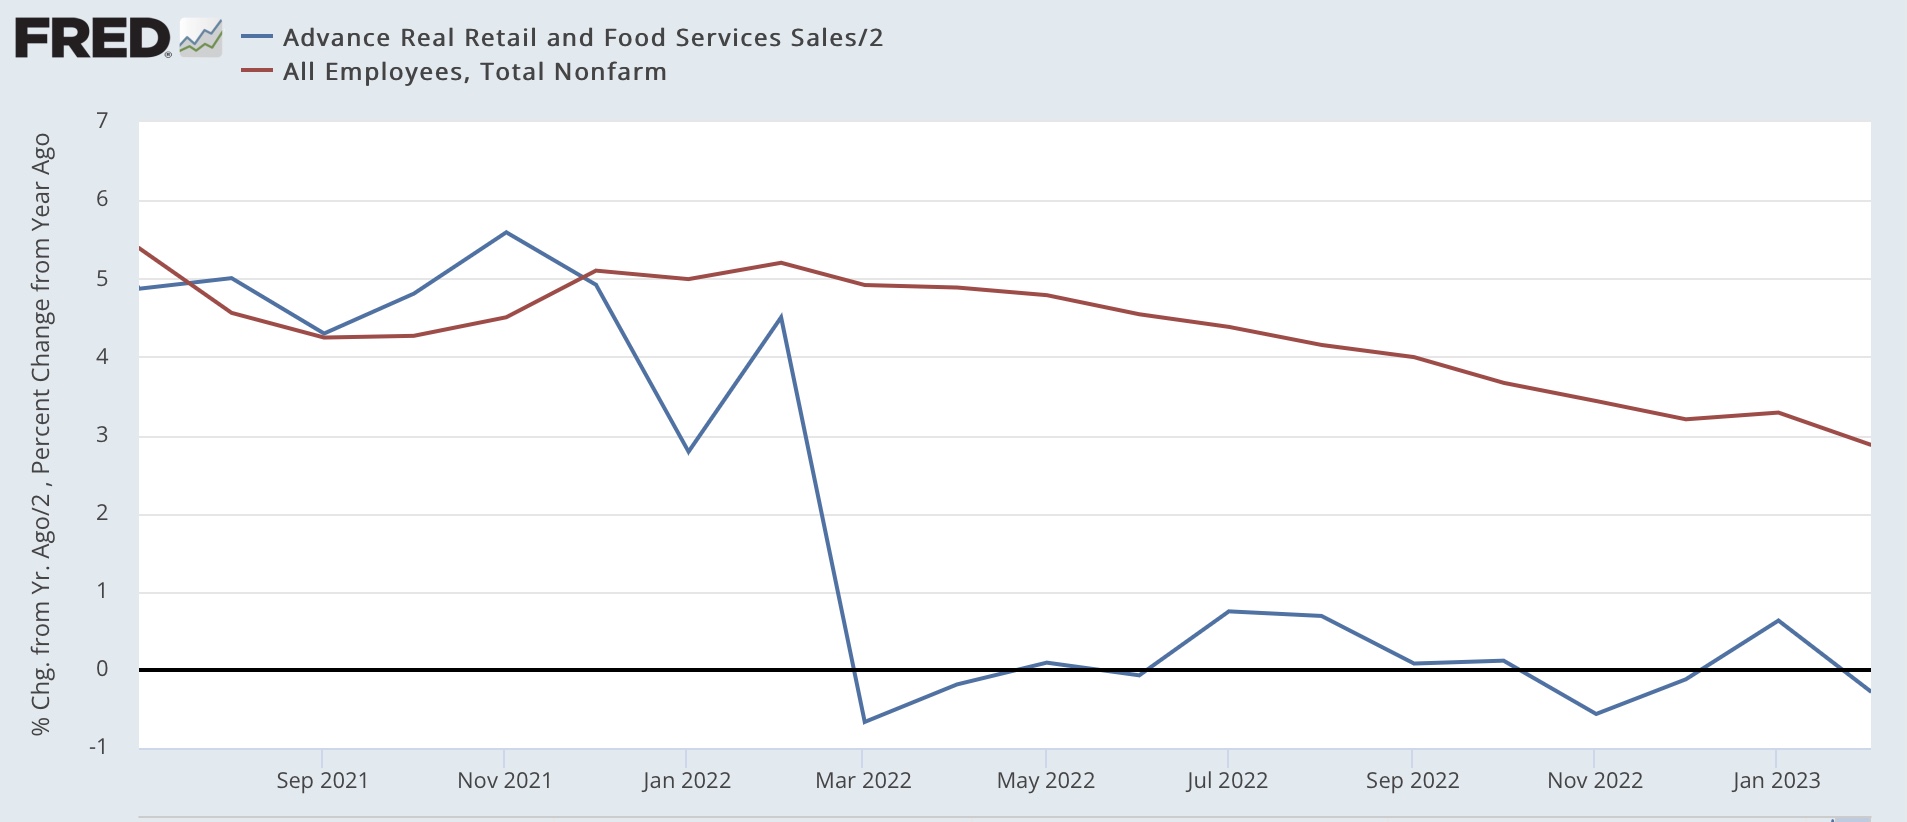
Because consumption leads employment, the YoY% change in retail sales, /2, tends to lead jobs growth. Here’s what that looks like since July 2021:


Although I have discounted the YoY declines last spring vs. the pandemic stimulus spending spree of one year before, that there has been no growth in retail sales (except for January) since last summer strongly suggests that the deceleration in jobs growth is going to continue, and perhaps even intensify. Further, a YoY decline in real retail sales has almost always correlated with the onset of a recession. The continuing growth in jobs has been the biggest contraindication of that, and is probably the only important reason we have not started into a recession yet.

In that regard, manufacturing and trade sales will also be released today. Adjusted for inflation, they are one of the 4 monthly indicators highlighted by the NBER in determining the onset of recessions. I plan on having a detailed comment later today, so stay tuned.

Tuesday, March 14, 2023

Properly measured, consumer prices have been in *deflation* since last June


 - by New Deal democrat


The majority wisdom is that the Fed is going to go ahead and raise interest rates again when it meets next week. I have been arguing for months that the data has not supported interest rate hikes. As of this morning, I am officially taking the position that, properly measured, inflation has been conquered, and the US economy has actually had price *declines* since last June.


The reason, as I have been pounding on for over a year, is that the shelter component of official inflation, which is 1/3rd of the total, and 40% of the “core” measure, badly lags the real data - as in, by a year or more. So let’s start with an updated YoY graph of the official measure of inflation, Owner’s Equivalent Rent, which increased another 0.7% in February, with the FHFA house price index (/2 for scale), which has been declining since last June through its last reading for December:


As I have repeated many time, house prices lead OER by 12 months or more. I said over a year ago that OER would drag core inflation in particular higher, even as actual house prices peaked. And that is exactly what has happened, as OER is now up 8.0% YoY, an all-time record, while the FHFA was only up 6.6% in December, and declining YoY at the rate of -1.6%/month:


Note the above graph also shows CPI less shelter, which is up 5.0% YoY. If we were to project the recent declines in the FHFA index forward through February, it would be up only 3.4% YoY. Applying the 1/3rd weight of shelter, headline CPI would only be up 4.5% YoY if actual house prices rather than OER were used in the calculation.

But that is not the most important point by any means. Because measured from last June, CPI less shelter is *down* -0.4%:


If we substitute the FHFA house price index for OER, headline CPI would have been down -1.4% as of December (since that is when the reported FHFA data ends):


If the trend of FHFA price declines since last June is projected forward into February, those would be down -1.3%. In other words, if CPI used actual house prices rather than OER, since last June headline CPI would be *down* -0.7%. UPDATE: Here’s what YoY core inflation using the FHFA house price index rather than the official shelter measure looks like through December:


Because CPI for rent has accelerated since then, but house prices have likely continued to decline, there is every reason to believe that YoY core inflation using actual house prices is now below 3%.

Indeed, with “core” inflation only up 3.4% since last June:


If we were to substitute house prices as measured by the FHFA (down at a projected trend through February of -1.2% since then) for OER, then even core CPI would be down -0.3% since then. 

To repeat my main point: properly measured - certainly for purposes of Fed action - consumer prices in the US since last June have actually been in *deflation.* Further, there is every reason to believe that by the end of this spring, even YoY CPI, properly measured, would be no higher than 3.0% - within the Fed’s comfort zone.

Before I conclude, let me briefly note 3 other sectors.

First, now that oil and gas prices have stabilized, gas prices no longer made a big impact one way or the other on CPI. But because fuel oil declined a big 7.0% in February, CPI for energy as a whole declined -0.6%. YoY energy prices are up 5.0%, but since last June’s peak are down -11.3%:


Another hot spot for inflation has been food prices. That is decelerating, if not entirely abating, as well. Food prices increased 0.4% in February, the smallest increase since April 2021:


YoY food prices remain up 9.5%:


Finally, new and used vehicle prices, another hot spot, are also generally moving in the right direction. The price of new vehicles increased 0.3% in February, while used vehicles declined -2.8%. Thus YoY new vehicle prices are up 5.8%, while used vehicles are down -13.6%:


To summarize: outside of the official measure of shelter, the only significant sector to show a price increase of more than 0.3% was food. Both headline and core inflation are only up outside of the Fed’s comfort zone because of the way shelter prices are calculated.

But whether or now OER “should” be used to calculate CPI, it most certainly should *not* be used by the Fed to determine monetary policy.  When properly measured, there has actually been *deflation* of both the headline and core measures since last June, and even on a YoY basis inflation is very likely to be within the Fed’s comfort zone in several months.

Monday, March 13, 2023

Thoughts on Silicon Valley Bank: Why the FDIC plan isn’t (but also is) a bailout; and why systemic risk remains


 - by New Deal democrat


There’s no big economic data being released today. Which I guess is fortunate, since we had a little kerfluffle over the weekend. Which may or may not be over. Herewith hopefully some commentary to put this in terms non-finance people can understand.


The really important issue for most people outside of the industry is whether or not this amounts to a taxpayer-funded bailout of wealthy VC’s and their clients. Answer: it doesn’t, but it kind of does.

First, let’s talk about why this was not a bailout. In 2008, when Wall Street investment banks were in crisis, neither shareholders nor bondholders nor senior management were cleaned out, in whole or in part. The USG stepped in and made them all whole. Had the USG not stepped in, they all would have been wiped out. That’s a bailout.

By contrast, in your typical FDIC takeover of a failed bank, senior management is out. Shareholders are wiped out. Bondholders, depending on how solvent or not the bank was, may take a haircut in whole or in part. And that is also exactly what has happened with SVB. No special exceptions were made. Nor does any part of the backstop announced by Yellen on Sunday offer any exception for future banks in similar trouble.

In short, a typical FDIC action. Not a bailout. In that regard, the only major wrinkle is that the FDIC was not able (at least so far) to find a buyer or a consortium of buyers for SVB, so it is having to operate the corpse of SVB directly.

Secondly, for the most part it was not a bailout of SVB depositors as well. That’s because it appears to be conceded by all parties that SVB had a *liquidity* problem (i.e., it couldn’t pay off all its depositors all at once) rather than a *solvency* problem (the value of its assets was insufficient to pay its debts). So, had the normal process played out, presumably all of the depositors would ultimately have received 100% of their money back. So, backstopping the depositors did not bail them out; it merely gave them access to all of their money now rather than later.

Now, let’s talk about why this *was* a bailout. The law is, bank depositors have FDIC insurance up to $250,000. Everyone knew this going in. Had this been The Bank of Depositors With No Political Clout, you can bet that the limit would have been enforced, and depositors would have to wait for their money. An exception was made because the depositors at SVB had enough political clout that they could have exacted major damage on the financial system. As the old saying goes (accounting for inflation), “If you owe the bank $1 million, the bank owns you. If you owe the bank $100 million, you own the bank.”

In short, the depositors at SVB had the risk that by law they assumed when they put their money in the bank in excess of $250k, removed. That’s a bailout.

Beyond whether SVB depositors received a bailout, the actions taken Sunday by regulators essentially assure that all future depositors for the duration of the plan will receive similar treatment.

But wait! It’s not taxpayer money, so it’s not a bailout! Well, it isn’t and it is. The Deposit Insurance Fund that will be tapped to make depositors whole is pre-funded by banks under the Dodd-Frank law. So, not taxpayer money? Well, the Deposit Insurance Fund is created by a tax. It is not the property of the banks, but property of the US Government. So it *is* taxpayer money, and to the extent banks are successful in passing on the costs of the assessment on to their depositors, it is depositors in “good” banks who are funding depositors in “bad” banks.

Beyond the issue of whether the rescue plan announced Sunday is or is not a “bailout“ of SVB (and Signature Bank of NY, and probably other banks in the near future), there is a much more important problem.

That problem is, the $250,000 FDIC limit on deposit insurance has effectively been removed, in total. 

Why is that a problem? Remember, SVB had a liquidity problem, not a solvency problem. Over the weekend, there was sufficient panic (that customers with large deposits at any bank deemed not “too big to fail” would withdraw their money today and put it in one of the banks subject to systemic stress tests under Dodd-Frank, causing those banks in turn to fail) that Treasury and the FDIC felt it necessary to step in and protect the deposits.

The precedent has been set. If Wall Street can put a gun to the head of the US financial system due to depositors’ foolish acts, and has successfully just done so, then every banker and large customer knows that the same thing will happen in the future.

And the next bank that does under may indeed be insolvent, not just illiquid. Is there anyone who seriously doubts that when that insolvent bank goes under, the same extortion won’t play out? The talking heads on CNBC last night were talking about massive bank runs today and recession by the end of this week had the FDIC not stepped in with a rescue. Those exact same arguments will be made when the next insolvent Bank of Depositors With Political Clout fails as when an illiquid bank fails. 

(And, by the way, we shouldn’t assume the crisis has been entirely averted. There are a number of other banks, and apparently at least one large brokerage, who might still be victims of bank runs, and need to tap the FDIC’s emergency fund, as early as this week).

In other words, we now have a banking system vulnerable to systemic risk where bankers and large clients know they can take reckless risks, but the FDIC will be forced to make their customers whole if the risks blow up, well beyond the $250,000 official limits of FDIC insurance.

Obviously the partial repeal of Dodd-Frank that was done in 2018 needs to be undone, at least mainly if not fully. That isn’t going to happen unless and until the next time the Democrats have a governing trifecta.

In the meantime, the threat needs to be minimized. That means ensuring that banks don’t have 95% uninsured deposits, like SVB did. It’s possible that large depositors might be forced to diversify, but I’m not sure if the FDIC, or Treasury, or the Fed has the legal authority to do so. That leaves enforcing such rules against banks themselves. In the future, bank covenants forcing loan clients to do all of their banking with the bank providing a start-up or similar loan must be subject to strict limits. In other words, a business like Roku can’t be forced by a bank to hold $500 Million in uninsured deposits with them. 

One way or another, if the $250,000 FDIC limit has gone away - and effectively it has - then the systemic risk to the system, and the risk to taxpayers to have to bail out those bank depositors with uninsured deposits, must be minimized. Until then, we’re in trouble.

Also, in the meantime, it seems *very* likely that banks will tighten lending standards further. This increases the odds that there will be a recession in the very near future.

Friday, March 10, 2023

February jobs report: the decelerating trend resumes


 - by New Deal democrat


As I’ve written several times this week, my focus on this report was on whether manufacturing and residential construction jobs turned negative or not, whether temporary jobs continued on their downward trajectory, and whether the deceleration apparent in job growth would reappear after the blockbuster January report.

Deceleration absolutely reasserted itself:


and manufacturing jobs appear to have rolled over, while construction and temporary jobs held up:


Although here too the decelerating trend is apparent. 

Here’s my in depth synopsis.

HEADLINES:
  • 311,000 jobs added. Private sector jobs increased 265,000. Government jobs increased by 46,000. The three month moving average of growth declined slightly to 351,000, still 67,000 higher than the average in December.
  • The alternate, and more volatile measure in the household report rose by 177,000 jobs. The above household number factors into the unemployment and underemployment rates below.
  • U3 unemployment rate increased +0.2% to 3.6%.
  • U6 underemployment rate also rose 0.2% to 6.8%.
  • December was revised downward by -21,000, and January was also revised downward by -13,000, for a net decrease of -34,000 jobs compared with previous reports. 

Leading employment indicators of a slowdown or recession

These are leading sectors for the economy overall, and will help us gauge whether the strong rebound from the pandemic will continue.  These were mixed, although as indicated above even the positive indicators still weakened:
  • the average manufacturing workweek, one of the 10 components of the Index of Leading Indicators, declined -0.2 hours to 40.7, down -0.9 hours from February peak last year of 41.6 hours.
  • Manufacturing jobs declined by -4,000.
  • Construction jobs increased 24,000.
  • Residential construction jobs, which are even more leading, increased by only 1,200.
  • Temporary jobs, which had been declining late last year, rose for the second month in a row, by 6,800.
  • the number of people unemployed for 5 weeks or less rose 343,000 to 2,289,000.

Wages of non-managerial workers
  • Average Hourly Earnings for Production and Nonsupervisory Personnel increased $.013, or +0.5%, to $28.42, a YoY gain of 5.3%, an increase from its previous deceleration to 5.1% in January.

Aggregate hours and wages: 
  • the index of aggregate hours worked for non-managerial workers declined -0.4%.
  •  the index of aggregate payrolls for non-managerial workers was unchanged, and resumed its deceleration to 7.4% YoY, the lowest since early 2021, although still more than 1% higher YoY than inflation as of the last reading.

Other significant data:
  • Leisure and hospitality jobs, which were the most hard-hit during the pandemic, rose 105,000, and have improved to -2.4% below their pre-pandemic peak.
  • Within the leisure and hospitality sector, food and drink establishments added 69,900 jobs, and are now only -0.9% below their pre-pandemic peak. 
  • Professional and business employment rose 45,000. This series has also been decelerating consistently, and is now up 2.7% YoY, the lowest increase since mid-2021.
  • The Labor Force Participation Rate increased 0.1% to 62.5%, vs. 63.4% in February 2020.
  • The number of job holders who were part time for economic reasons rose 17,000.
  • Those not in the labor force at all, but who want a job now, declined -211,000 to 5.103 million, compared with 4.996 million in February 2020.


SUMMARY

In absolute terms, this report was yet another solid positive report in terms of job growth. In relative terms, however, the deceleration which was apparent for most of last year resumed. 

Positive signs included growth in temporary and construction jobs, the nearly total recovery in food and drinking places jobs, resumed stronger wage growth, an increase in labor force participation, and a decline in those who aren’t in the labor force but want a job now.

Negatives included a resumption in the decline of the manufacturing work week, a decline in manufacturing jobs (plus downward revisions for the prior two months), increases ini both the un- and under-employment rates as well as short term unemployment, and an outright decline in the number of hours worked.

Deceleration was apparent in residential construction jobs, professional and business jobs, and aggregate non-supervisory payrolls.

In sum, we have further deceleration but no indication of any imminent downturn in the number of actual jobs available in the economy.

Thursday, March 9, 2023

Jobless claims, like JOLTS, consistent with softening within a strong labor market


 - by New Deal democrat


Initial jobless claims increased 21,000 last week to 211,000, still a very low number even if it is the highest since the beginning of January. The 4 week average increased 4,000 to 197,000, also still an excellent level. Continuing claims, with a one week delay, increased 69,000 to 1.718 million, tied for the highest since January 2022:


Just like the JOLTS report yesterday, continuing claims tell us that the labor market, while still objectively very strong, has softened compared with last year.

The YoY% changes also indicate relative softness, with continuing claims up 3.2%, initial claims up 6.6%, but the most important 4 week average only up 0.1%:


For initial claims to warrant even a cautionary yellow flag for recession, the 4 week average would have to be up 10% YoY. Needless to say, we’re nowhere near that marker.

Finally, initial claims are a leading indicator for the unemployment rate, typically with a lag of several months. Here is what the last 16 months look like:


In general, the unemployment rate in tomorrow’s jobs report should be within 0.1% of unchanged, and is a little more likely to increase than to decrease, given the lag compared with November and December’s increase in jobless claims.

I expect tomorrow’s report to revert to the general trend of deceleration that we’ve seen over the past year, since unlike January in February seasonally the data “expects” some hiring vs. massive layoffs as in January. I’ll be especially focusing on whether there is weakness in the leading temp help, manufacturing, and residential construction sectors. We’ll see then.

Wednesday, March 8, 2023

January JOLTS report consistent with a softening, but still very strong, labor market


 - by New Deal democrat


This morning’s JOLTS report for January, unlike the recent payrolls report, generally showed further softening in the labor market.


While hires (red in the graph below, normed to a value of 100 as of February 2020) increased 121,000, quits (gold) declined 207,000, and openings (blue) declined 410,000:


The downward trend in quits is most noticeable. Since employees voluntarily quit more, the more confident they are about new job prospects, this is a clear sign of *relative* weakening. The increase in hires is more a flattening of the trend, which had been decelerating. The trend in openings does appear to be softer, although given the increase in the last few months before January, that is more questionable.

For comparison purposes, here is the same graph covering the period since the inception of the series through 2019:


Note that all three appeared to be weakening just before the 3 recessions since 2000; but openings have continued to increase on a secular basis. That businesses may have been maintaining job postings even when they were not actively looking, but just to troll for resumes; and further that that behavior has probably been spreading throughout industry; is one reason why I do not place as much value in this series as I do in others. Still, the overall trend is useful evidence of the status of the jobs market.

Finally, layoffs and discharges increased sharply, by 241,000, in January, to their highest level since October 2020:


Here is their record before the pandemic:


Note that the current level of layoffs and discharges would be very good for any period since 2000 up until the pandemic hit.

To summarize: the January JOLTS report is most consistent with a continued very strong labor market, but one which is softening in comparison with even stronger levels during 2021-22.

A weakening of this report, particularly as to job openings, is one of the main indicators I have been looking at for evidence that broader employment metrics are beginning to capitulate. I don’t think this report puts us there in any meaningful sense. Still, in Friday’s employment report I will be focusing most intently on whether employment in three leading sectors - temporary jobs, manufacturing, and residential construction - has either continued negative (as to the first sector) or turned negative (as to the last two).

Tuesday, March 7, 2023

Coronavirus dashboard: the first year of COVID endemicity


 - by New Deal democrat


As I indicated back in January, I don’t plan on any regular COVID dashboard updates unless something noteworthy has occurred. Since we are now 1 year into endemicity, this is a good time to look back and see what that means.


The huge initial Omicron spike started in late November 2021 and ended early in March 2022. Since March 1 of 2022, here is the range of confirmed cases daily:


Confirmed cases have varied between a low of 27,400 last April 3 to a high of 140,000 on July 17. The winter Holiday wave only reached a peak of 76,800. As of yesterday, cases were 37,000. 

But with the advent of home testing over a year ago, fewer and fewer people are having the “official” tests to confirm their cases. To get a more accurate reading, Biobot’s waste particles analysis is the better metric (dotted line = 2,000 copes per mL):


At the peak of the Omicron wave, Biobot measured 4,553 particles per milliliter. By contrast, the lowest number was 40 per milliliter on May 26, 2021, at the point where we thought the initial round of vaccinations might conquer the virus.

Since March 1, 2022, particles have varied from a low of 110 particles on March 9, 2022 to a peak of 1,160 on December 28, with a close secondary peak of 1,140 on July 20. The most recent reading last week on March 1 was 460, even lower than last October’s 536. This suggests that the “real” number of daily cases has varied from about a low of 75,000 to a high of 600,000 during the Holidays.

That cases have been as high as they are is probably a combination of the nearly total abandonment of mitigation measures, plus the fact that each new variant has been indicated as inherently more immune-evasive than the last. Thus BA-1 was superseded by the even more transmissible BA-2, then the ever more transmissible BA-2.12.1, BA-5, and finally XBB.1.5, which according to the CDC is so dominant that as of last week it accounted for over 90% of all cases:


Regionally XBB varies from a “low” of 75%+ in the Pacific Northwest to over 98% of all cases in the Northeast and Mid-Atlantic. In fact, XBB.1.5 has so thoroughly transmitted through the vulnerable portion of the population of the Northeast that that Census Region now has a lower particle count than at any point since last March (dotted line = 2,000 particles per mL; Northeast is gold, West green, South pink, and Midwest violet):


Advances in treatment, the percent of the population that has been vaccinated, and increased resistance from prior infections has meant that hospitalizations, which reached a peak of over 160,000 during the Omicron wave, have varied between just below 10,300 last April 5 to a peak of 47,500 this January 3, with a secondary peak of 46,400 last July 25. Currently hospitalizations are at a new 11 month low of 22,800, just below last October’s 22,900:


Which brings us, finally, to deaths, which during last March were still declining from their Omicron peak of 2600 per day in January 2022. Since then they have varied from a low of 234 at the end of November to a high of 642 in January:


Currently deaths average 371 for the past week.

Deaths during each of the first two years of the pandemic totaled about 500,000. Since April 1 of last year, total deaths have increased by 139,000, for an annual rate of 150,000. While this is the equivalent of a very bad flu season, that masks the fact that vulnerability to dying from COVID is very much a factor of immunization status and age.

Here is the death rate by vaccination status for all age groups in total since the start of the pandemic:


In general the unvaccinated are more than 10x as likely to die from COVID as are the unvaccinated.

But age is also a huge determinant. Here are the death rates by various age groups, broken down into vaccinated vs. unvaccinated.

Age 80+:


Age 65-79:


Age 50-64:


Age 30-49:


Age 18-29:


As you can see, regardless of vaccination status, risk rises steeply with age. A fully vaccinated senior is almost as likely to die of COVID as is an unvaccinated person age 50-64.

To summarize: in the first year of endemicity, case rates have averaged 1 person in 1000 each day, varying between a low of 1 in 4000 to a high of 1 in 500. Hospitalizations have ranged between roughly 10,000 to 50,000 per day (well below the crisis point of roughly 150,000 per day). Deaths have ranged between roughly 250 to 600 per day (vs. 1000 to 2600 during the first 2 years of the pandemic), heavily skewed towards the unvaccinated and the aged. 

Finally, if we break down seniors between roughly 7 million unvaccinated and 57 million vaccinated, with about 75,000 of the former dying in the past 12 months and 30,000 of the latter, we get a death rate of 1 in 1000 for the unvaccinated and 1 in 20,000 for the vaccinated. Over the next 10 years, if that were to continue, unvaccinated seniors have a 1 in 100 likelihood of dying from COVID, while the unvaccinated have a 1 in 2000 likelihood for dying from the disease over that period.