Monday, April 8, 2019

I told you so: the March employment report showed a slowdown in the leading sectors


 - by New Deal democrat

For the past few months, I have been forecasting a jobs slowdown. That has been based in part on the natural progression of a downturn in long leading indicators, then short leading indicators, and finally to coincident indicators of which jobs along with industrial production are the Queen and King, respectively.

Further, I have pointed out that, even when the spread between short and long term bonds simply gets tight, even if there is no outright inversion, employment growth almost always falters. And goods-producing employment - including manufacturing and construction jobs - has *always* faltered in the past 60 years.

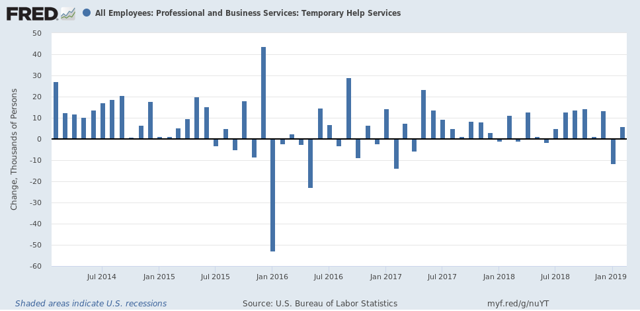
Finally, since temporary jobs are a well-known leading indicator for jobs as a whole, I have been expecting them to slow down if not turn down.

March’s jobs report  delivered all of this in spades.

But I received a little blowback on this point, suggesting that the declines were trivial or that I was retrospectively cherry-picking to support a Doomish hypothesis. Far from it: this is something I’ve been forecasting for months in specific sectors, and in the last three months, even in the face of big overall employment gains, it has shown up.

So, to set the record straight, before I get to the March graphs, let me recap the literally 15 times I warned of a coming slowdown in manufacturing, construction, and temporary jobs, and in the goods sector  generally. If you don’t want to read the “I told you so” part, just scroll right past number 15 to the bolded headline and you’ll get right to the March jobs graphs.

The 15 times I forecast an oncoming slowdown in leading employment sectors

1. Last August: the simple tightening of the yield curve suggests a subsequent jobs slowdown
Four times during the 1980s and 1990s the difference in the interest yield between 2 and 10 year treasury bonds got about as low as it is now [Note: i.e., August 2018] (blue in the graphs below). That occurred in 1984, 1986, 1994, and 1998.   
Even though on none of those 4 occasions a recession followed, on 3 of 4 of those occasions YoY employment gains ... subsequently declined ...  
In other words, even if the Fed stops raising rates now [as of August 2018], and the yield curve does not get tighter or fully invert, my expectation is that monthly employment gains will decline to about half of what they have recently been -- i.e., to about 100,000 a month -- during the next year or so.
2.  In January, discussing The consumer nowcast and economic forecast
Keep an eye on these three areas (new orders, temp hiring, and new jobless claims). If these turn outright negative, that will be a very strong sign that poor public policy is causing what otherwise would just be a slowdown to tip all the way into recession.


Unsurprisingly, building permits lead construction employment. The lead time between the former turning negative YoY vs. the latter has varied between 5 and 23 months, but usually has been between 10 and 14 months. Currently, with the exception of one month, permits have been negative YoY since August.  
[C]onstruction employment has usually turned down YoY before a recession....

The number of manufacturing jobs themselves has also turned down in advance of recessions ever since 1974. 

...the absolute number of manufacturing jobs reliably decelerates from peak before a recession begins, and usually declines, even if the YoY change does not turn  negative.
At present, while the manufacturing work week has declined in recent months, the absolute number of manufacturing jobs has not followed.
The second conclusion, building on my last post concerning construction jobs, is that with the sole exception of the oil shock of 1974, no recession has ever started without at least one of the two - construction or manufacturing jobs - having moved down first.

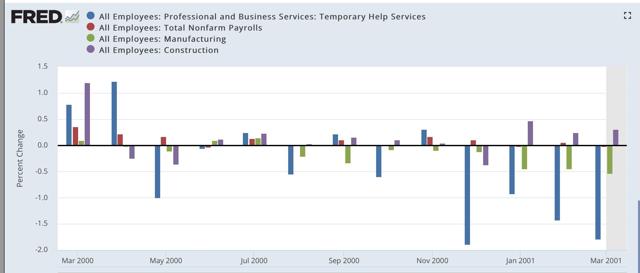
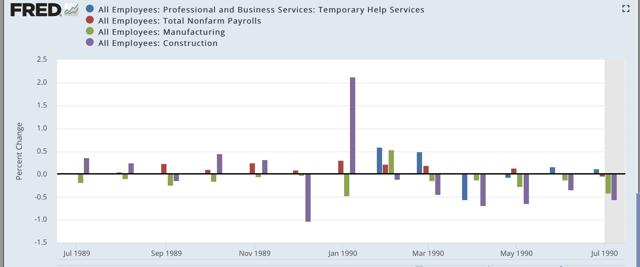
5. I followed that up with a post showing how manufacturing, construction, and temporary jobs have led the overall jobs numbers prior to each of the last three recessions, including the following three graphs .


1989-90

2000-01


2006-07
If the poor December ( retail sales) number isn’t revised away, or reversed by a big gain in the next months’ report, this portends a significant deceleration in jobs growth in the monthly employment reports over about the next 6 months.
All of which makes me think that the deceleration of temp jobs in the monthly report for the last three months, ... hasn’t just been noise, but - while still positive - is demonstrative of real weakness.
The bottom line is that almost all of the other economic data has been validating the “slowdown” forecast I made beginning last summer, and I expect employment to follow — and temporary jobs will probably lead the way.
Tomorrow I am looking for continued gains in both manufacturing and construction, but a cooling in manufacturing vs. continued trend growth to a slight deceleration in construction.  In both cases this means gains of less than 30,000, and possibly as low as 5,000. Because the economy is slowing, and this should show up in jobs numbers, if there is a surprise in either or both, it will likely be to the downside.
Finally, I expect YoY overall jobs growth to begin to decelerate from its peak last month:

this month’s report actually went beyond taking back January’s report. The YoY change in construction, manufacturing, and total jobs for the last two months combined are all lower than they were in December.  

In summation, I suspect this month marked the first month in which the economic slowdown showed up in the jobs report.


The bottom line is that, even averaging January with February, all of the leading employment indicators show some deterioration, but none of them are at a point where I would expect them to be if a recession were imminent.

...Even if the Fed starts to lower rates soon, I strongly suspect that January was the YoY peak in employment, and we have started down the road to roughly 100,000/month employment gains - if not worse - later this year. 

After the 2015-16 shallow industrial recession, the growth in temp jobs picked up decently. But in the last four months, only about 2250 temp jobs per month have been added. I am looking for this decelerating trend to continue, and the decline in the Staffing Index indicates we shouldn’t be surprised if there is an outright loss in temp jobs in the report on Friday.

15. Pointing out that A tight or inverted yield curve has always led to a stall or downturn in goods-productions jobs, in the context of what to watch for in the March jobs report: 

Note that in *every* case that the interest rate spread has inverted, or just decreased to nearly zero, within about 18 months YoY growth in goods-producing jobs has declined to less than 0.5%, and usually outright declined. That translates to an annual pace of not more than 7000 goods producing jobs a month. By contrast, in the past several years at least 20,000 goods productions jobs have been addedvirtually every month ...

So if history is a guide, a sharp slowdown in goods producing jobs growth should begin  very soon, if not having already begun in February.

To the graphs:  the jobs reports in the last three months have borne out my forecast for a deceleration or decline in the leading semployment sectors


First, here is a m/m graph of manufacturing, construction, and temporary jobs, all of which are leading sectors for jobs as a whole:
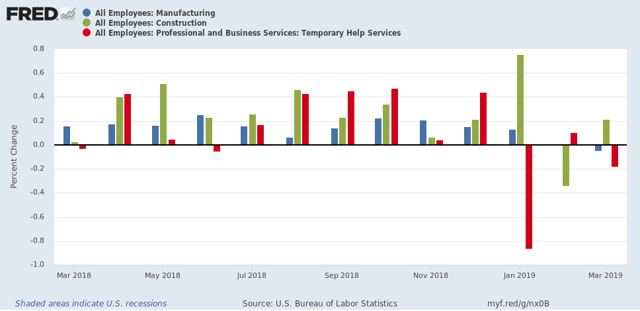

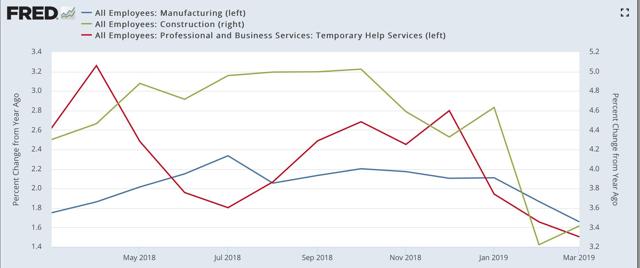
In the past three months, all three have faltered, with decelerating or outright declines in jobs. Note how similar this looks to the trend in the three pre-recession graphs of these sectors I posted under article #5 above.

Here is the YoY look at the same three sectors, showing that all three have decelerated substantially:

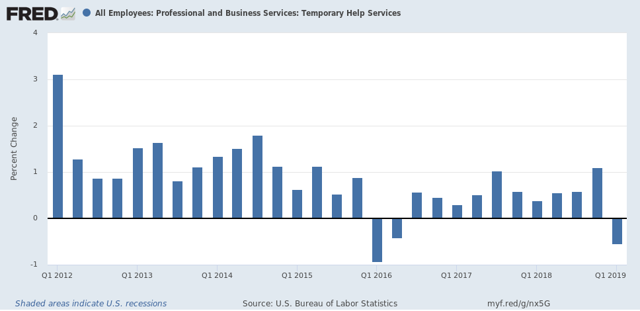
On a six month basis, temporary jobs are up by 500 out of 3 million! Here are the quarterly numbers, showing that Q1 of this year marked the first decline, aside from the downturn of 2015-16, since the end of the Great Recession: 
By the way, if you don’t believe me that temporary jobs are a leading sector for jobs overall, then how about University of Oregon Professor Tim Duy, who wrote in connection with Freiday’s report that it contained “A Hint of Weakness;”

 On the surface, this is another “Goldilocks” report – strong job growth, low and steady unemployment and nothing in the wage data to support inflation concerns. A hint of weakness, however, is visible in the temporary help numbers:

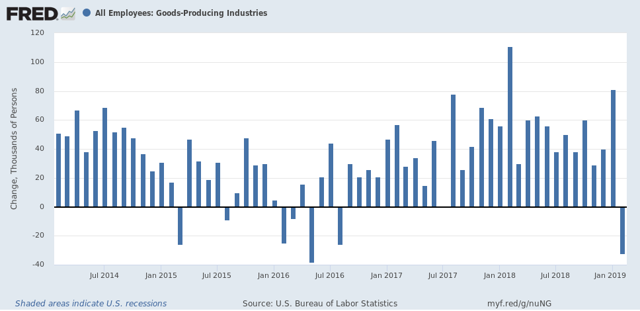
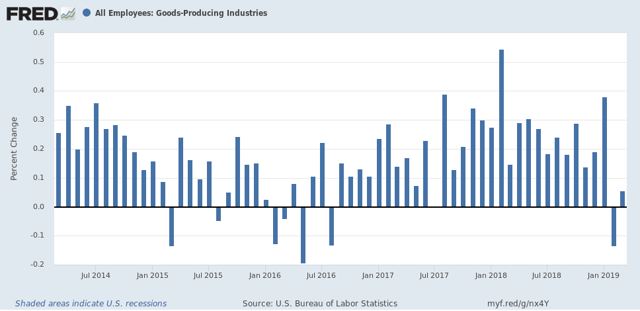
Next, here are goods-producing jobs (which include but are not limited to manufacturing and construction). Last week I wrote that I expected these to slow down to a rate of +7000/month. In the past two months, there was a loss of -28,000 in February, followed by a gain of +12,000 in March:

Here is the YoY look:
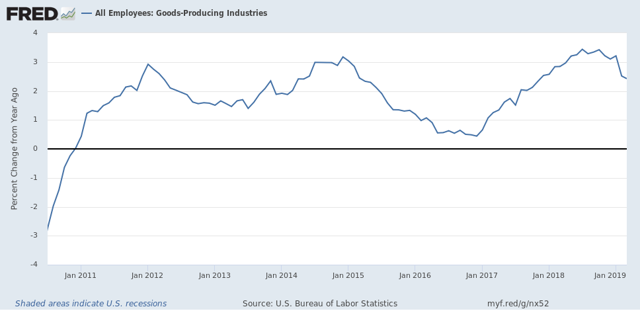

The last two months average to -8,000 per month.

Next, here is the YoY% change in nonfarm payrolls, showing a deceleration in the past two months:
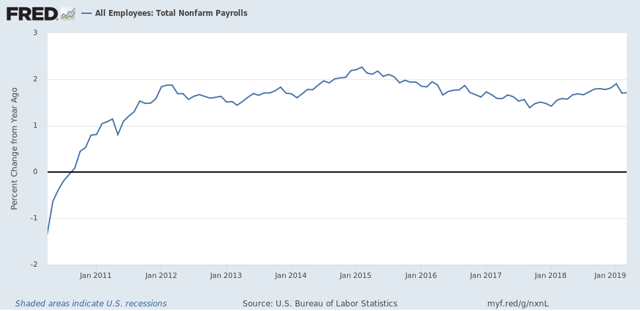

This is as I forecast.

Here is a comparison of YoY changes in nonfarm payrolls as measured b the establishment report vs. jobs as measured by the household report:
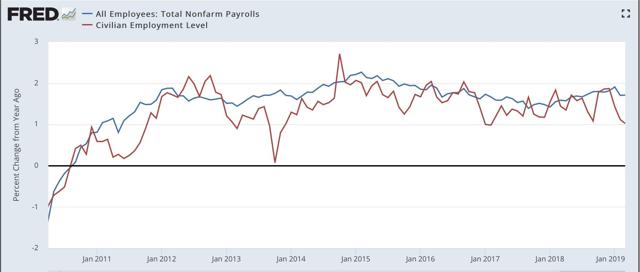

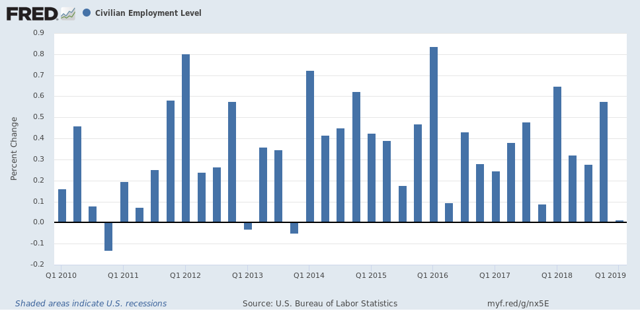
What is noteworthy is that, at turning points, it appears to be the case that the household report gives warning first. in that regard, this past month was one of the worst 4 months in the past 9 years:


Finally, here is a graph of the quarterly changes in employment since the beginning of 2018.  Jared Bernstein, who is convalescing from a stroke, typically compares the 3-, 6-. And 12-month average in employment growth to show the trend:
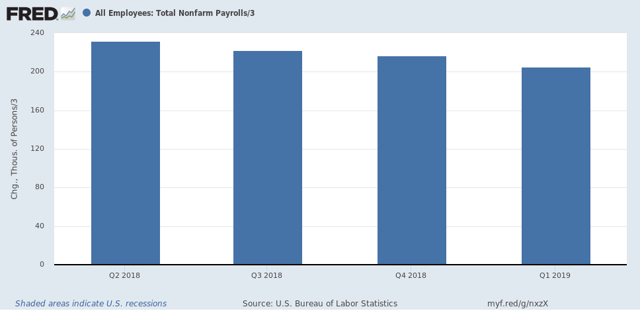

Here are the numbers:

3 month average: 205,000
6 month average: 208,000
12 month average: 219,000

This shows a slow decline in the job growth trend overall.

In sum, for three months I have been pounding the table to watch the leading sectors of manufacturing, construction, and temporary jobs.  The three months since, including Friday’s jobs report, give every appearance of heralding the jobs slowdown I have been forecasting.

Saturday, April 6, 2019

Weekly Indicators for April 1 - 5 at Seeking Alpha


 - by New Deal democrat

My Weekly Indicators post is up at Seeking Alpha.  Interest rates ticked up this week, which brought the readings on some interest rate indicators back down.

As usual, clicking over and reading helps reward me with a little $$$ for my efforts.

Friday, April 5, 2019

March jobs report: good nowcast, concerning forecast


 - by New Deal democrat

HEADLINES
  • +196,000 jobs added
  • U3 unemployment rate unchanged at 3.8% 
  • U6 underemployment rate unchanged at  7.3%

Leading employment indicators of a slowdown or recession

I am highlighting these because many leading indicators overall strongly suggest that an employment slowdown is coming. The following more leading numbers in the report tell us about where the economy is likely to be a few months from now. With one exception, these either decelerated or outright declined.
  • the average manufacturing workweek was unchanged 40.7 hours. This is one of the 10 components of the LEI. It is down -0.6 hours from its peak during this expansion.
  • Manufacturing jobs declined by -.6,000. YoY manufacturing is up 209,000, a big deceleration from last summer’s pace.
  • construction jobs rose by 16,000. YoY construction jobs are up 246,000, also a big deceleration from last summer.   
  • temporary jobs declined by -5400. YoY these are up +44,900. These are only up 3700 in the past 5 months, a big slowdown.
  • the number of people unemployed for 5 weeks or less fell by -68,000 from 2,194,000 to 2,126,000.  The post-recession low was set 10 months ago at 2,034,000.

Wages and participation rates

Here are the headlines on wages and the broader measures of underemployment:
  • Not in Labor Force, but Want a Job Now: increased by 5,000 from 5.222 million to 5.227 million
  • Part time for economic reasons: increased by 189,000 from 4.310 million to 4.499 million
  • Employment/population ratio ages 25-54: declined -0.1% from 79.9% to 79.8%
  • Average Hourly Earnings for Production and Nonsupervisory Personnel: rose $.06 from  $23.18 to $23.24, up +3.4% YoY.  (Note: you may be reading different information about wages elsewhere. They are citing average wages for all private workers. I use wages for nonsupervisory personnel, to come closer to the situation for ordinary workers.)  

Holding Trump accountable on manufacturing and mining jobs

 Trump specifically campaigned on bringing back manufacturing and mining jobs.  Is he keeping this promise?  
  • Manufacturing jobs rose an average of +22,000/month in the past year vs. the last seven years of Obama's presidency in which an average of +10,300 manufacturing jobs were added each month.   
  • Coal mining jobs rose by 100 for an average of 150/month vs. the last seven years of Obama's presidency in which an average of -300 jobs were lost each month
January was revised upward by 1,000. February was also revised upward by 13,000, for a net change of 14,000.

Other important coincident indicators help  us paint a more complete picture of the present:
  • Overtime declined -0.1 hour to 3.4 hours.
  • Professional and business employment (generally higher-paying jobs) increased by 34,000 and  is up +534,000 YoY. This has also decelerated from last year’s pace.
  • the index of aggregate hours worked for non-managerial workers rose by 0.5%
  •  the index of aggregate payrolls for non-managerial workers rose by 0.7%  
Other news included:            
  • the  alternate jobs number contained  in the more volatile household survey declined by -201,000  jobs.  This represents an increase of 1,158,000 jobs YoY vs. 2,537,000 in the establishment survey. This is a big difference and, because the household survey has a tendency to turn first, is a definite concern.    
  • Government jobs rose by 14,000.
  • the overall employment to population ratio for all ages 16 and up declined -0.1% from 60.7% to 60.6% m/m and is up 0.2% YoY.          
  • The labor force participation rate declined -0.2% from 63.2% to 63.0% and is up +0.1% YoY.

SUMMARY

The headline jobs number was very good, although a little below the pace of last year. But the internals were generally neutral to negative.

To begin with, all three of the jobs sectors I am watching closely - construction, manufacturing, and temporary jobs - showed a marked slowdown in growth. All three have declined over the last two months, and temporary jobs are at a virtual standstill over the last five months. Another source of concern is that the household survey’s number showed an outright loss of jobs for the month, for the second time in four months. This measure has grown by only an average of 130,000 per month for the last year. All of this heightens concern that a big slowdown in jobs growth has probably already begun.

Unemployment, underemployment, labor force participation, and the prime age employment/population ratio all either stalled or, in the last case, declined slightly.

On the bright side, wages for ordinary workers grew at 3.4% YoY, a slight slowdown from their recent best pace. Perhaps the best news was the continued strong pace of growth in aggregate hours and payrolls.

To sum up, the jobs nowcast is very good. The jobs forecast is for a significant slowdown, the scope of which is not clear yet.

Thursday, April 4, 2019

March news good so far; the Fed has plenty of scope to cut rates


 - by New Deal democrat

While we are waiting for tomorrow’s jobs report, let’s step back for a moment and look at where we are in the big picture of the economic cycle.

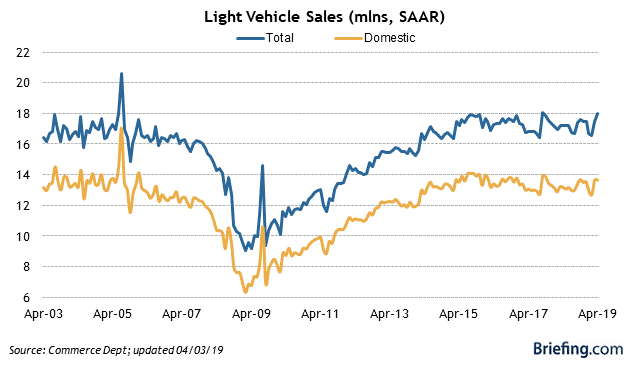
So far, March data is running pretty positive.  In addition to the decent ISM manufacturing report I discussed the other day, motor vehicle sales turned out to be excellent, topping 18 million annualized:


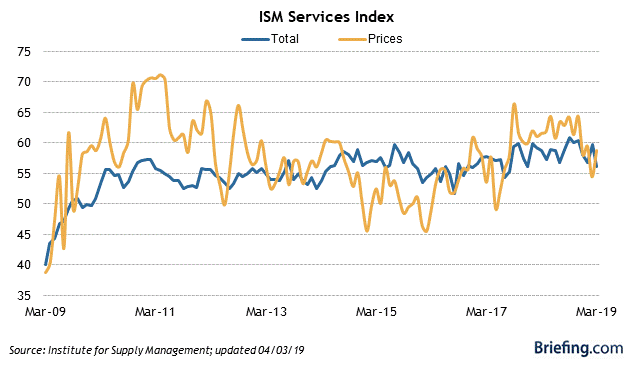
The ISM services index, like the manufacturing index, also downshifted, but continued positive:


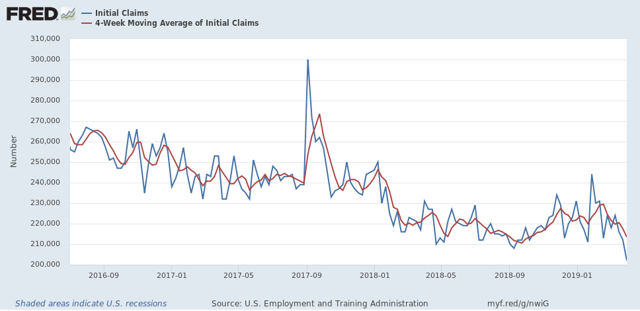
And this morning, new jobless claims for the prior week made a new expansion low:


The last time jobless claims were this low was almost exactly 50 years ago, in December 1969. At 213,500, the 4 week average wasn’t quite as low as September’s 206,000, but aside from that, also last saw this number in December 1969.   

So the short leading and the coincident data so far for March indicate an expansion that is doing nicely, if not at the pace of last summer.

That does not mean “ALL CLEAR,” however. The long leading indicators generally deteriorated all through 2018, and those forces can be expected to press down on the economy for the rest of this year.

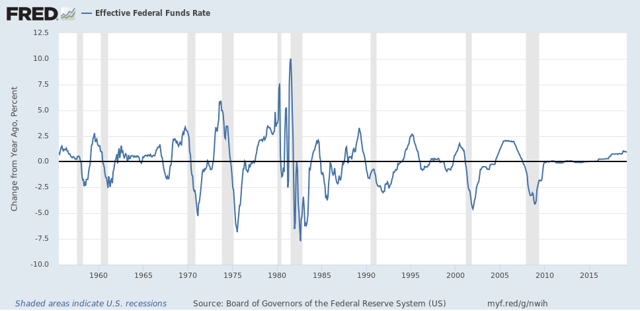
The reason for the most optimism about the economy going forward, aside from the recent decline in long term interest rates like mortgages, is that the Fed’s rate hikes occurred at such a leisurely pace, totaling 0.75% in 2017 and 1.0% in 2018, unlike most prior tightening cycles that increased at levels of 2.0% YoY or more:


Because the impact of each 0.25% rate hike is less than 0.5% rate hikes, and because they were so gradual, this means that any overshoot is likely less than usual, and also gives the Fed plenty of time to react to any such overshoot.

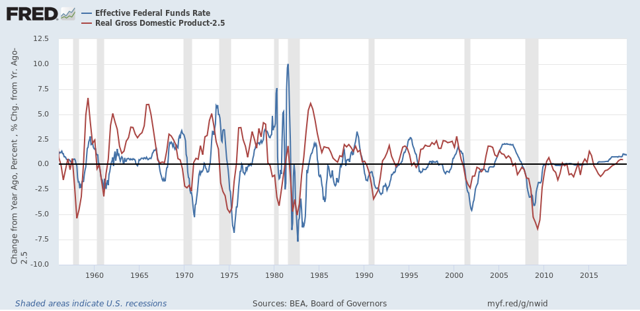
Typically the Fed has only begun to curtail its tightening cycle or loosen rates 6-12 months after the maximum YoY real GDP growth (red in the graph below) (from which I’ve subtracted 2.5% to show the relationship better):


Since the recent YoY peak was Q3 of last year, the Fed is right on time with its pause. If data continues to weaken, so long as inflation - lately up only 1.5% YoY - remains subdued, the Fed need not worry about prices overheating. With gas prices still $0.01 less than they were a year ago, a spike in inflation in the next few months looks very unlikely, which gives the Fed plenty of space to cut, and avoid a recession.

Wednesday, April 3, 2019

Watch for temp jobs weakness in Friday’s employment report


 - by New Deal democrat

Yesterday I looked at manufacturing jobs, and goods-producing jobs generally, as two what to look for in Friday’s jobs report.

Today let’s follow up with temporary jobs, an acknowledged leading indicator for jobs as a whole.

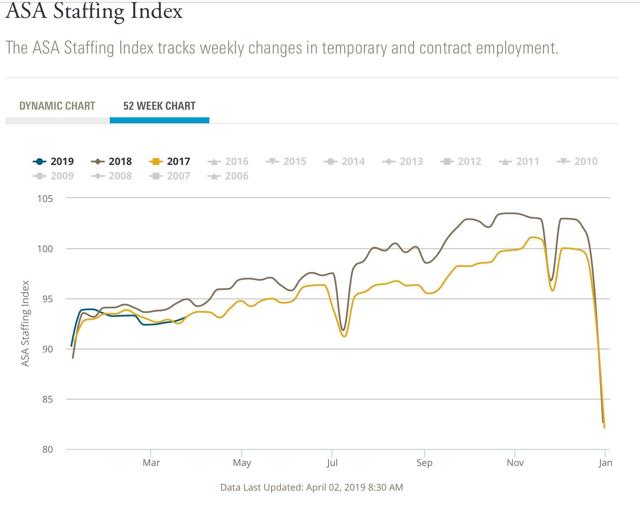
As I wrote about a couple of months ago, the American Staffing Association’s Staffing Index does a good job forecasting the trend in temporary jobs in the monthly employment report.

And here, the news is becoming slightly, but more and more, negative. In the four week period through the end of March, the YoY comparison slipped to -1.7%, its worst yet:

The index went negative YoY at the turn of the year, and has gradually deteriorated since.

Meanwhile here is the monthly change in temporary jobs from the employment report for the past several years:


After the 2015-16 shallow industrial recession, the growth in temp jobs picked up decently. But in the last four months, only about 2250 temp jobs per month have been added. I am looking for this decelerating trend to continue, and the decline in the Staffing Index indicates we shouldn’t be surprised if there is an outright loss in temp jobs in the report on Friday.

Tuesday, April 2, 2019

Manufacturing slowdown apparent, but no contraction


 - by New Deal democrat

With yesterday’s ISM report for manufacturing in March, let’s take an updated look at this sector, with a particular emphasis on what to look for in this Friday’s jobs report.
    
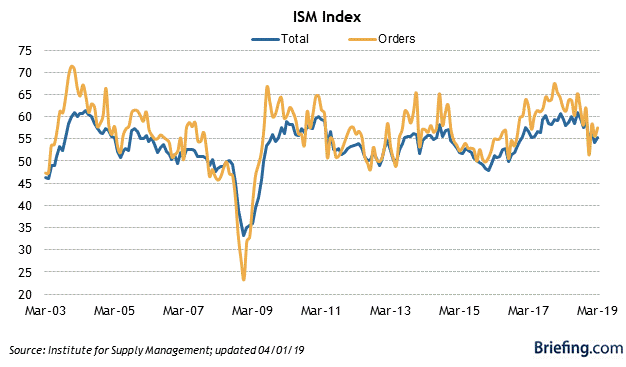
The ISM manufacturing index, and its more leading new orders sub-index, both continued positive in March, with the former at 55.3 and the latter at 57.4. Both of these are good, solid, positive numbers. Here’s the updated graph from Briefing.com:


Although as noted above, these are positive numbers (any value above 50 indicates expansion), the last few months have shown a considerable slowdown from the red hot pace of expansion one year ago. This is in line with the five regional Fed reports, which have also slowed to very tepid - but still positive - readings in the last few months.

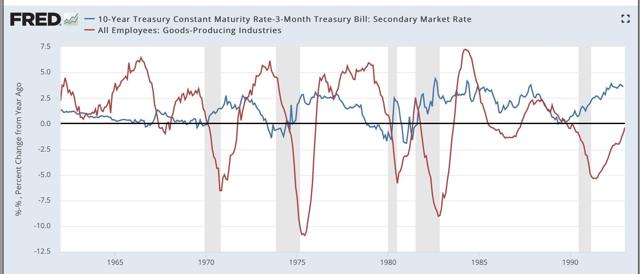
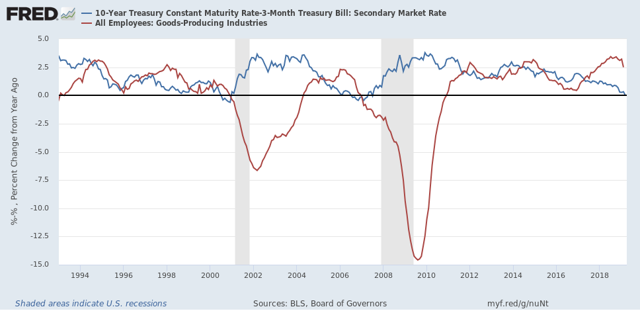
As I wrote last week, I am expecting a slowdown in employment growth. This is particularly true as to manufacturing and other goods-producing jobs. Here’s two graphs going back nearly 60 years of the spread between 10 year and 3 month treasuries (blue) and the YoY% change in goods producing jobs (red):


Note that in *every* case that the interest rate spread has inverted, or just decreased to nearly zero, within about 18 months YoY growth in goods-producing jobs has declined to less than 0.5%, and usually outright declined. That translates to an annual pace of not more than 7000 goods producing jobs a month. By contrast, in the past several years at least 20,000 goods productions jobs have been added virtually every month:


So if history is a guide, a sharp slowdown in goods producing jobs growth should begin very soon, if not having already begun in February.

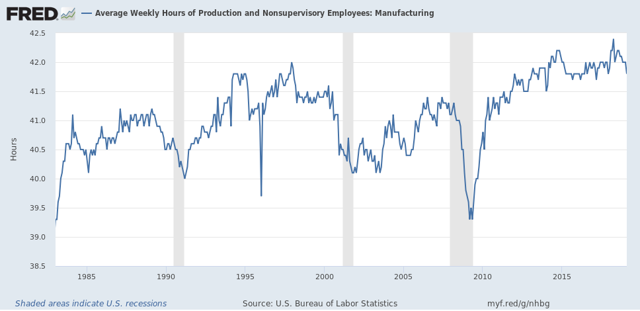
In addition to watching for poor manufacturing and other goods producing jobs growth in Friday’s employment report, an even more forward looking indicator is the average manufacturing work week, which tends to decline even before jobs do. Here’s the history of that number over the past 35 years:


Although it wasn’t the case in 2007, usually the average manufacturing work week declines by nearly an hour if not more before a recession begins.

In the past 10 months, this has declined by -0.6 hours. Any further decline this Friday would be cause for significant concern.

Monday, April 1, 2019

Retail sales flash yellow


 - by New Deal democrat

This morning’s retail sales report for February was disappointing on a monthly basis, but also signals caution for the economy as a whole.

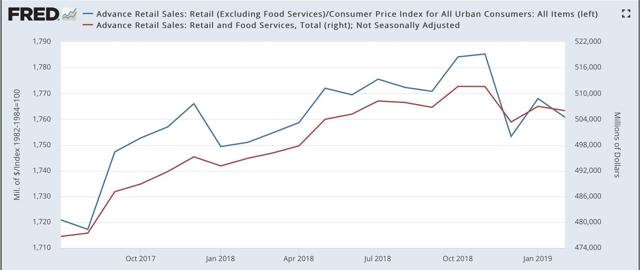
On a nominal basis, retail sales declined -0.2% for the month, although January was revised higher, to +0.7%.

On an inflation adjusted basis, the news was worse, as the monthly decline was -0.4%.

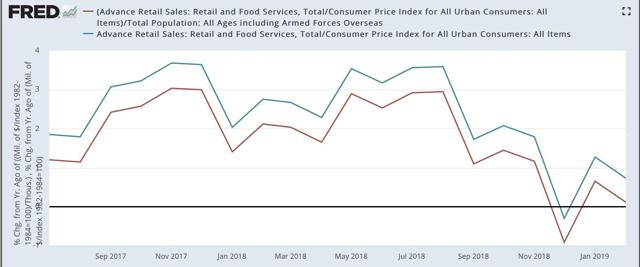
Below are real retails sales for the last few years, and because it is a long leading indicator, real retail sales per capita (in red):


Both of these last made new highs in November. Because there is a lot of noise in the data, it is almost impossible to know whether or not this is true signal.

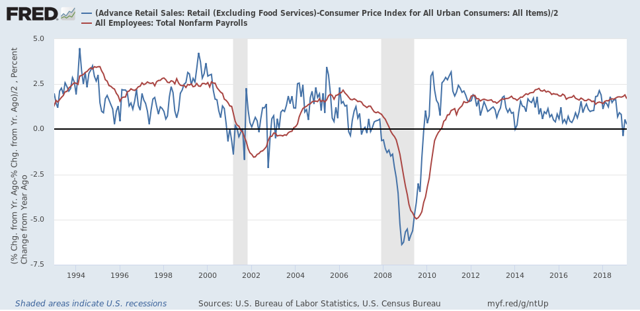
Although the relationship is noisy, because real retail sales measured YoY tend to lead employment (red in the graph below) by a number of months, here is that relationship for the past 25 years:


This is yet another sign that employment gains are likely to downshift significantly over the next several months.

Next, here are both forms of real retail sales YoY recently:


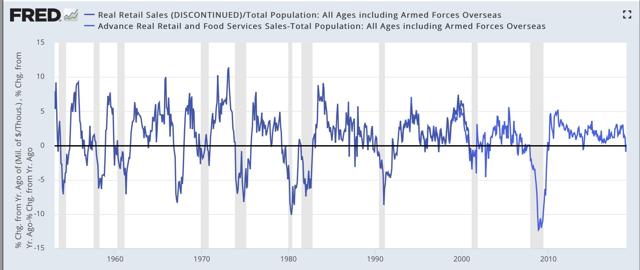
And here are real retail sales per capita YoY, going all the way back to 1948:


In the last 70 years, this measure has always turned negative at least shortly before a recession has begun. There are no false negatives. While there are about a dozen false positives for a single negative month, there are only four false positives for consecutive negative readings — 1966, 1995, 2002, and early 2006. 

Real retail sales per capita YoY just escaped making its second negative reading in three months. So while sales are definitely sounding a note of caution - call it a yellow flag - they aren’t flashing red at this point.

Sunday, March 31, 2019

No, the Meuller report ***DID NOT*** “find no collusion!”


 - by New Deal democrat

This past week I nearly became apoplectic about he malfeasance of much of the press and the punditry reporting of Barr’s 6 paragraph substantive “summary” (3 paragraphs each as to “collusion” and “obstruction of justice”) of Mueller’s roughly 300 page report.

As an initial matter, because Mueller’s grand jury is continuing to meet, and there are still subpoenas and witnesses outstanding, it is incorrect to say that “the investigation” has concluded. clearly “the investigation” is ongoing. What *has* concluded is Mueller’s involvement as special counsel, now that an Attorney General has taken over who did not have to recuse himself. Keep that basic point in mind.

But that’s not what got me livid. Much has already been covered by others. But it is one important, even fundamental, aspect of Barr’s executive summary on which I wanted to focus.

Start with the fact that Barr is a very good attorney. He is going to choose his words, and what he cites and what he omits with great care. Now, this is the *totality* of the language from the actual Mueller report that Barr quotes as to collusion:   


“[T]he investigation did not establish that members of the Trump Campaign conspired or coordinated with the Russian government in its election interference activities.”

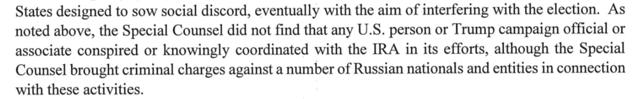
Barr repeats this formulation virtually verbatim twice more in his letter. Here’s the second time:


Stop right there. Let me just slightly reword Barr’s money quote:

“[T]he investigation established that members of the Trump Campaign did not conspire or coordinate with the Russian government in its election interference activities.”

All I did was change the phraseology (in italics) slightly. But the meaning is much more definite and sharper. In my formulation above:

1. There was a finding.
2. The finding was no collusion.

But in the quote which Barr cites, and refers to twice more, it states:

1. There was no finding.
2. The “no finding” was that there was collusion.

Notice that the first formulation above is much stronger than the second. And yet, three times in his executive summary, Barr chooses the second - in circumstances where, if the first were true, he certainly would have used that instead.

While the “no finding” formulation is consistent with a “finding of no collusion,” it is also consistent with other readings: 

1. The investigation isn’t complete yet (which is almost certainly a correct statement).
2. The evidence is inconsistent, weak, or contradictory.
3. There are too many unknowns to come to a conclusion.
4. While the evidence of collusion is strong, it is not strong enough to support a jury verdict beyond reasonable doubt.

To reiterate, Barr is a seasoned attorney. He chose the weaker rather than the stronger formulation for a reason.  Again, if the stronger statement were the true one, don’t you think he would have used the stronger statement? That he chose the weaker statement is telling. The reason, almost certainly, is that the stronger formulation is not correct, and that some version of the 4 weaker possibilities I’ve listed above is the correct factual statement.

Further, as it was elsewhere pointed out a few days ago (sorry, lost the link),  the bracketed [T] in Barr’s quote of Mueller is doing a lot of work. Because it means that there was a first part of the sentence that was omitted. Put that together with the fact the Mueller’s quote then specifically references that “the investigation did not establish ...” and there is compelling evidence that the first part of the actual sentence was a qualifier.

In the first place, had the first part of the sentence been a positive statement, Mueller would not have repeated the phrase “the investigation” in the second part. It would have been something like “The investigation demonstrated that at all time Donald Trump and his Campaign acted lawfully, and thus it did not establish ...” 

Almost certainly the first part of the sentence is something like “Although...’” “Since ...’” or “Despite ...” followed by “the investigation...”,  or a formulation like “The grand jury’s work is incomplete, and so the investigation ...”

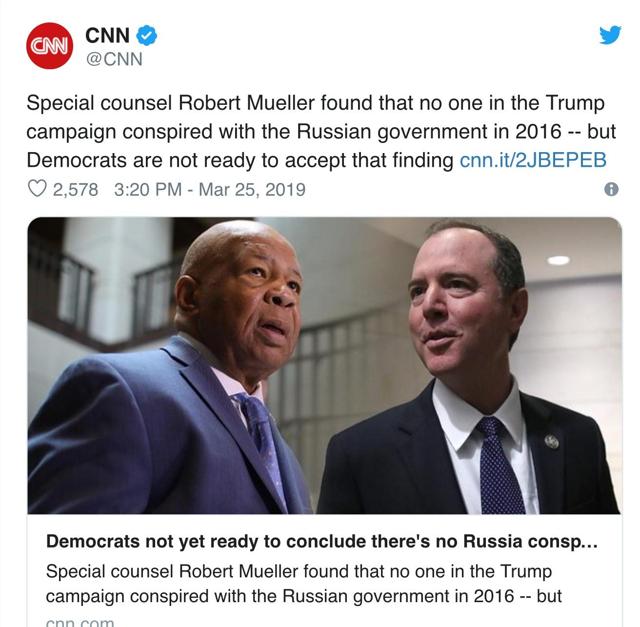
Yet the press and most commentary wrote as if Barr had chosen the stronger formulation I discussed above. Here are some examples:


CNN:

Reuters:
 

 Presidential candidate Tulsi Gabbard:


Even, surprisingly, Josh Marshall:

Aside from the fact that none of these people has read the actual Mueller report, the simple fact is they are all incorrect as to what Barr stated as well.

And that probably tells you why Barr, who putting it most charitably, as Trump’s attorney general was going to “tell the truth with the best foot forward,” pounded this quote 3 times in his three paragraph discussion of the collusion issue: because he wanted people who aren’t versed in parsing attorney language to jump to the exact conclusion they reached: the “no finding” of collusion became a “finding of no collusion.”

There is no such “finding of no collusion” in evidence. This is spin, plain and simple. It needs to be corrected.